Bridging Two Worlds: Navigating the Financial Crossroads of Expatriate Life
For many, the expatriate experience represents the ultimate blend of adventure, cultural immersion, and professional growth. For Laura, 32, and her husband Ethan, 38, moving from Philadelphia to Hanoi, Vietnam, was precisely that. Over the past two years, the couple has leveraged the unique economic landscape of Southeast Asia to accelerate their personal development, pursue graduate education, and explore the region. However, as they look toward a future that includes returning to the United States, starting a family, and purchasing a home, they find themselves at a critical financial juncture.

Laura, currently pursuing a Master’s in Public Health, and Ethan, an educator at an international school, are grappling with the "unknowns" of international living. Their story—a quintessential case study in modern financial planning—highlights the tension between the freedom of global mobility and the looming realities of domestic stability.
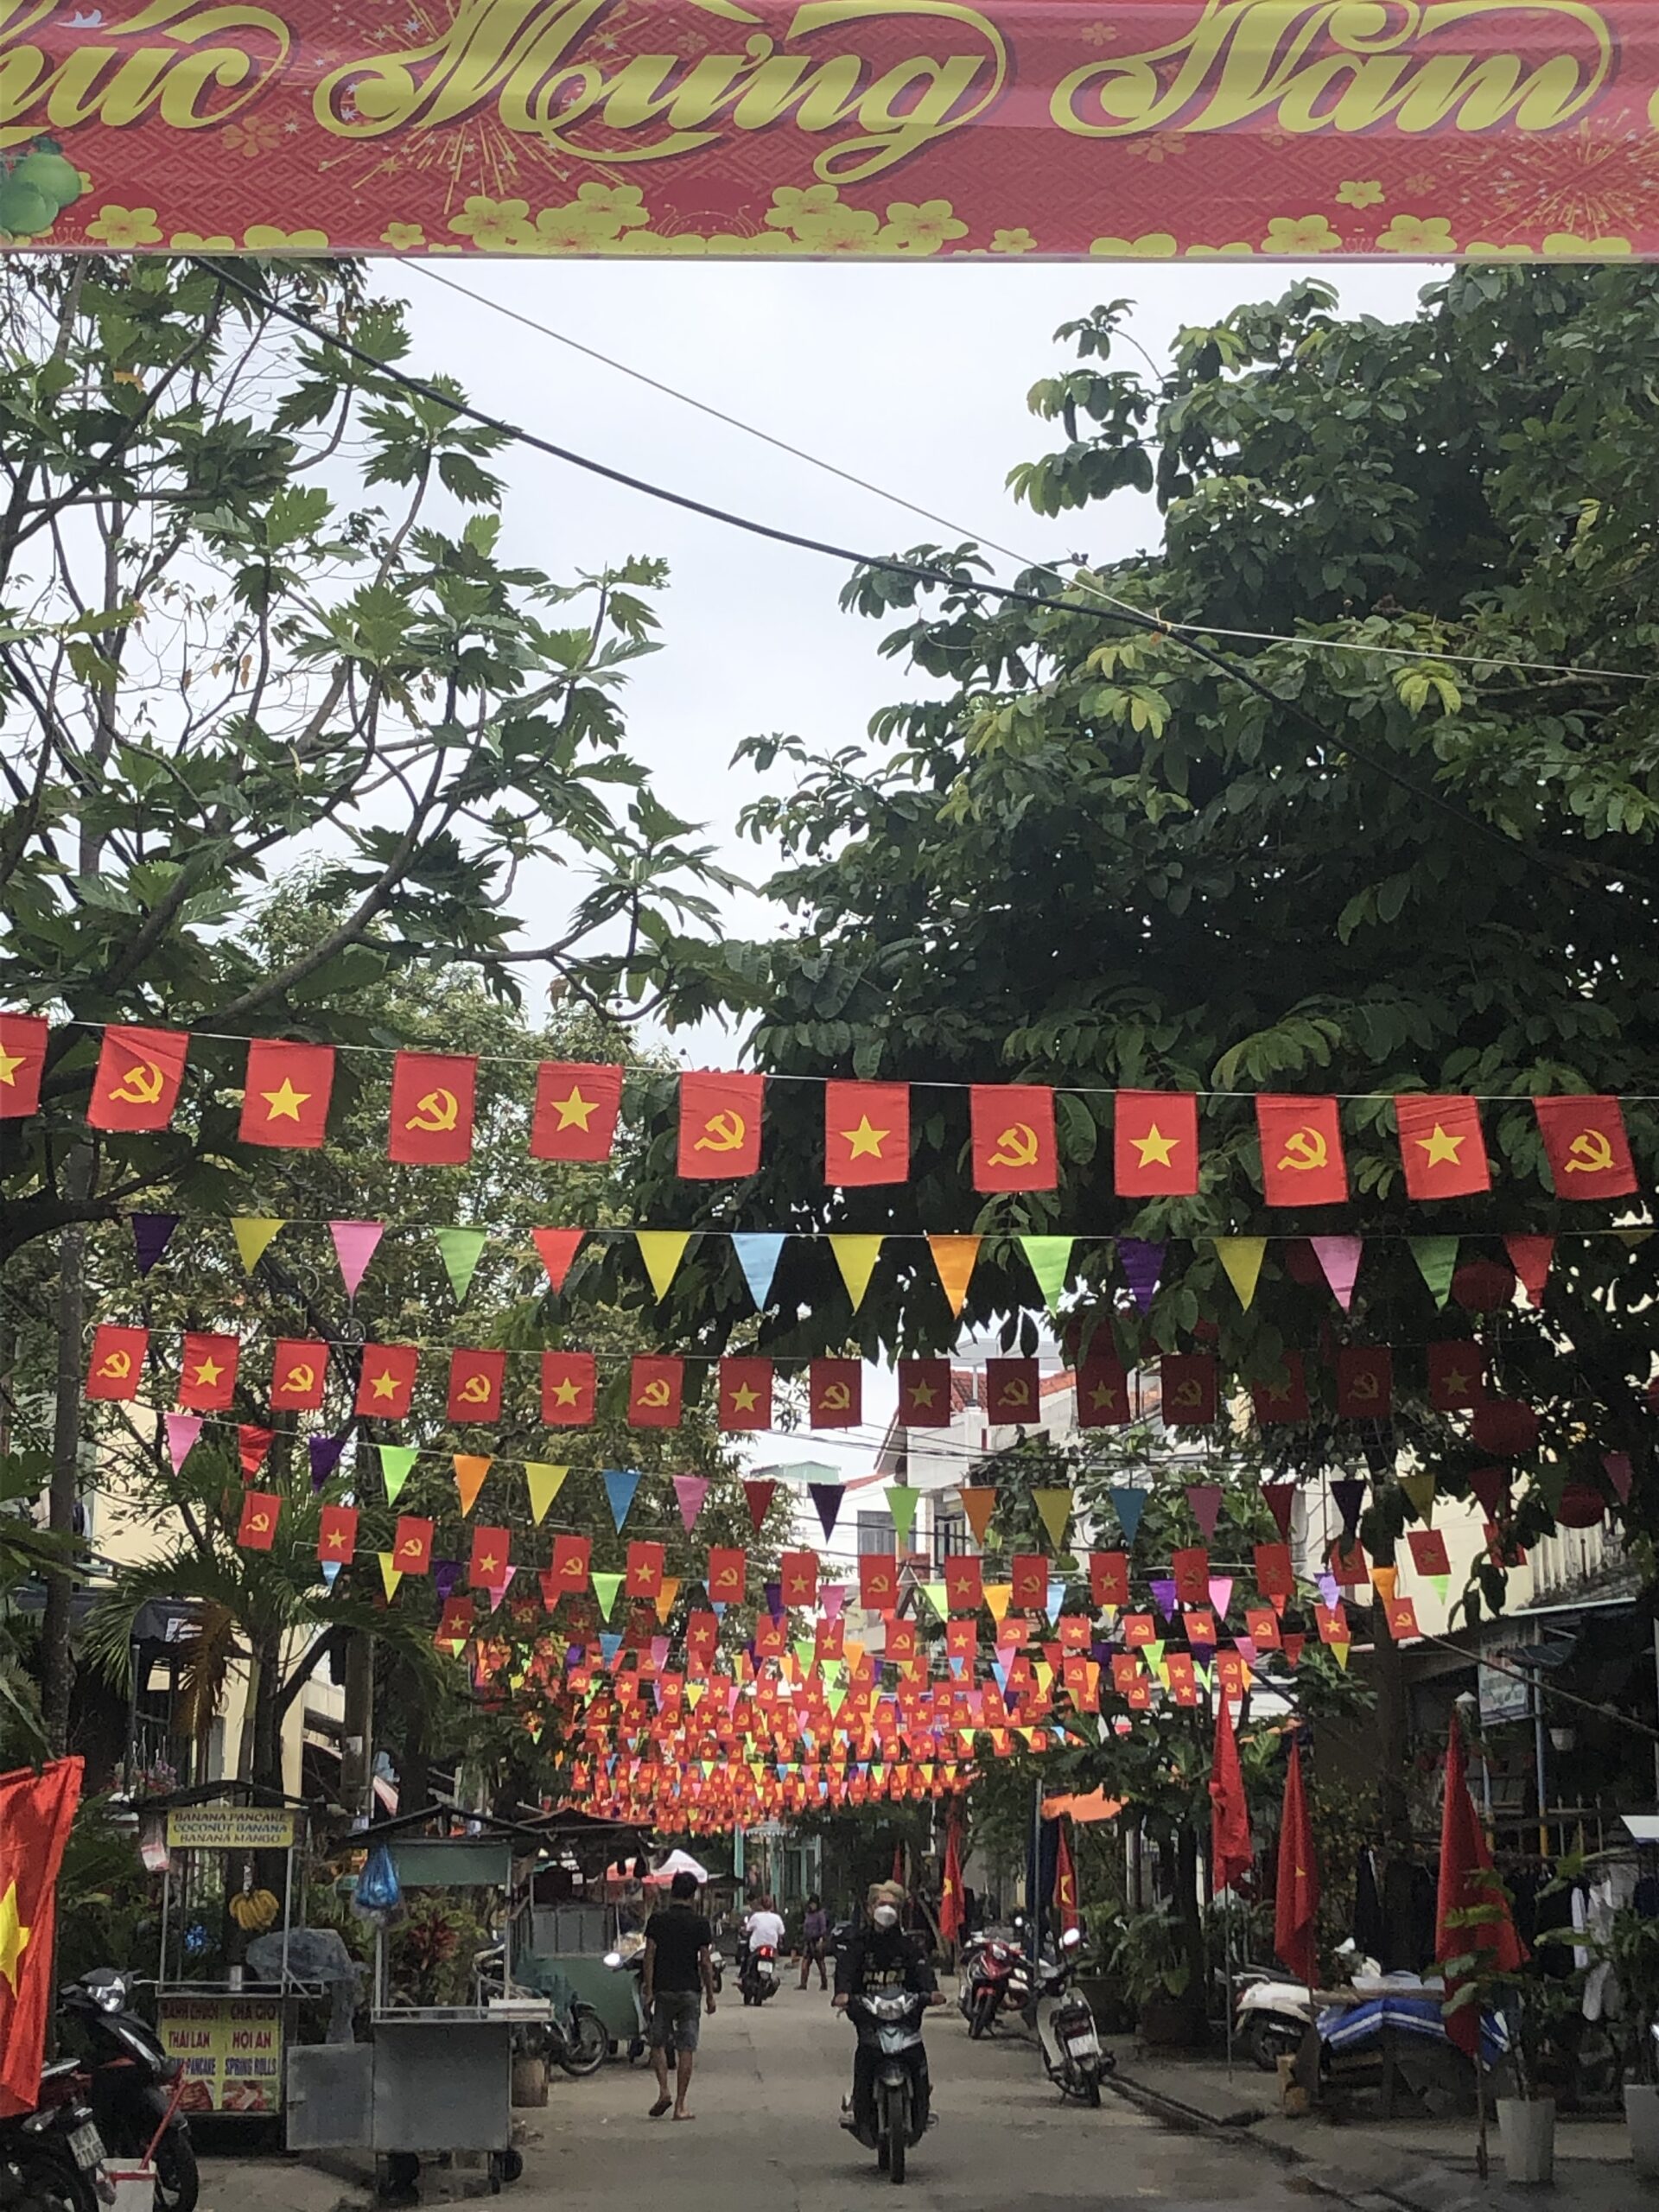
The Journey: From Philadelphia to Hanoi
The couple’s trajectory began with a shared commitment to financial discipline. Before their move, both were burdened by significant debt. Within four months of meeting, Ethan successfully cleared $80,000 in student loans, a feat that inspired Laura to tackle her own $60,000 debt shortly thereafter. This "debt-averse" mindset has been the cornerstone of their partnership.

Life in Hanoi has provided a stark contrast to their previous lives. Ethan’s expat package, which covers housing and annual flights home, has allowed the couple to live on a modest budget while aggressively saving. They have embraced the local lifestyle—enjoying $0.75 bowls of pho, affordable gym memberships, and a rich social life—all while maintaining a disciplined savings rate. Yet, the lack of a formal, long-term financial roadmap for their eventual return to the U.S. has triggered a sense of anxiety for Laura, particularly regarding retirement contributions and the high cost of American real estate.

Financial Snapshot: Data and Assets
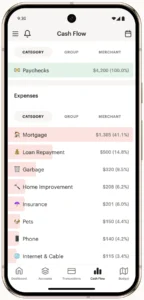
The couple’s current financial standing is a testament to their frugality, yet it also reveals the complexities of managing wealth while abroad.

- Total Net Worth: Approximately $235,708.
- Annual Net Income: $44,154 (with significant fluctuations due to student status).
- Monthly Expenses: $1,741 (notably low due to employer-covered rent).
- Debt: $0.
Their asset allocation is heavily skewed toward cash, with $76,500 held in a high-yield savings account designated for a future home purchase. They also maintain various retirement accounts, including 401(k)s, 403(b)s, and a small pension fund from Ethan’s teaching tenure in Pennsylvania.

Strategic Analysis: The "Cash vs. Invest" Dilemma
A central question posed by Laura is whether their desire to pay cash for a home upon returning to the U.S. is sound. Financial experts, including Frugalwoods founder Liz Thames, generally advise against this.

The Opportunity Cost of Liquidity
The primary argument against paying cash for a home is the "opportunity cost." Money tied up in a house is illiquid and typically earns a return only equal to the mortgage interest rate saved. By contrast, capital invested in the stock market historically averages a 7% annual return. By opting for a mortgage, the couple could potentially keep their cash invested in index funds, allowing their net worth to grow more aggressively over time.

The Hedge Against Inflation
Furthermore, a mortgage is a hedge against inflation. Because a fixed-rate mortgage is paid back in "future dollars"—which are theoretically worth less than current dollars due to inflation—the real cost of the debt decreases over time. For a young couple, maintaining a mortgage allows them to preserve their capital for retirement contributions and emergency liquidity.

Official Guidance and Future Planning
When navigating the complexities of international finance, experts emphasize several key steps for the couple to ensure stability:

1. Understanding Expat Tax Rules
Contributing to retirement accounts while abroad requires careful navigation of the Foreign Earned Income Exclusion (FEIE). Laura and Ethan must consult with a tax professional to ensure they have enough taxable income to remain eligible for IRA contributions. Furthermore, the possibility of a "spousal IRA" could be a viable path for Laura while she is a full-time student.

2. The Pension Rabbit Hole
Ethan’s pension through the Pennsylvania School Employees’ Retirement System (PSERS) represents a significant, yet opaque, asset. Experts recommend that the couple contact a union representative or the PSERS office directly to clarify the impact of their time abroad on his vesting schedule. They must also consider whether returning to public school teaching in the U.S. would disqualify them from certain Social Security benefits or consolidate their previous years of service.

3. Investment Optimization
The couple holds several legacy accounts from previous employers. A critical recommendation is to perform a "rollover" of these 401(k) and 403(b) accounts into a single IRA. This consolidation allows them to:

- Gain control over investment choices.
- Reduce management fees by selecting low-cost index funds.
- Streamline their financial tracking, which may alleviate Laura’s anxiety regarding their future.
Implications: Moving Toward Stability
The "anxiety" Laura feels is common among expatriates in a "holding pattern." However, the data suggests they are in a strong position. The transition back to the U.S. will undoubtedly involve a higher cost of living, but their history of aggressive debt repayment and consistent saving suggests they possess the behavioral discipline to adapt.

Preparing for the Transition
To soften the impact of moving back, the couple should focus on:

- Automation: Once they return to the workforce, setting up automated transfers to retirement and brokerage accounts will remove the emotional burden of decision-making.
- Diversification: They should move away from being "overbalanced" on cash. While having a home-buying fund is prudent, once that goal is achieved, surplus cash should be funneled into tax-advantaged investment vehicles.
- Education: By reading foundational texts like JL Collins’ The Simple Path to Wealth, the couple can demystify the stock market and gain confidence in their investment strategy.
Conclusion
Laura and Ethan are not "behind" in any objective sense; rather, they are in a unique phase of life that requires a shift in perspective. Their time in Vietnam has provided them with a financial cushion that many of their peers in the U.S. lack. By consolidating their assets, embracing the strategic use of mortgage debt, and maintaining their frugal habits, they are well-equipped to navigate the transition back home. The key to their future success lies not in the perfection of their plan, but in their continued ability to act with intention and discipline, regardless of which side of the ocean they call home.