The Inflation Squeeze: Navigating Rising Costs in a Volatile Economic Landscape
The simple act of filling up your gas tank has become a jarring reminder of the current economic reality. As you watch the numbers climb on the pump, the total serves as a tangible indicator of a broader trend: the cost of living is rising at a pace not seen in recent months. According to the latest Consumer Price Index (CPI) report, inflation surged to 3.7% in September, a jump that has caught both consumers and market analysts off guard.
For individuals navigating their 20s and 30s—a demographic often balancing student loans, entry-to-mid-level salaries, and long-term savings goals—this shift is more than just a headline. It is a signal that your personal budget requires immediate recalibration. With gasoline and energy costs acting as the primary catalysts for this inflationary spike, the ripple effects are beginning to touch everything from grocery store aisles to the interest rates on your credit cards.
The September CPI Data: By the Numbers
The Consumer Price Index (CPI) is the definitive yardstick for measuring the average change over time in the prices paid by urban consumers for a market basket of consumer goods and services. In September, that basket became significantly more expensive.
The 3.7% year-over-year increase represents a marked acceleration from the 3.4% readings seen in both July and August. Economists, who had forecasted a more moderate increase of approximately 3.6%, are now reassessing their projections for the remainder of the year. Perhaps more concerning to policymakers is "core inflation"—a metric that excludes the volatile food and energy sectors—which climbed to 2.6%, up from 2.4% the previous month. This suggests that inflationary pressures are becoming deeply embedded in the broader economy, rather than being confined solely to the gas pump.
A Chronology of Economic Pressure
To understand the current environment, one must look at the recent trajectory of these figures. Throughout the summer, there was a tentative sense of optimism that inflation might be cooling. However, September’s data shattered that narrative.
- July & August: The economy hovered around a 3.4% inflation rate. While still elevated, the stability provided a sense of predictability for household budgeting.
- Early September: Analysts began to notice subtle shifts in energy markets, particularly as diesel prices began to reach historic highs, averaging $6.29 per gallon.
- Mid-September: The Bureau of Labor Statistics released the CPI data, confirming the 3.7% jump.
- Late September/Early October: Following the report, stock indexes retreated, and bond yields climbed, reflecting a market that is pricing in a more hawkish stance from the Federal Reserve.
This timeline underscores the speed at which macroeconomic factors can degrade purchasing power. For the average consumer, the shift from 3.4% to 3.7% might seem marginal, but when compounded over the course of an annual budget, it represents hundreds—if not thousands—of dollars in lost disposable income.
Why Energy is the Engine of Inflation
The primary driver behind the September spike is undoubtedly the energy sector. Gasoline prices alone surged by 9.1% during the month, a single category that accounted for more than half of the total monthly increase in the CPI.
When zooming out to a 12-month perspective, the picture becomes even more stark: energy prices have risen by 20.4% over the past year, with gasoline prices specifically climbing by 34.2%. The surge in diesel prices is particularly damaging to the wider economy. Because diesel is the fuel of choice for the heavy-duty trucking and logistics industries, these costs are rarely absorbed by the shipping companies themselves. Instead, they are passed down the supply chain. When it costs more to transport goods from a regional distribution center to a local supermarket, those costs appear on your grocery receipt. This "logistics inflation" creates a secondary wave of price increases that persists even if crude oil prices fluctuate.
Official Responses and Market Sentiment
The reaction from the financial sector was swift. Analyst Adam Crisafulli noted that the September report offered "little room to downplay" the severity of the increase. When the data dropped, the markets responded with characteristic volatility: stock indexes slipped as investors adjusted their portfolios for a higher-interest-rate environment, and bond yields climbed, signaling that lenders are demanding higher returns in the face of inflation.
David Royal, chief investment officer at Thrivent, highlighted the fundamental disconnect between current economic reality and the Federal Reserve’s long-term objectives. "Inflation remains well above the Fed’s 2% target," Royal explained. "In this environment, the prospect of imminent rate cuts looks increasingly unlikely."
Implications for the Federal Reserve
The Federal Reserve, led by its commitment to price stability, is currently in a difficult position. Having raised its benchmark interest rate to a target range of 3.75% to 4%, the central bank is now telegraphing that further hikes may be necessary before the year concludes.
The market has reacted accordingly. Prior to the release of the September data, the probability of a rate hike at the October 27-28 meeting was estimated at roughly 20%. Following the release, that probability skyrocketed to 50%. With another meeting scheduled for December 8-9, the Fed has two remaining windows in the calendar year to curb demand and rein in the overheating economy. For consumers, this means the cost of borrowing—whether for a car loan, a mortgage, or a credit card balance—is likely to remain elevated or increase further.
Budgeting in a High-Inflation Climate: Actionable Strategies
For those in their 20s and 30s, the temptation might be to "wait it out." However, proactive management is the most effective way to weather an inflationary cycle.
1. Revisit Your Budgeting Framework
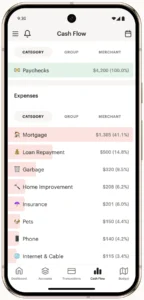
If you are still using the same budget you built a year ago, it is already obsolete. Return to a classic, category-based framework. Break your income into "Fixed" and "Variable" buckets. Update your gas and grocery line items to reflect current prices, not what you wish they were.
2. The Emergency Fund as a Buffer
Rising prices and rising interest rates create a double squeeze: your expenses go up, and the cost of credit (if you need it) also goes up. An emergency fund is your only shield. If you do not have one, start small. Even a modest, automated transfer of $50 per paycheck into a high-yield savings account will build a buffer over time. Aim for one month of essential expenses initially, with a long-term goal of three to six months.
3. Understanding Variable Interest Rates
It is critical to remember that most credit cards are tied to the prime rate. When the Fed raises its benchmark rate, your credit card APR often follows within one or two billing cycles. If you carry a balance, high inflation is effectively making that debt significantly more expensive. Prioritizing the payoff of high-interest debt is no longer just a "good idea"—it is a critical defensive move against rising interest expenses.
Frequently Asked Questions
What exactly does the Consumer Price Index (CPI) measure?
The CPI is a statistical estimate constructed using the prices of a sample of representative items whose prices are collected periodically. It provides a snapshot of the change in the cost of living for consumers, allowing the government and the Federal Reserve to monitor the effectiveness of monetary policy.
Why did gas prices have such an outsized impact in September?
Gasoline is a high-frequency purchase for most households, meaning price changes are felt immediately. Because it increased by 9.1% in a single month, it acted as a "demand shock" to personal budgets, leaving less room for discretionary spending.
How do I protect my savings from inflation?
While cash in a savings account loses purchasing power during high inflation, it remains necessary for liquidity. Look for High-Yield Savings Accounts (HYSAs) that offer interest rates closer to the current inflation rate to minimize the erosion of your wealth.
Is a 3.7% inflation rate a crisis?
While not an economic collapse, it is a significant warning sign. It indicates that the "soft landing" sought by the Fed is becoming more difficult to achieve. It is a signal to transition from a growth-oriented mindset to a wealth-preservation mindset until the data shows a consistent downward trend.
Final Thoughts: The Path Forward
The September inflation report is a sobering reminder that economic conditions are fluid. While a 3.7% inflation rate is not a catastrophe, it is an undeniable signal to adjust your financial behavior. By focusing on your gas and grocery expenditures, automating your savings, and paying down variable-rate debt, you can navigate these headwinds with confidence. Small, deliberate changes made today will prevent the need for desperate, reactive measures if prices continue their upward climb this winter. Stay informed, stay diligent, and prioritize the stability of your personal balance sheet.