The Resurrection of the 60/40 Portfolio: Why High Bond Yields Spell Relief for Balanced Investors
October 13, 2026
By Ben Carlson (Enriched & Expanded Financial Review)
Main Facts
The traditional 60/40 portfolio—consisting of 60% equities and 40% fixed income—has officially survived the structural turbulence of the 2020s, proving its critics wrong. Despite a decade defined by plummeting bond values, soaring inflation, and historic interest rate shifts, diversified strategies have thrived. However, this success came with an unexpected twist: instead of bonds supporting equities during market downturns, a roaring stock market compensated for abysmal fixed-income returns.
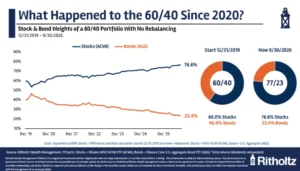
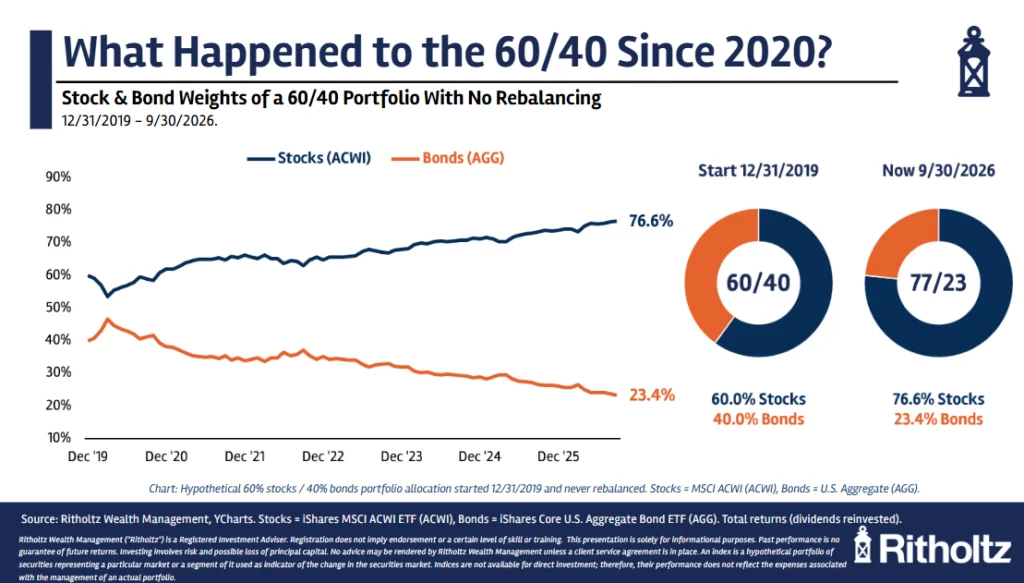
As the financial landscape enters late 2026, a fundamental shift is underway. High-quality bonds are now yielding upwards of 5% for the first time in nearly two decades. This dramatic pivot gives investors a rare luxury: the ability to secure attractive, predictable returns from the fixed-income portion of their portfolios without relying exclusively on aggressive equity performance. Consequently, financial experts are urging investors to look closely at their current asset allocations. Due to the massive equity bull market of the 2020s, many portfolios that started the decade as balanced 60/40 configurations have experienced severe "style drift," organically morphing into aggressive 77/23 allocations. With bond yields finally earning their keep, market analysts argue it is time to harvest equity gains and rebalance back toward target weights.
Chronology of the 2020s Investment Landscape
To understand how modern portfolios arrived at this crossroads, it is necessary to retrace the economic evolution of the 2020s:
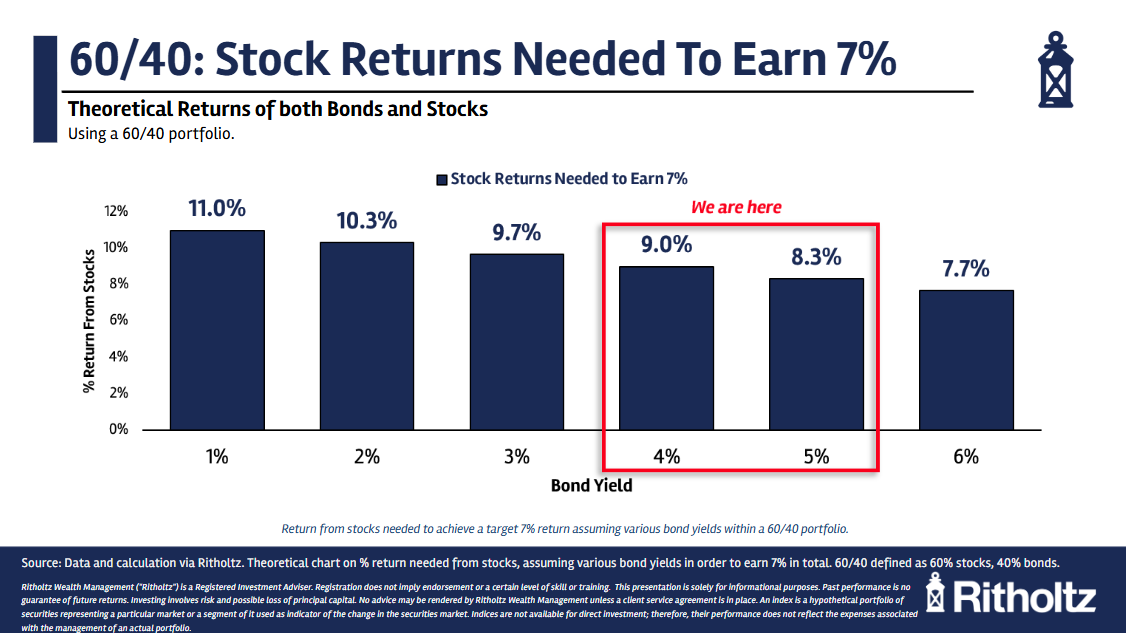
- Early 2020 (The Pandemic Shock): At the height of global lockdowns, central banks slashed interest rates to historic lows. Bond yields plummeted, forcing income-seeking investors into a corner. Traditional 60/40 math broke down; hitting a standard 7% annual return target required heroic assumptions about future stock market performance.
- The 2020–2024 Era of "TINA" (There Is No Alternative): Facing dismal fixed-income payouts, investors abandoned diversification. Many shifted from a 60/40 allocation to an 80/20 profile, while others went entirely all-in on equities. This risk-on behavior was handsomely rewarded by an unexpected, prolonged stock market boom.
- Mid-Decade Monetary Tightening: To combat runaway inflation, central banks embarked on aggressive rate-hiking campaigns throughout the mid-2020s. While this crushed existing bond prices in the short term, it laid the groundwork for a new generation of high-yielding fixed-income assets.
- Late 2026 (The Rebalancing Imperative): Today, high-quality bonds comfortably yield over 5%. Having ridden an epic, tech- and AI-driven equity bull market for years, investors now face a stark portfolio imbalance. Untouched 60/40 portfolios from 2020 are now heavily equity-weighted (approaching 77/23), prompting a necessary industry-wide conversation about prudent risk management and disciplined rebalancing.
Supporting Data & Market Metrics
The mechanics behind the 60/40 evolution are illustrated by several core financial metrics and structural shifts observed over the decade:
- The Return Hurdle: Historical analytical models show that when bond yields hovered near zero during the early pandemic, a balanced portfolio required aggressive equity returns simply to achieve a baseline 7% annual return.
- Vanguard LifeStrategy Performance: Despite gloomy forecasts predicting the death of the 60/40 model at the start of the decade, funds like the Vanguard LifeStrategy 60/40 have delivered robust performance, averaging nearly 8% per year throughout the 2020s. This resilience was driven almost entirely by the extraordinary strength of the equity markets, which effectively masked the worst decade for bonds in modern history.
- The Yield Rebound: For nearly 20 years, investors operated in a repressed yield environment. Today, risk-free and high-grade corporate bonds yielding over 5% represent a generational shift. A vast cohort of new investors—and many mature portfolios looking to de-risk—are experiencing true fixed-income returns for the first time in their investing lifetimes.
- Style Drift Metrics: A hypothetical 60/40 portfolio established in January 2020 that was left entirely untouched has drifted dramatically due to asymmetric asset class performance. By late 2026, the compounding outperformance of stocks has skewed the asset mix to roughly 77% equities and 23% fixed income, drastically altering the portfolio’s original risk profile.
Official Perspectives and Expert Commentary
Financial advisors, wealth managers, and institutional researchers have weighed heavily on the changing dynamics of portfolio construction.
- The Risk Management Argument: Industry veterans emphasize that diversification is not an optimization tool designed to maximize returns every single year; rather, it is an insurance policy against an unpredictable future. As analysts note, "The reason you diversify your portfolio is because no one knows what comes next. If you knew what was going to happen, you wouldn’t need to diversify."
- The Behavioral Challenge of Rebalancing: Behavioral finance experts point out the psychological friction inherent in rebalancing during an extended bull market. Selling top-performing equity assets to buy lagging bonds feels counterintuitive to human psychology. However, seasoned advisors stress that prudent risk management requires rebalancing before a market regime shift occurs.
- The Generational Divide: Wealth management firms have highlighted a unique psychological hurdle for newer investors who entered the market post-2008. Having only known a world of zero-percent interest rates and perpetual equity outperformance, younger investors must now learn how to value and integrate fixed income as a primary growth and stability engine.
Implications for Investors
The maturation of the 2026 economic environment carries profound implications for retail investors, institutional funds, and retirement planners alike:
1. The End of Forced Speculation
During the low-rate era, investors were forced up the risk curve simply to maintain purchasing power against inflation. Today, with bonds yielding 5%+, investors no longer need the stock market to "knock it out of the park" to secure a comfortable retirement. Fixed income is finally earning its keep.
2. The Necessity of Rebalancing Policies
An asset allocation strategy is incomplete without an explicit rebalancing framework. Leaving a portfolio on autopilot during a historic bull market exposes investors to unintended tail risk. While letting winners run is tempting, failing to trim outsized equity positions leaves portfolios vulnerable to sharp, unexpected macroeconomic corrections—whether driven by a sudden recession, geopolitical shocks, or the eventual cooling of the artificial intelligence infrastructure boom.
3. Tailoring to Individual Risk Profiles
Ultimately, there is no single "perfect" portfolio. Effective asset allocation must reconcile an investor’s unique time horizon, short-term liquidity needs, emotional disposition, and long-term financial goals. Rebalancing back to target weights (such as returning a drifted 77/23 portfolio back to a disciplined 60/40 split) is designed not to maximize absolute returns, but to minimize regret and protect capital when market cycles inevitably turn.
As financial markets look toward the remainder of the decade, the takeaway is clear: the 60/40 portfolio is not dead. It has simply evolved, proving that disciplined asset allocation and traditional diversification remain the ultimate bedrock of resilient long-term investing.