The Expat Financial Crossroads: Balancing Global Living with Future Stability
For many, the expatriate experience represents the ultimate dream: an immersion into a new culture, professional growth in an international setting, and the unique opportunity to build savings while traveling the world. For Laura and Ethan, a couple originally from Philadelphia now living in Hanoi, Vietnam, that dream has become a reality. Yet, as they approach the three-year mark of their overseas tenure, the transition from "adventurous living" to "long-term planning" has brought a wave of financial anxiety.

While they have successfully navigated the complexities of international life, they are now grappling with the looming question that faces all expats: How does one bridge the gap between an affordable life abroad and the high-cost reality of returning home?
The Current Landscape: A Life of Freedom and Flux
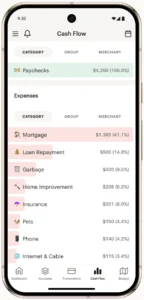
Laura, 32, and Ethan, 38, moved to Hanoi for Ethan’s career as an English literature teacher. Their lifestyle is a masterclass in intentional living. By leveraging an expat package that covers rent and international flights, the couple has kept their monthly expenses remarkably low—approximately $1,741 per month. This has allowed them to pursue hobbies like rock climbing, yoga, and knitting, while extensively traveling across Southeast Asia.

However, the lack of a permanent, long-term roadmap has created friction. Laura, currently a full-time student pursuing a Master’s in Public Health, is acutely aware of the "career gap" and the potential financial impact of their eventual return to the United States. With plans to start a family and purchase a home in the future, the couple finds themselves at a critical juncture where their current, low-cost lifestyle must eventually yield to the economic pressures of stateside living.

Chronology of Their Financial Journey
The couple’s financial history is defined by a rigorous commitment to debt repayment. Their journey to financial stability began shortly after they met, when Ethan finalized the payoff of $80,000 in student loans. Inspired by this momentum, Laura followed suit, clearing $60,000 of her own debt in just 11 months.

- The Debt-Repayment Phase: Within their first five years together, the couple aggressively eliminated over $140,000 in combined debt.
- The Transition Abroad: Moving to Hanoi provided a "financial sanctuary," allowing them to save aggressively while enjoying a significantly lower cost of living.
- Education Investment: Ethan recently completed an accelerated Master’s in Education, while Laura is currently finishing her Master’s in Public Health. These investments in human capital were made strategically, with most costs covered by employer funding or scholarships.
- The Present Moment: As of mid-2023, the couple is debt-free and holds a net worth of approximately $235,708. Their primary concern is no longer debt, but rather the preservation of this capital and the logistics of transitioning back to the U.S. labor market.
Supporting Data: An Asset Overview
The couple’s financial profile is robust, characterized by a high liquidity-to-debt ratio. Their total assets of $235,708 are divided between retirement vehicles and house-savings cash.

| Asset Class | Total Value | Notes |
|---|---|---|
| Cash/Savings | $104,370 | Includes house savings and emergency funds |
| Retirement Accounts | $112,555 | Includes 401k, 403b, IRA, and Pension |
| Taxable Brokerage | $18,783 | Managed via Ellevest |
The $104,370 in cash is a significant point of contention. While it provides the security needed for a future home purchase, it currently sits in high-yield savings accounts. The couple is now weighing the opportunity cost of holding this much cash versus the potential returns of a more diversified investment strategy.

Professional Analysis and Recommendations
To address their concerns, we turn to the expertise of financial mentor Liz "Frugalwoods" Thames, who highlights several key strategic adjustments for the couple.

1. The "Cash for a House" Fallacy
A primary source of anxiety for Laura is the idea of buying a home in cash to avoid mortgage interest. From a mathematical standpoint, this is often an inefficient use of capital. By paying cash, the couple misses out on the power of compounding interest in the stock market. With historical stock market returns often outpacing mortgage interest rates, maintaining a mortgage allows the couple to keep their capital working for them, rather than locking it into an illiquid asset.

2. Retirement Contributions and Expat Status
The couple expressed concern about their two-year hiatus from retirement contributions. As U.S. citizens abroad, their eligibility to contribute to an IRA depends on their specific tax filing status—specifically, whether they have earned income leftover after claiming the Foreign Earned Income Exclusion (FEIE). If they utilize the Foreign Tax Credit (FTC) instead, or if they have non-excluded income, they may be able to resume contributions. Furthermore, the possibility of a "spousal IRA" offers a path for Laura to continue building her retirement nest egg even while she focuses on her graduate studies.

3. Investment Optimization
The couple’s current investment structure is fragmented, with accounts scattered across various providers (Voya, Alerus, Ellevest, etc.). A critical recommendation is to consolidate these legacy 401k and 403b accounts into a single IRA. This allows for greater control over investment selection and expense ratios. By moving funds into low-fee index funds—such as a total stock market index—the couple can minimize administrative fees that currently eat into their long-term growth.

Implications for the Future: Building a Roadmap
The anxiety Laura feels is a common symptom of the "expat transition." Moving back to the U.S. will undoubtedly be a shock, both culturally and financially. The following implications should guide their next steps:

- The "Holding Pattern" is Acceptable: The couple is not "behind" in a way that cannot be corrected. Their primary task is to maintain their current, disciplined spending habits even after their income increases.
- Pension Clarity: Ethan’s PA Teachers Pension (PSERS) is a significant, yet poorly understood asset. Clarifying the specifics of this pension—and how it interacts with potential future public service in the U.S.—is a "must-do" item.
- The Power of Automation: Once they return to the U.S. and re-enter the workforce, the couple should prioritize automating their savings. By treating their retirement and savings goals as non-negotiable monthly expenses, they can mitigate the emotional stress of managing finances in a high-cost environment.
A Path Forward
Laura and Ethan are in a position of strength. They have successfully navigated debt, international relocation, and career pivots. Their anxiety is not a sign of failure, but a sign of maturity—they are now looking at their life through the lens of a long-term horizon.

By focusing on consolidating their accounts, understanding the nuances of expat taxation, and accepting that a mortgage is a tool rather than a burden, they can move forward with confidence. The transition back home will be complex, but with their current foundation of $235,000 in assets and a disciplined, frugal mindset, they are well-equipped to build a stable and prosperous future in the United States.