Staying Power in a Digital World: How Apple Bank Balances Tradition with Modern Ambition
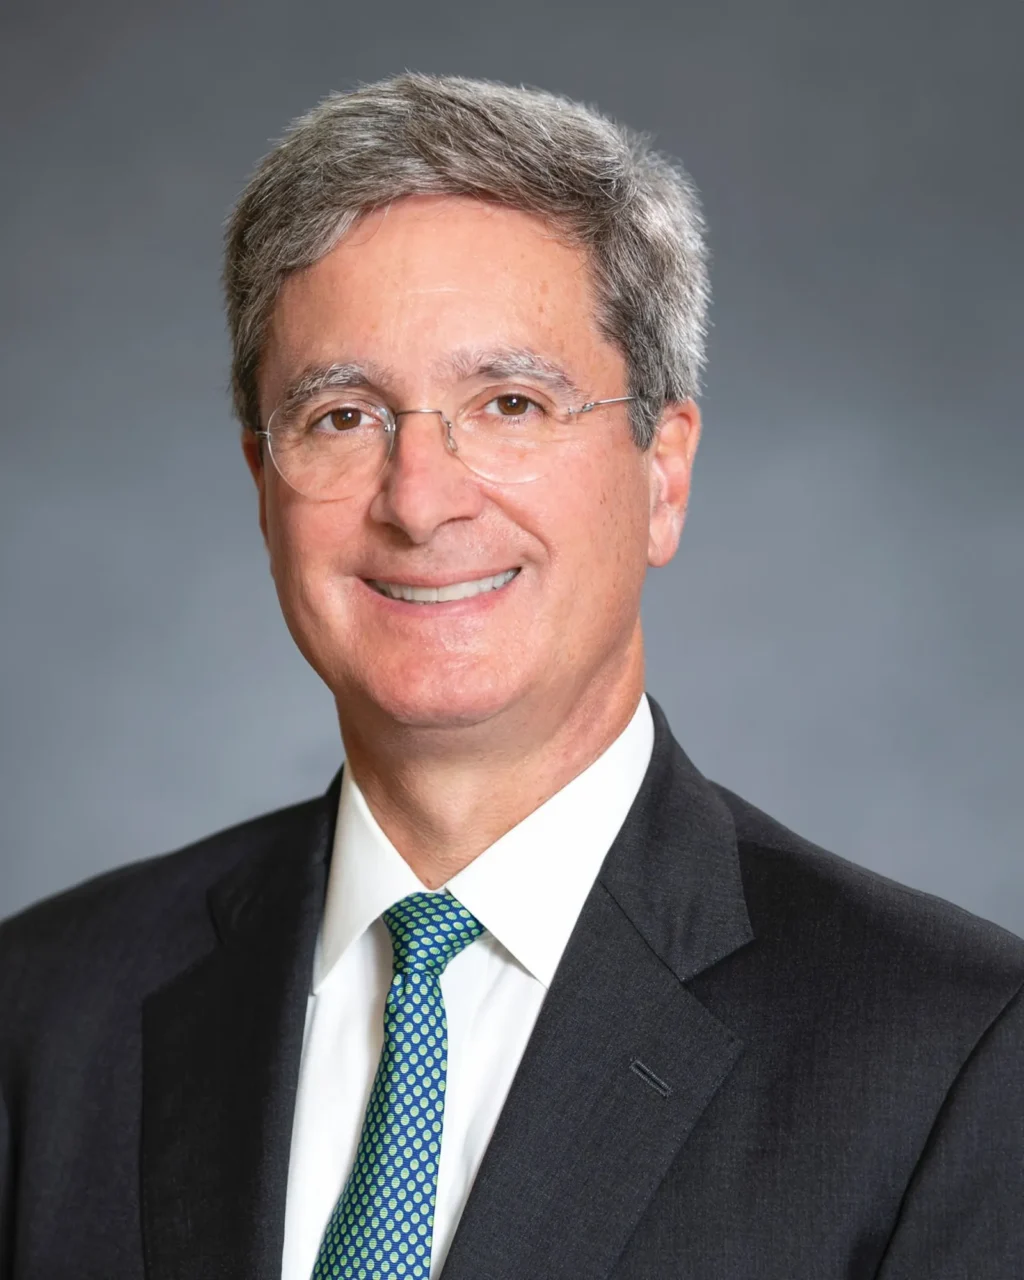
In the hyper-competitive landscape of American retail banking, where global giants and nimble fintech startups engage in a relentless arms race for the "mass-affluent" and younger demographics, New York City-based Apple Bank is taking a different path. While its peers chase digital-only growth and high-net-worth portfolios, the $20 billion-asset, privately held institution remains firmly rooted in its identity as a champion of the middle and working class.
Under the leadership of CEO Steve Bush, who has steered the 161-year-old institution for the past decade, Apple Bank is navigating a delicate evolution. It is a transition defined by a singular question: How does a legacy brand—built on brick-and-mortar relationships with teachers, nurses, and small-business owners—remain relevant in an era where the average consumer’s attention span is measured in milliseconds?
The Main Facts: A Legacy Reimagined
Founded in 1863, Apple Bank has long served as the financial backbone for the “everyday” New Yorker. Its core customer base is composed of the city’s essential workforce—administrators, hospital staff, school employees, and families in the surrounding suburbs. Yet, as Bush candidly admits, longevity does not grant immunity from market shifts.
“It’s a challenge to get the attention of people on the street in a way that it didn’t used to be,” Bush noted in a recent interview. “It’s a digital world. We are trying new paths to enter the collective consciousness to a greater degree than we typically would have done in the past.”
The bank’s strategy is not to abandon its roots but to modernize its outreach. With a marketing budget of approximately $10 million—a figure that has remained consistent over the last four years and is projected to hold steady through 2027—Apple Bank is diversifying its visibility. Current efforts include strategic partnerships with Major League Baseball’s New York Mets and collaborations with youth-focused financial literacy influencers, such as a pair of teenage sisters who run a popular YouTube channel dedicated to money management.
A Chronology of Resilience and Adaptation
To understand Apple Bank’s current posture, one must look at its trajectory over the last century and a half.
- 1863: The institution is founded, positioning itself as a community-centric lender during a pivotal era in American banking.
- The 1930s–2010s: The bank solidifies its footprint in New York, acquiring large, ornate physical branches that, while iconic, eventually become "mausoleum branches"—sprawling, inefficient spaces in a modern era of streamlined digital banking.
- The Last Five Years: The bank experiences a significant growth spurt, with assets increasing by approximately 24%, according to FDIC data.
- Recent Years: Under Bush’s leadership, the bank begins selling off its oversized legacy real estate to fund the opening of smaller, more efficient branches in New Jersey, which have already contributed $1 billion in new deposits.
- Present Day: The Office of the Comptroller of the Currency (OCC) grants conditional approval for Apple Bank to transition from a state charter to a national charter, a strategic move intended to simplify expansion into new markets.
Supporting Data: By the Numbers
The bank’s financial health and operational footprint provide a clear picture of its "middle-market" strategy:
- Asset Growth: A 24% increase over the last five years, signaling robust performance despite the bank’s refusal to pivot to high-risk, high-net-worth client acquisition.
- Physical Presence: 79 branches across New York and New Jersey, with a growing interest in Florida.
- Florida Migration: Apple Bank currently serves approximately 1,200 customers who have migrated from the New York area to Florida, providing a "beachhead" for future expansion.
- Marketing Investment: A steady $10 million annual expenditure, focusing on brand-building rather than aggressive acquisition.
The "Big Bank" Paradox: Opportunity in Friction
One of the most intriguing aspects of Steve Bush’s philosophy is his outlook on the competition. Apple Bank does not attempt to out-spend or out-innovate the “Big Five” U.S. lenders. Instead, it waits for the friction that inevitably accompanies massive scale.
“Big banks annoy people, on a regular basis,” Bush remarked. “99% of the time, their systems work very well. But as a small bank, you need for those banks to have a problem to really have an opportunity. You want to be able to take advantage of those opportunities when they present themselves, but you have to punch through to consciousness.”
Bush believes that despite the digitization of banking, the human element remains a competitive moat. When Apple Bank makes a mistake, customers call the CEO directly. This level of accessibility is a stark contrast to the automated, often opaque, grievance procedures of the nation’s largest financial institutions. For Apple Bank, this "personal touch" is not a marketing slogan; it is a core business proposition.
Implications for the Future
The decision to pursue a national charter is perhaps the most significant indicator of the bank’s future. By simplifying the regulatory burden associated with interstate expansion, Apple Bank is signaling that it no longer views itself solely as a New York City institution.
However, the expansion will be measured. Bush is not looking to be the "most numerous animal on the plains." Instead, the bank is focusing on "recharging the system" by capturing the constant turnover of New York’s population and following its existing customers as they move south.
The transition to a national charter will allow the bank to enter markets that may differ significantly from the New York/New Jersey corridor. Yet, as Bush notes, the bank remains wary of the hubris that can come with age. He pointedly reminds his team that "Credit Suisse failed at 166," a humbling reminder that in the banking industry, history is not a guarantee of future stability.
Conclusion: The Path Forward
Apple Bank is essentially betting that in a world of algorithmic banking, there is still a premium on the "middle-class" experience. By investing in financial literacy for the youth—such as its high-yield savings accounts for children and branch events for local sports teams—the bank is playing a long game. It is cultivating the next generation of loyalists while simultaneously optimizing its physical footprint and regulatory status to capture new markets.
Whether this strategy of "prudent, personal growth" can withstand the relentless pressure of the digital age remains to be seen. But for Steve Bush and Apple Bank, the goal is clear: to remain a reliable, human-centric alternative in an industry that often forgets the people behind the accounts. In the vast, crowded ecosystem of finance, Apple Bank is betting that there is plenty of room for a bank that knows exactly who its customers are—and, more importantly, that its customers know exactly who they are banking with.