Inside the Minds of Self-Made Millionaires: Navigating the Great Wealth Transfer and Inheritance Dilemmas
As the United States stands on the precipice of the largest generational wealth transfer in modern history—an estimated $124 trillion in assets projected to flow from older generations to heirs and charities through 2048—conversations around inheritance have moved from whispered taboos to urgent kitchen-table summits. To understand how everyday affluent Americans are managing this monumental shift, a specialized panel of self-made millionaires has offered a rare, unfiltered look into their private financial planning, family dynamics, and legacy goals.
Main Facts: The Anatomy of the Modern Millionaire
The conversation surrounding wealth in America often conjures images of corporate dynasties, tech moguls, and trust-fund elites. However, the reality of the nation’s millionaire demographic is far more grounded.
The participants in this ongoing study—dubbed the "Millionaires Panel"—are not born titans of industry. They are ordinary people who built their fortunes through decades of diligent saving, calculated entrepreneurship, and strict adherence to living within their means. Hailing from geographically diverse corners of the United States—ranging from the rural expanse of Shoshoni, Wyoming, and West Lakeland, Minnesota, to bustling urban hubs like Virginia Beach and San Diego—these individuals represent a cross-section of American professions. They are former schoolteachers, small-business owners, project managers, and engineers.
To encourage absolute candor regarding sensitive financial matters, the identities of the 30 panelists remain strictly confidential, known only to the research team. This anonymity yielded unprecedented engagement, resulting in a 100% participation rate on the panel’s inaugural survey.
The core mission of the panel is to tackle three of the most challenging questions facing high-net-worth families today:
- Are affluent parents actively talking to their children about wealth?
- Should estates be divided equally among heirs regardless of circumstance?
- Should inheritances be capped to prevent demotivating the next generation?
Chronology: From Quiet Accumulation to the Great Wealth Transfer
The journey of these millionaires reflects a broader macroeconomic timeline that has shaped personal finance over the past half-century.
Phase 1: The Accumulation Decades (1980s–2010s)
Decades before joining the panel, these individuals began their financial lives like most Americans: dealing with student loans, entering the workforce during economic downturns, buying modest homes, and learning the value of compound interest. Unlike inherited wealth, their assets were accumulated slowly through disciplined budgeting, maximizing retirement accounts like 401(k)s, and building small businesses from the ground up. During this era, financial education was largely self-taught, and money remained a private, rarely discussed topic inside the home.
Phase 2: The Shift Toward Transparency (Late 2010s–Present)
As their net worth crossed the seven-figure threshold and their children transitioned into adulthood, these self-made individuals faced a new paradigm. Recognizing the impending realities of the "Great Wealth Transfer," they realized that keeping financial success a secret from their children could backfire. Rather than fostering fiscal responsibility through ignorance, panelists began shifting toward early financial literacy and intentional transparency.
Phase 3: Modern Legacy Planning (The Present Day)
Today, these millionaires are actively drafting wills, establishing trusts, and—most importantly—having difficult conversations with their adult children. They are navigating the delicate balance between providing generational security and ensuring their heirs retain the drive to build their own successful lives.
Supporting Data: What the Numbers Tell Us
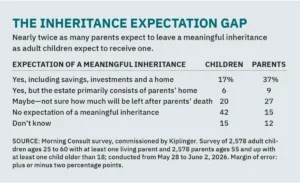
While the Millionaires Panel offers qualitative insight into elite financial planning, broader data reveals a stark contrast between how average families and high-income earners approach money.
According to the Kiplinger "Trillion Dollar Talk" survey, conducted in partnership with Morning Consult:
- The Silence Gap: More than half (50%+) of parents aged 55 and older report that they rarely or never discuss money matters with their children.
- The Income Correlation: The frequency of financial discussions scales directly with household income. Overall, 45% of all adults state they discuss money often or sometimes with their kids. However, for households earning above $100,000 annually, that figure jumps to 56%.
- The Extreme Reticence: Only 11% of high-income earners ($100k+) say they "never" discuss money with their children, compared to 18% of the general population.
These statistics underscore a vital trend: as net worth increases, the necessity for open dialogue regarding inheritance, taxes, and estate planning becomes harder to ignore.
Official Responses and Perspectives from the Millionaires Panel
When surveyed on the practical application of wealth transfer, the panel’s responses highlighted deeply personal philosophies, ethical dilemmas, and diverse strategies.
1. Are Millionaires Talking to Their Kids About Money?
The consensus among the panelists is an overwhelming "yes," though the methods vary. Many emphasized that financial literacy must begin at an early age.
One panelist detailed the creation of a formal "Family Wealth Mission Statement." This document outlines the family’s core values, ethical priorities, and long-term goals, ensuring that the next generation understands the philosophical weight behind the money.
"Communication is vital in preparing the next generation to be good stewards in preserving, growing, and passing on this gift and legacy," the panelist noted.
Another parent highlighted how open communication protects retirement security while keeping adult children informed. By demystifying the family balance sheet, the children understand that their eventual inheritance is a variable equation.
"Since we are open with our children about our finances, and since they understand that their inheritance is, in part, determined by how long we live and how much we need to spend to take care of ourselves during retirement, they have been very supportive," he shared.
2. Should Inheritances Be Split 50/50?
The question of equal versus equitable distribution is one of the most contentious issues in estate planning. Many panelists default to a traditional 50/50 split to preserve family harmony and avoid the perception of favoritism.
"There should be no favorites," one respondent asserted. "Love all that are close to you equally. Don’t create a rift or friction after you pass."
However, strict equality often creates internal dilemmas. One female panelist described her struggle between "even" versus "fair." She has a married daughter with children and an unmarried son with no children. While she currently plans to split her estate evenly down the middle, she frequently wrestles with whether the daughter—who bears the additional financial responsibilities of raising grandchildren—should receive a larger share.
Another panelist shared a poignant generational lesson learned from his own mother. Instead of dividing everything equally, his mother left the bulk of her savings and investments to the child who "needed it most"—an underemployed son living paycheck-to-paycheck—while distributing physical assets differently.
"We discussed who needed financial help vs. who was deserving of help," the panelist wrote. "Once we worked through that conversation, it became very easy."
3. Should Inheritances Be Capped to Avoid Demotivation?
The fear of creating "trust fund babies"—adult children immobilized by the safety net of immense wealth—is a persistent anxiety among self-made millionaires. This philosophy mirrors public statements by prominent figures like Microsoft founder Bill Gates, who has publicly stated he plans to leave less than 1% of his multi-billion-dollar fortune to his children to ensure they forge their own paths.
Panelists expressed similar sentiments, prioritizing work ethic over sheer financial windfall.
"I have a fear that if they find out the potential inheritance, it could demotivate them for grades, life, and job seeking," one panelist admitted. "I prefer to keep them motivated."
Another panelist took a strategic, tax-informed approach, capping her children’s inheritance at a specific threshold while routing the rest to philanthropy.
"Our kids know that they will inherit $4 million each, because that is the state tax exclusion in Illinois," she noted. "Everything else will pretty much go to charity. This means my children, who are 21 and 24, need to make their own living. They are motivated to do so."
Implications: What the Great Wealth Transfer Means for Society
The insights gathered from the Millionaires Panel carry profound implications for the future of American society, family structures, and wealth management.
- The Shift Away from Taboos: The historical reluctance to discuss money is actively breaking down among the affluent. As generational wealth transfer accelerates, families that fail to communicate risk severe post-mortem litigation, fractured sibling relationships, and mismanaged assets.
- Redefining "Fairness": The debate between equal splits and needs-based distribution highlights that modern estate planning is no longer a simple mathematical equation. Parents are increasingly weighing psychological impacts, life stages, and caregiving burdens when drafting their wills.
- The Balance of Motivation and Security: Self-made millionaires possess a unique psychological profile rooted in struggle and hard work. By capping inheritances or tying payouts to financial literacy milestones, affluent parents are attempting to engineer resilience in a generation that stands to inherit unprecedented sums.
As the $124 trillion transfer continues to unfold over the coming decades, the strategies practiced by these 30 millionaires may well serve as a blueprint for families nationwide attempting to navigate the intersection of wealth, love, and legacy.
(Note: The views and opinions expressed in this article are those of the contributing financial advisers and panelists and do not necessarily reflect the official stance of financial regulatory bodies. Investors and families seeking estate planning guidance are encouraged to verify professional credentials via the SEC or FINRA.)