Beyond the Exchange Rate: Why Forcing Renminbi Appreciation Won’t Fix China’s Domestic Slump
By Kai Guo
October 13, 2026
Main Facts
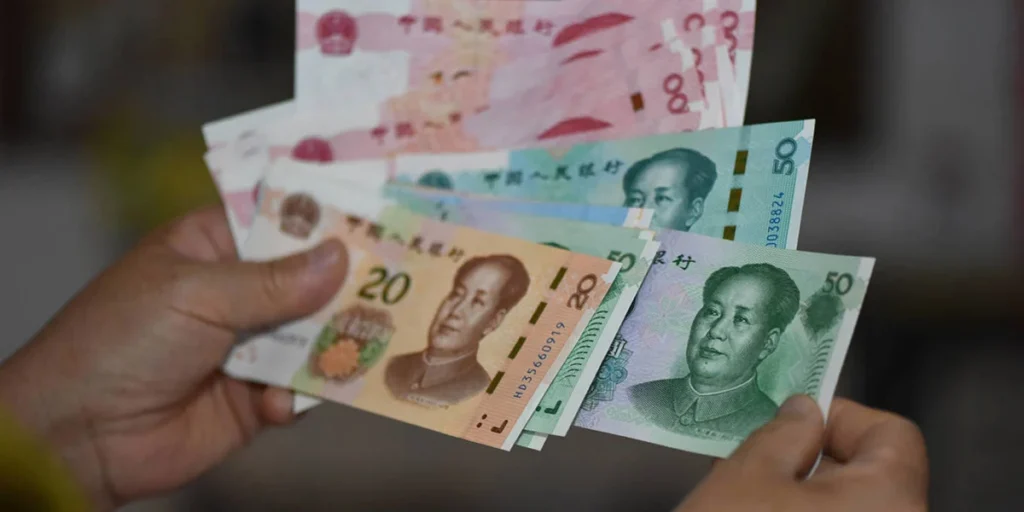
The debate surrounding the valuation of China’s currency, the renminbi (RMB), has once again taken center stage in global economic policy discussions. As international trade tensions mount and global imbalances widen, a near-consensus has emerged among financial commentators, international policymakers, and trade analysts: the renminbi is artificially undervalued.
This viewpoint is largely fueled by staggering macroeconomic indicators. In 2025, China’s merchandise trade surplus reached a historic and unprecedented $1.2 trillion, driven by an industrial and manufacturing engine that continues to dominate global supply chains despite sluggish domestic consumption. Critics argue that this massive trade imbalance is directly propped up by a weak currency that confers an unfair competitive advantage on Chinese exporters, depressing manufacturing sectors across the United States, Europe, and emerging markets.
The prevailing prescription from Western capitals and international financial institutions is straightforward: Beijing must allow the renminbi to appreciate sharply. Proponents of this view argue that a stronger currency would simultaneously make Chinese goods more expensive abroad, curb the surging trade surplus, and ease the competitive pressures facing foreign industrial economies.
However, this conventional diagnosis fundamentally misinterprets the root causes of the renminbi’s current weakness. The softness of the Chinese currency is not the result of aggressive, deliberate manipulation aimed at boosting exports; rather, it is a symptom of deep-seated, persistent weakness in domestic demand. Forcing currency appreciation without first addressing the structural malaise of the domestic economy would be counterproductive—harming not only China’s fragile recovery but also destabilizing the broader global financial architecture.
Chronology of Events
To understand how global markets arrived at the current standoff over the renminbi, it is necessary to trace the evolution of China’s trade dynamics and currency policy over recent years:
- Late 2022 – 2023 (The Post-Pandemic Divergence): As China lifted its strict zero-COVID policies, analysts anticipated a robust consumption-led rebound. Instead, a deepening real estate crisis sapped consumer confidence. While domestic retail sales remained stagnant, industrial production pivoted aggressively toward exports, laying the groundwork for expanding trade surpluses.
- Throughout 2024 (Widening Surpluses and Downward Pressure): Despite mounting anti-dumping investigations and tariff threats from the European Union and the United States, Chinese manufacturers maintained robust export volumes by cutting prices. Capital outflows driven by low domestic yields placed persistent downward pressure on the renminbi against the U.S. dollar.
- January 2025 (The Record-Breaking Milestone): Official customs data revealed that China’s annual merchandise trade surplus for 2024 shattered previous records, crossing the psychological $1 trillion threshold. This milestone triggered intensified scrutiny from the International Monetary Fund (IMF) and G7 finance ministers regarding China’s exchange rate policies.
- Mid-2025 (The $1.2 Trillion Reality): By the close of 2025, annual trade data confirmed that China’s merchandise trade surplus had swelled to an astonishing $1.2 trillion. The sheer magnitude of the surplus cemented the narrative among Western economists that the renminbi was undervalued by as much as 30%.
- Late 2025 – October 2026 (The Policy Impasse): International pressure on the People’s Bank of China (PBOC) to permit a managed float or sharp appreciation reached a fever pitch. Simultaneously, domestic economic indicators showed that deflationary pressures within China remained stubborn, complicating any potential monetary tightening or currency defense strategies.
Supporting Data and Economic Analysis
The argument that the renminbi is undervalued typically relies on traditional purchasing power parity (PPP) models and the sheer size of China’s current account and trade surpluses. Proponents of this view point to several key data points:
- The $1.2 Trillion Trade Surplus: Achieving a merchandise trade surplus of this magnitude in an era of rising global protectionism underscores the unmatched competitiveness of China’s industrial base.
- Manufacturing Dominance: China’s share of global manufacturing output has continued to climb, even as its domestic property sector remains depressed and consumer price index (CPI) growth hovers near zero.
- Real Effective Exchange Rate (REER) Disconnect: Independent analyses, such as those from the Council on Foreign Relations, have suggested that the renminbi’s real effective exchange rate is undervalued by roughly 30% relative to historical fundamentals and current account balances.
The Flaw in the Undervaluation Thesis
While these figures appear damning, they misread the underlying mechanics. A currency is typically weak because capital is fleeing, or because domestic demand is too anemic to absorb national savings. In China’s case, domestic consumption is severely depressed due to high precautionary household savings, inadequate social safety nets, and the wealth effect of the multi-year real estate downturn.
When domestic demand collapses, excess capacity must find an outlet. Chinese factories have redirected unsold domestic inventory toward global markets, competing aggressively on price. The weakness of the renminbi is a reflection of this weak domestic demand and subsequent capital outflow pressure—it is not the primary driver of the trade surplus.
If Beijing were to bow to international pressure and artificially force a sharp appreciation of the renminbi without stimulating domestic consumption, the consequences would be severe. A stronger currency would squeeze already razor-thin manufacturing margins in China, leading to widespread corporate distress and rising unemployment. Crucially, it would do nothing to boost domestic purchasing power. Instead of rebalancing the global economy, it would simply export deflationary pressures while failing to sustainably reduce the trade surplus.
Official Responses
The policy response from Beijing and international institutions highlights a growing ideological and economic divide:
- The People’s Bank of China (PBOC) and Beijing Officials: Chinese authorities have consistently defended their exchange rate policy, describing the renminbi’s rate as market-determined within a managed floating band. Beijing maintains that external demands for currency appreciation ignore structural imbalances within Western economies—such as low savings rates and fiscal deficits—and amount to protectionist efforts to stifle legitimate Chinese industrial competitiveness. Officials have emphasized that true economic rebalancing must come from structural reforms that boost domestic consumption rather than superficial monetary adjustments dictated from abroad.
- The United States and G7 Finance Ministries: Western officials continue to press Beijing to abandon its managed exchange rate practices. The prevailing narrative in Washington and Brussels is that China is "exporting its way out of a domestic crisis" at the expense of foreign workers. Treasury officials have repeatedly warned that prolonged currency misalignment risks provoking a new wave of global trade retaliation, including blanket tariffs and strict capital controls.
- Multilateral Institutions (IMF and World Bank): The IMF has adopted a more nuanced stance. While acknowledging that China’s external position is stronger than warranted by medium-term fundamentals, multilateral economists have increasingly echoed the sentiment that exchange rate adjustments alone are insufficient. They stress that fiscal policy reforms—specifically strengthening the social safety net to reduce household savings rates—are the indispensable prerequisite for any sustainable macroeconomic rebalancing.
Implications for Global Markets
The ongoing fixation on the renminbi’s exchange rate obscures the more complex reality of global economic interdependence. If international policymakers continue to pressure China solely on currency valuation, several negative outcomes are likely to materialize:
- Escalating Trade Wars: Failure to resolve the trade surplus through cooperative domestic reforms in China will likely trigger aggressive retaliatory measures from the U.S. and EU, including higher tariff walls and market fragmentation.
- Stifled Global Growth: Forcing premature appreciation without domestic stimulus could tip China’s manufacturing sector into a deeper deflationary spiral, dampening demand for global commodities and slowing worldwide economic growth.
- Misdirected Policy Focus: By framing the issue entirely as a currency manipulation problem, policymakers risk ignoring the real reforms required—namely, structural fiscal policies inside China that shift the economic model away from state-driven investment toward consumer-led demand.
Ultimately, the renminbi is a mirror, not an engine. Until policymakers address the fundamental weakness of China’s domestic demand, attempts to manipulate or force currency appreciation will prove futile, offering a superficial fix to a deeply structural global challenge.