Beyond the Balance Sheet: Why the $124 Trillion ‘Great Wealth Transfer’ Is a Human Crisis, Not Just a Legal One
As the United States stands on the precipice of what financial historians are calling the "Great Wealth Transfer"—an estimated $124 trillion projected to cascade from older generations to their heirs over the next two decades—wealth management professionals are sounding an urgent alarm.
While affluent families spend countless hours and exorbitant fees perfecting the technical scaffolding of their estates—funding complex trusts, mapping generation-skipping tax exemptions, and optimizing basis step-ups—advisers note that legal perfection is rarely what keeps an inheritance intact.
Instead, the true catalyst for family fracture is silence. When the ink dries on a multi-million-dollar estate plan, what remains behind is often a web of cold mechanisms without a drop of context. Without understanding the why behind a parent’s financial decisions, beneficiaries routinely fill the narrative vacuum with assumptions of favoritism, giving rise to costly litigation, fractured relationships, and the rapid erosion of generational wealth.
Main Facts: The Anatomy of the Great Wealth Transfer
The core dilemma of the Great Wealth Transfer is a paradox of preparation. Families with $10 million or more in multigenerational assets almost universally complete the necessary technical work. Trusts are established, powers of attorney are designated, and tax exposures are modeled.
Yet, these mechanical safeguards fail to address the emotional and interpersonal dynamics of inheriting vast sums of money. A trust can dictate precisely what an heir must do with their inheritance, but it cannot explain why those specific choices were made.
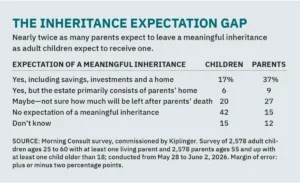
Furthermore, data reveals a profound conversational chasm within American households. According to a Morning Consult survey conducted for Kiplinger’s Trillion Dollar Talk report, more than half of parents aged 55 and older admit they rarely or never discuss money with their children. This pervasive silence transforms estate planning from an act of stewardship into a ticking time bomb of unaddressed expectations.
Chronology: From Legal Oversight to Family Fragmentation
To understand how estate plans fail, financial planners often point to a timeline that begins long before a death certificate is signed and extends years into probate court.
- Decades of Accumulation: Throughout a professional career, individuals build substantial assets through businesses, real estate, and investment portfolios, rarely establishing a structured framework for communicating financial values to the next generation.
- The Critical Omission (The Estate Planning Phase): Families hire attorneys and CPAs to minimize tax liabilities and set up airtight legal structures. However, they stop short of documenting their personal philosophy or convening family meetings to discuss intent.
- The Catalyst Event: A primary wealth holder passes away or experiences cognitive decline. Sudden grief intersects with heavy financial responsibility.
- The Vacuum of Meaning: Heirs receive disparate inheritances—one child may receive liquid assets, while another inherits an operating business or a complex real estate portfolio. Because the rationale was never articulated, beneficiaries assume bias or malice.
- The Downstream Fallout: Silence gives way to suspicion, which rapidly escalates into formal litigation, contested wills, frozen assets, and permanent family estrangement—a phenomenon industry veterans grimly refer to as "probate as a reality show."
Supporting Data: The Scale and the Silence
The numbers underpinning the Great Wealth Transfer highlight both the magnitude of the capital in motion and the staggering lack of communication surrounding it:
- $124 Trillion: The estimated amount of wealth projected to move from older generations to heirs over the next 20 years in the United States, representing the largest intergenerational wealth migration in history.
- 55+ Demographics: More than half of parents in this age bracket report that they "rarely or never" discuss inheritance plans, account values, or financial philosophies with their adult children.
- First-Generation Failure Rates: Industry data consistently shows that a significant percentage of family wealth fails to survive even the transition to the second generation, largely due to a lack of shared vision, financial literacy, and interpersonal communication rather than poor investment returns.
- The Cost of Gaps: Legal fees, court costs, and prolonged probate battles drain millions of dollars from estates annually—losses that could be entirely mitigated by proactive family alignment.
Official Perspectives and Expert Warnings
Estate planning attorneys, wealth managers, and fiduciary experts are increasingly shifting their advisory models away from purely technical tax mitigation toward family governance and communication coaching.
Industry experts emphasize that a high-net-worth portfolio does not insulate a family from human error or legal vulnerability. For instance, many successful professionals—driven by a sense of invulnerability derived from their business achievements—neglect foundational safety nets like durable powers of attorney or advanced healthcare directives. This oversight can force families into bitter, public guardianship proceedings if cognitive decline sets in before an estate plan is activated.
"Sophistication in your portfolio doesn’t protect you from a gap in your authority documents," notes veteran financial advisory commentary. "I’ve watched it happen to plenty of clients who assumed their success made them exempt from ordinary human vulnerabilities."
Advisers universally argue that estate planning must evolve from a discrete legal transaction into an ongoing, transparent dialogue.
Implications: Three Moves Beyond the Legal Documents
To ensure that the Great Wealth Transfer strengthens rather than dismantles a family, financial planners recommend three essential practices that go far beyond standard legal drafting:
1. Document the Intent with a "Letter of Wishes"
While the core trust documents dictate legal distributions, a separate letter of wishes provides the human element. Though not legally binding, this document sits alongside the trust instrument to explain the reasoning behind specific decisions—such as why certain assets were allocated to particular heirs. It gives future generations the context they need to understand the parent’s state of mind and core motivations.
2. Convene Structured Family Meetings Early
Waiting for a crisis to force a conversation about wealth is a recipe for disaster. Families should hold periodic, facilitated discussions regarding overarching financial priorities and philanthropic goals. Crucially, these meetings do not need to disclose exact account balances to be effective; the primary objective is to align family values and manage expectations long before assets change hands.
3. Treat the Estate Plan as a Living Instrument
An estate plan drafted a decade ago is rarely aligned with today’s family dynamics, tax laws, or business interests. Wealth holders must treat their plans as dynamic frameworks, reviewing them on a regular cadence to ensure they reflect current realities rather than outdated assumptions.
Conclusion: Reframing the Estate Plan as a Memoir
Ultimately, the Great Wealth Transfer is not fundamentally a legal event unfolding behind closed doors in an attorney’s office; it is a deeply human event moving through legal channels.
When wealth holders begin to view their estate plans less as cold mechanisms triggered by mortality and more as a memoir—a written reflection of the values, lessons, and judgment they wish to project into the future—the entire dynamic shifts.
Families who survive the Great Wealth Transfer intact are those who recognize that a financial plan built without an origin story rarely survives contact with real money, real grief, and real responsibility. By prioritizing communication, transparency, and shared intent today, families can ensure their legacy endures across generations.