Retiring in the Golden State: A Comprehensive Guide to Navigating the Financial Realities of California
For many Americans, California is the ultimate retirement destination. Boasting a Mediterranean climate, endless outdoor recreation, world-class culinary scenes, and a vibrant cultural mosaic, the Golden State offers a lifestyle that is hard to replicate elsewhere. However, behind the palm trees and ocean breezes lies a complex and often unforgiving financial landscape. With an overall cost of living running roughly 40% to 45% above the national average, retiring in California demands a level of financial foresight and strategic planning that goes far beyond simply packing up and heading west.
Navigating the intricacies of California’s tax code, skyrocketing real estate, comprehensive healthcare costs, and daily living expenses requires a disciplined approach. Whether you are contemplating a do-it-yourself retirement strategy or working alongside a certified financial planner, understanding the intersection of state-specific policies and personal finance is essential to ensuring your nest egg lasts as long as your retirement.
Main Facts: The Economic Realities of the Golden State
The decision to spend your golden years in California involves weighing unparalleled lifestyle benefits against significant economic hurdles. While the state is undeniably attractive, its structural financial markers require careful calibration of any retirement portfolio.
- Cost of Living: California’s cost of living outpaces the national average by 40% to 45%, driven largely by housing, transportation, energy, and taxation.
- State Income Taxes: California levies some of the highest state income taxes in the United States, with marginal rates starting at 1% and climbing to 12.3%, plus an additional 1% surcharge on taxable income exceeding $1 million.
- Capital Gains Treatment: Unlike the federal government, which offers preferential tax rates on long-term capital gains, California taxes these investment profits at the exact same ordinary income rates as traditional retirement account withdrawals.
- Social Security Exemptions: On a positive note, California does not tax Social Security benefits, nor does it tax disability or survivor benefits, providing a minor cushion for retirees relying heavily on these streams.
- Property Tax Protections: Thanks to historic legislation like Proposition 13 and Proposition 19, long-term homeowners enjoy caps on property tax increases and certain tax-transfer benefits for seniors moving to new homes.
Chronology: The Evolution of California Retirement Planning
Understanding how to retire in California effectively is best viewed as a chronological process—a series of distinct phases that begin years before you actually leave the workforce and continue well into your retirement.
Phase 1: Pre-Retirement Assessment (5 to 10 Years Out)
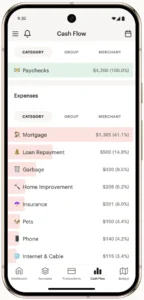
During the final decade of your working years, the focus must shift from wealth accumulation to cash-flow mapping. Many future retirees look at their bank and investment balances and assume they are ready, but few have a precise accounting of their actual monthly and annual expenditures.
Wealth advisers frequently note that clients drastically underestimate what they spend. This phase requires categorizing expenses into fixed, nondiscretionary needs (housing, utilities, healthcare premiums, and insurance) and discretionary wants (travel, dining, and hobbies). Knowing the exact baseline required to survive versus what can be trimmed during a down stock market year is the bedrock of a secure California retirement.
Phase 2: The Transition and Healthcare Integration (Ages 63–65)
As you approach Medicare eligibility, the timeline accelerates. Planning for healthcare in California goes far beyond finding a primary care physician near world-class institutions like Cedars-Sinai, Stanford Health Care, UC San Diego Health, or UCLA Ronald Reagan Medical Center.
During these years, retirees must integrate Medicare Parts A, B, and D, evaluate Medigap or Medicare Advantage policies, and factor in dental, vision, and potential long-term care insurance. Crucially, this is the window where managing your taxable income is paramount, as large pre-tax retirement account withdrawals can trigger Income-Related Monthly Adjustment Amounts (IRMAA), substantially raising your monthly Medicare premiums.
Phase 3: Active Retirement and Asset Management (Post-Age 65)
Once retirement officially begins, the chronology becomes cyclical. Annual tax planning, portfolio rebalancing, and monitoring capital gains become routine. Because California treats capital gains as ordinary income, the timing of asset sales must be meticulously synchronized with your overall tax bracket to avoid unnecessary liabilities.
Supporting Data: Breaking Down the Numbers
To visualize the financial impact of retiring in California, one must examine the specific data points governing taxes, healthcare, and housing.
The Tax Burden Breakdown
California’s tax structure is progressive and aggressive. For retirees drawing from traditional pre-tax vehicles—such as traditional IRAs, 401(k) plans, or pensions—every dollar withdrawn is exposed to state income taxes that can reach up to 12.3%.
Compare this to long-term capital gains: at the federal level, capital gains are taxed at 0%, 15%, or 20% depending on income. In California, however, those same gains are lumped in with ordinary income. For high-net-worth retirees liquidating portfolios to fund lifestyle expenses, this distinction can dramatically erode net returns.
Healthcare and IRMAA Surcharges
Healthcare inflation outpaces general inflation nationwide, but regional costs in major California metro areas like San Francisco, Los Angeles, and San Diego can be exceptionally steep. Furthermore, the IRMAA brackets catch many retirees off guard. If a retiree pulls a large lump sum from an IRA to buy a car or remodel a kitchen, that spike in modified adjusted gross income (MAGI) can retroactively hike their Medicare Part B and Part D premiums for the following year.
Housing Equity vs. Liquidity
Housing represents the largest single component of net worth for most older Americans. In California, decades of real estate appreciation mean many retirees are "asset rich and cash flow constrained." A home bought for $40,000 in the 1980s may now be worth $1.5 million. While this looks fantastic on a balance sheet, it complicates decisions regarding downsizing. Selling a home triggers a new property tax assessment unless specific state exemptions apply, meaning a smaller, less expensive home on paper might not actually reduce monthly overhead.
Official Responses and Legislative Protections
Recognizing the immense pressure high costs and taxes place on older residents, California has enacted specific constitutional amendments and legislative frameworks to protect long-term homeowners and seniors.
Proposition 13: Halting Runaway Property Taxes
Passed by voters in 1978, Proposition 13 remains a cornerstone of financial predictability for California property owners. It limits the base year value of real property to its purchase price and caps annual property tax increases at a maximum of 2%, regardless of how much the local real estate market appreciates. This protection ensures that seniors living on fixed incomes are not priced out of their homes by sudden spikes in municipal property valuations.
Proposition 19: Facilitating Senior Mobility
For retirees who do wish to downsize, relocate closer to family, or move to a single-story home, Proposition 19 offers a vital mechanism. Eligible homeowners who are 55 or older, severely disabled, or victims of a natural disaster can transfer the tax-assessed value of their original primary residence to a new replacement home anywhere in the state—regardless of the new home’s higher market value. Qualified adults can utilize this tax-transfer benefit up to three times in their lifetime, mitigating the tax penalty traditionally associated with moving.
Implications: Making Your California Retirement Sustainable
The overarching implication for anyone eyeing a retirement in the Golden State is that hope is not a strategy. Because the margins for error are smaller due to high taxes and cost of living, financial decisions cannot be made in isolation.
The Ripple Effect of Financial Decisions
Every financial move in California creates a ripple effect. Cashing out a stock portfolio to fund a major purchase impacts your capital gains tax liability, which in turn raises your adjusted gross income, which can subsequently trigger an IRMAA surcharge on your Medicare premiums. Recognizing how these variables interconnect is essential.
Flexibility and Lifestyle Balance
Ultimately, retiring in California is entirely feasible—and deeply rewarding—for those who plan accordingly. Maintaining a clear understanding of nondiscretionary versus discretionary expenses allows retirees to pivot swiftly when economic headwinds, such as a volatile stock market, emerge. By combining rigorous budgeting, strategic tax management, and a realistic appraisal of state-specific costs, retirees can successfully balance the high financial price of living in the Golden State with the irreplaceable richness of its lifestyle.
Note: This article presents general financial considerations and perspectives on retirement planning. Readers should consult with qualified, independent certified financial planners, tax professionals, or estate attorneys before making major financial decisions. You can verify the credentials of financial advisers through the Securities and Exchange Commission (SEC) via AdviserHub or the Financial Industry Regulatory Authority (FINRA) via BrokerCheck.