The Great Squeeze: Deconstructing the American Affordability Crisis
The American economy is currently navigating a complex paradox. On one hand, headline economic indicators suggest a resilient labor market and wage growth that—at least on paper—has kept pace with inflation. On the other, the lived experience of the average household tells a drastically different story. From the rising cost of a gallon of gasoline to the astronomical climb in mortgage payments, Americans are feeling a profound sense of economic instability.
In a recent episode of the On the Market podcast, host and BiggerPockets Chief Investment Officer Dave Meyer deconstructed this "affordability crisis." The central question is whether the current economic malaise is a symptom of a systemic failure, a temporary spike in costs, or a fundamental shift in how Americans consume and prioritize their household budgets.
Main Facts: The Disconnect Between Data and Reality
At the core of the current discourse is the divergence between macroeconomic statistics and personal finance reality. While the Consumer Price Index (CPI) tracks the cost of a "basket of goods," it is a blunt instrument that often fails to capture the nuance of specific household burdens.
The primary fact driving public anxiety is that while nominal wages have risen by approximately 37% since 2019, the cost of essential services—housing, childcare, and higher education—has outpaced income growth by a wide margin. For instance, mortgage payments have surged by 116% in that same period. This creates a "weighted" crisis: if a household’s primary expenses are in categories that have seen hyper-inflation, a 37% wage increase feels like a pay cut.
Furthermore, the national savings rate has plummeted from a long-term average of 7-12% to roughly 3%. This depletion of financial cushions suggests that even if households are technically keeping up with inflation, they are doing so by exhausting their reserves, leaving them increasingly vulnerable to economic shocks.
A Chronological Look: Where Did We Go Wrong?
To understand the current crisis, one must look at the progression of the American budget over the last three decades. By comparing 1999, 2009, and 2019 to the present day, a pattern of shifting financial stress emerges.
- 1999-2009: During this decade, real wage growth was modest, but costs for basic consumer goods remained relatively stable. Household budgets were primarily focused on traditional debt management and savings.
- 2019 (The Pre-Pandemic Baseline): This year serves as the critical turning point. While the economy was robust, the foundation for the current housing and childcare crises was already being laid. Income growth was steady, but it was failing to account for the rising cost of entry into the housing market.
- 2021–2023 (The Inflationary Wave): The post-pandemic era brought an unprecedented spike in inflation, peaking at nearly 9%. During this window, real wages turned negative for the first time in years. This period permanently shifted the "price level" for basic necessities.
- 2026 (The Current State): We are currently seeing a return to negative real wage growth. Despite previous gains, the cumulative effect of price hikes over the last five years has resulted in a permanent shift in the cost of living that wages have not fully reconciled.
Supporting Data: The Winners and Losers of the Budget
A detailed analysis of household categories reveals that the "affordability crisis" is not uniform.
Where Inflation Hits Hardest
- Housing: As noted, the 116% increase in mortgage payments since 2019 makes housing the single most significant driver of the current crisis.
- Childcare and Education: These costs have risen by 200% since 1999. For families in their prime working years, this represents an enormous drag on disposable income.
- Energy: Energy costs have risen by 205% since 1999, significantly outpacing the 130% growth in wages.
The Surprising Stability
- Groceries: Contrary to public sentiment, the data suggests that food prices have tracked relatively closely with wage growth since 1999 (113% vs 130%). While the psychological impact of seeing a higher bill at the register is real, the statistical reality is that groceries remain more affordable than they were 27 years ago.
- Consumer Goods: Electronics and general household items have seen price stability or even deflation in some sectors, yet these categories make up a smaller percentage of the "essential" budget than housing or childcare.
The "Hidden" Drivers: Subscriptionization and Overconsumption
A significant portion of the affordability crisis is not found in the CPI, but in structural changes to the economy—specifically, the "subscriptionization" of daily life.
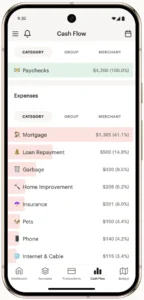
In previous decades, purchasing a tool, a car, or a household appliance was a one-time expense. Today, software, entertainment, and even automotive features are tied to monthly subscriptions. This creates a perpetual drain on household cash flow. Because these are "sunk costs" that never disappear, they prevent households from building the equity that once protected families from economic volatility.
Furthermore, there is the issue of "social inflation." The standard of living deemed "normal" today requires more items than in 1999. Whether it is the necessity of high-speed data plans, constant hardware upgrades, or the proliferation of specialized childcare gear, the volume of goods required to participate in modern society has increased. Even if the price of an individual item has remained stable, the total count of items a household must pay for has ballooned, stretching budgets to the breaking point.
Implications for Investors and the Economy
The ripple effects of this crisis extend deep into the investment landscape, particularly for real estate.
For Rental Property Investors
Investors must pivot their expectations. With savings rates at historic lows, the margin for error for tenants is razor-thin. Landlords should prepare for:
- Moderated Rent Growth: Expecting double-digit rent increases is no longer realistic or sustainable in the current environment.
- Increased Reserves: Investors should prioritize higher cash reserves to weather potential periods of non-payment or increased vacancy rates.
- Operational Efficiency: With energy and maintenance costs rising due to labor and material inflation, property managers must aggressively manage utility and upkeep expenses.
The Opportunity in "Affordability"
There is a silver lining for those who adapt. The demand for "affordable" housing configurations—such as accessory dwelling units (ADUs), house-hacking, and rent-by-the-room models—is set to skyrocket. As younger generations are priced out of traditional single-family home ownership, they will gravitate toward creative, cost-effective living arrangements. Investors who pivot to provide these solutions are likely to see high occupancy and long-term stability.
Conclusion: A Nuanced Crisis
Is the American affordability crisis real? The answer depends entirely on the demographic. For a young family navigating the "trifecta" of rising housing, childcare, and energy costs, the crisis is absolute. For others, the issue may be more rooted in the psychological fatigue of a high-price-level environment and the constant, cumulative drain of the subscription economy.
While headline data shows wages trending upward, the "real" economy is defined by the erosion of the financial cushion that households rely on for security. As we look toward the future, the stability of the American economy will depend on whether wages can eventually outpace these sticky, elevated price levels, or if the country must undergo a fundamental reassessment of what it means to live a "comfortable" life in the 21st century.
For investors, the mandate is clear: abandon the assumptions of the last decade. In an era where the cost of living is being squeezed from every side, success will belong to those who can provide value, efficiency, and flexibility to a consumer base that is increasingly forced to choose between the essential and the desirable.