The Tax Trap: How Modern Wealth Management Solutions Create New Psychological and Financial Dilemmas
September 13, 2026
By Ben Carlson (Adapted and Expanded for Financial Journal)
Main Facts
Taxes occupy a peculiar psychological space in human finance. Virtually everyone dislikes paying them, actively structures their affairs to minimize them, and frequently derives more emotional satisfaction from saving a dollar on taxes than from earning an extra dollar through hard work. Yet, in the realm of investing, paying capital gains taxes is fundamentally a byproduct of success. It indicates that an asset purchased in the past has appreciated in value, yielding a profit and signaling to the government that it is time to collect its share.
Because of loss aversion—the psychological phenomenon where the pain of losing something vastly outweighs the pleasure of gaining its equivalent—paying taxes feels acutely like a theft of personal property. In recent years, explosive bull markets have intensified this dynamic. Wealth management clients sitting on massive paper gains, particularly those concentrated in high-flying technology equities or low-cost-basis employee stock options, face a daunting dilemma. While traditional financial wisdom dictates that "you concentrate to get rich and diversify to stay rich," the tax bill triggered by unwinding a concentrated position can be astronomical.
To combat this, the financial technology sector has evolved. Traditional direct indexing allows investors to harvest tax losses at the individual security level to offset gains. However, for portfolios with outsized, rapid gains, standard direct indexing often lacks the horsepower to generate sufficient losses quickly enough.
This limitation has popularized long/short direct indexing. By utilizing margin and short positions, this advanced strategy supercharges tax-loss harvesting, accelerating the generation of artificial losses to offset massive capital gains. Yet, as financial planners are discovering, these sophisticated tools come with unforeseen trade-offs. Beyond the complex quantitative mechanics lie deep psychological traps, creating a scenario where investors successfully defer taxes only to become permanently trapped in their own portfolios, unable or unwilling to ever unlock their wealth for actual consumption.
Chronology of Modern Wealth Management and Tax Strategy
To understand how investors arrived at today’s complex tax-deferral landscape, it is helpful to trace the evolution of wealth management tools over the past several decades:
- The Era of Mutual Funds and Broad Indexes (Late 20th Century): For decades, retail and high-net-worth investors relied heavily on mutual funds and, later, passive exchange-traded funds (ETFs). While tax-efficient compared to actively managed mutual funds, standard ETFs offered zero customization. If an investor held a highly appreciated, concentrated block of tech stock, selling it meant absorbing the entire tax liability immediately.
- The Rise of Direct Indexing (Early 2020s): As trading commissions dropped to zero and fractional shares became standard, financial technology platforms democratized direct indexing. Instead of buying an S&P 500 ETF, investors could buy the individual 500 stocks in their exact weightings. This enabled automated, continuous tax-loss harvesting (TLH) at the individual security level, allowing portfolios to shave down tax liabilities year after year.
- The Bull Market Concentration Crisis (Mid-2020s): Fueled by structural shifts in artificial intelligence, cloud computing, and mega-cap tech performance, portfolios accumulated unprecedented unrealized gains. Traditional direct indexing proved too slow for investors needing to de-risk immediately, as the natural drift of a bull market meant fewer downward-sloping securities were available to harvest.
- The Emergence of Long/Short Direct Indexing (2026): Financial advisors began adopting long/short direct indexing strategies to artificially inject volatility and loss-generation into portfolios. By introducing margin and short positions, these platforms could aggressively manufacture losses, neutralizing massive capital gains overnight and allowing clients to diversify out of concentrated risk without writing a seven-figure check to the IRS.
- The Psychological Reckoning (Present Day): As financial scientists and wealth managers analyze the long-term impacts of aggressive tax-deferral engineering, a new debate has emerged regarding behavioral finance. Experts note that aggressive tax optimization frequently locks investors into perpetual holding patterns, transforming the original goal of wealth creation into a barrier against enjoying the fruits of one’s labor.
Supporting Data and Financial Mechanics
The numbers underpinning modern tax-aware strategies reveal a fascinating tension between quantitative optimization and qualitative human behavior.
The Math of Concentration vs. Diversification
Consider an executive or early employee who holds $5 million in single-stock tech options with a cost basis of near zero. Selling the entire position in a top federal and state tax bracket could easily trigger a tax liability exceeding $1.5 million.
- Standard Liquidation: Pay $1.5M immediately, leaving $3.5M to reinvest in a diversified, lower-risk portfolio.
- Long/Short Direct Indexing Approach: By utilizing a levered long/short overlay, the portfolio manager can aggressively harvest synthetic losses in the early years of the strategy. This offsets the realized gains of selling portions of the concentrated stock, allowing the investor to transition out of the single stock over a multi-year period with a dramatically reduced tax burden.
The Declining Loss Curve
However, the mathematical architecture of long/short direct indexing contains a structural paradox. Nick Maggiulli, in his seminal behavioral finance research, highlights the trap inherent in these systems:
"As it generates more gains, it lowers your likelihood of ever selling these positions. Why? Because, in my experience, people hate paying taxes more than they like making money. As a result, you can end up stuck in the strategy.
This is by design. A levered long/short strategy generates lots of losses in the early years, but as markets (typically) drift upward over time, there are fewer and fewer losses to harvest. As a result, you end up with an increasing amount of unrealized gains."
Over a 10-to-20-year horizon, as the broader equity markets drift upward, the strategy exhausts its ability to manufacture losses. The investor is left with a portfolio that has continuously compounded, pushing unrealized gains higher and higher. Paradoxically, the very mechanism designed to free the investor from concentration risk ends up trapping them in a new, hyper-optimized cage of unrealized gains that they are perpetually too terrified of taxes to liquidate.
Official Responses and Expert Perspectives
As the wealth management industry races to adopt long/short direct indexing, leading financial thinkers and practitioners are offering nuanced warnings about the limits of tax optimization.
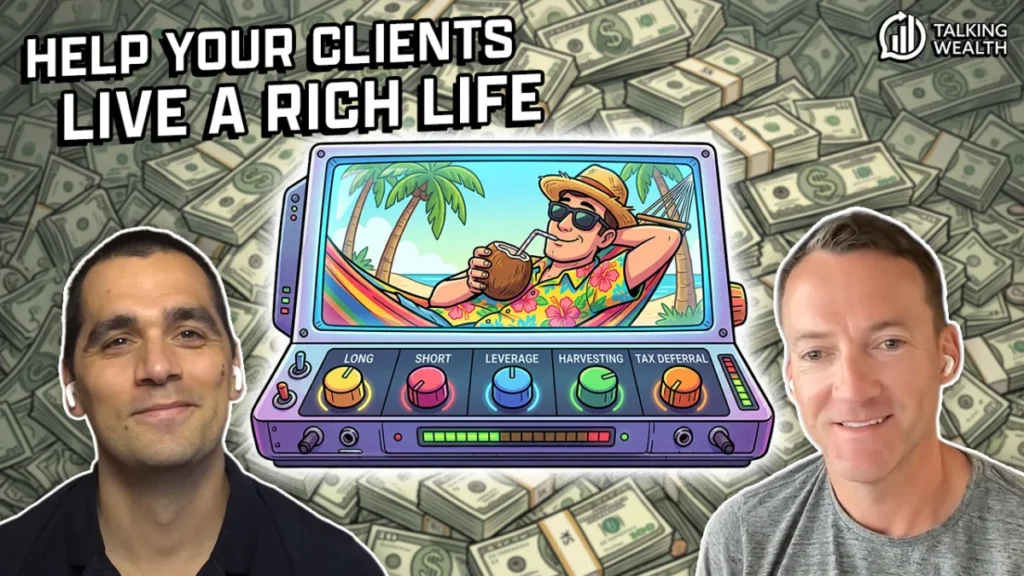
In a recent episode of the financial commentary program Talking Wealth, wealth managers Ben Carlson and Nick Maggiulli sat down to deconstruct the emotional and structural realities of tax-aware investing. The discussion centered on a fundamental question: At what point does minimizing taxes begin to actively harm a financial plan?
The Trade-Off Between Wealth Accumulation and Utility
"We’ve seen firsthand how difficult it can be for certain individuals to enjoy their hard-earned money," Carlson noted during the broadcast. "Creating a large tax deferral in such a short period of time can create an insurmountable psychological barrier to actually spending your money."
While financial planners are heavily incented to solve quantitative problems—such as basis-point drag, fee minimization, and tax alpha—they frequently underappreciate qualitative metrics, such as life satisfaction and capital utilization.
Industry experts emphasize several key takeaways regarding modern tax strategies:
- Not Every Solution is Universal: Advanced long/short strategies are powerful tools, but they add operational complexity, margin costs, and administrative fees. They are built for high-net-worth clients with massive single-stock concentrations, not the average retail investor.
- The Danger of the "First World Problem" Trap: Wealthy clients often fall into the trap of optimization perfectionism, treating their portfolios like a video game where the highest score wins, forgetting that money’s ultimate utility is to fund life experiences, security, and philanthropy.
- Situational Strategy Trumps Dogma: There is no single "best" portfolio construction. For some investors, taking the tax hit upfront, cleaning the slate, and moving on to a simplified life of diversified index funds provides more peace of mind than engineering a complex, levered tax shelter that they can never untangle.
Implications: The Psychological Toll of Financial Perfection
The widespread adoption of long/short direct indexing and aggressive tax-alpha strategies points to a deeper philosophical shift in modern wealth management. We have entered an era where engineering tax efficiency has become an art form. Yet, this technical brilliance carries profound downstream implications.
1. The "Living Rich to Die Rich" Phenomenon
When tax avoidance is optimized to its absolute mathematical limit, it often alters human behavior in unintended ways. If an investor builds a mental model where paying taxes represents a catastrophic failure, they will naturally resist any transaction that triggers a taxable event. Over decades, this creates an unspent fortress of wealth. The individual lives a modest lifestyle relative to their net worth, terrified of triggering the capital gains tax monster they spent years constructing complex financial engineering to avoid.
2. The Illusion of Control
Financial technologies give advisors and clients incredible levers to pull. Margin, shorting, algorithmic tax-loss harvesting, and direct security customization make investors feel as though they can bend the market to their will. However, these tools substitute one set of risks for another. Instead of facing concentration risk or market risk, the investor now faces complexity risk, operational risk, and behavioral paralysis.
3. Redefining Success in Financial Planning
Ultimately, the proliferation of these tools forces a re-evaluation of what a successful financial plan actually looks like. Is success measured strictly by the net worth figure displayed on a digital dashboard at the end of a lifetime? Or is it measured by the freedom, utility, and peace of mind the capital provided along the way?
As Carlson and Maggiulli concluded in their analysis, every investment strategy involves trade-offs and unintended consequences. Intelligent solutions frequently solve yesterday’s problems while silently breeding tomorrow’s dilemmas. For wealth managers and investors alike, the challenge of the future will not be finding new ways to avoid taxes, but knowing when to stop optimizing, accept the tax bill, and actually enjoy the wealth that was so painstakingly built.