The Silent Crisis: Why Record Numbers of Americans Are Tapping Into Their Retirement Future
In the modern American economy, the 401(k) has long been heralded as the bedrock of middle-class retirement security. However, recent data from Vanguard—one of the world’s largest investment management firms—reveals a troubling shift. Last year, 6% of workers enrolled in Vanguard-managed plans opted for "hardship withdrawals," an early extraction of retirement capital to cover immediate financial crises. This figure marks the sixth consecutive year of growth, signaling that an increasing number of households are being forced to compromise their future stability to survive their present circumstances.
The Chronology of a Growing Financial Strain
To understand the current surge, one must look at the trajectory of the last half-decade. Prior to the global pandemic, hardship withdrawals were relatively uncommon, often viewed as a last-resort option for those in dire straits. However, the economic volatility triggered by 2020 served as a catalyst for a sustained upward trend.
Year over year, the percentage of plan participants dipping into their retirement accounts has crept higher, rising from 5% to 6% in the most recent reporting period. While a one-percentage-point increase might appear marginal in isolation, it represents hundreds of thousands of workers across the United States. Furthermore, the median withdrawal amount has surged to approximately $1,900—a figure that is roughly triple what was recorded during the pre-pandemic era. This escalation suggests that the "buffer" households have between their income and their essential expenses has eroded, leaving them with fewer options when a sudden bill arrives.
The Anatomy of an Emergency: Why Workers Are Pulling Early
The prevailing narrative surrounding 401(k) withdrawals often suggests a lack of financial discipline. However, data from the How America Saves 2026 report suggests the exact opposite: the vast majority of these withdrawals are driven by non-discretionary, unavoidable life events.
The Primary Drivers
- Housing Stability (36%): The most frequent cause for hardship withdrawals is the immediate threat of eviction or foreclosure. As rent and mortgage costs have soared, many households have reached a breaking point where their retirement savings are the only remaining liquidity.
- Medical Emergencies (31%): Unexpected health issues and the resulting out-of-pocket expenses continue to be a primary driver of financial distress.
- Education and Infrastructure (24%): Tuition payments (13%) and critical home repairs (11%) account for nearly a quarter of all withdrawals. These are expenditures that, if ignored, would lead to long-term consequences such as loss of housing utility or interrupted professional development.
It is critical to note that these withdrawals are rarely impulsive. Unlike a credit card purchase for a luxury item, these withdrawals are reactive, desperate measures taken by individuals facing existential financial threats.
The Hidden Cost: Calculating the True Price of Liquidity
While a hardship withdrawal provides immediate cash, it comes with a severe, often underestimated, financial penalty. It is a common misconception that these funds can be replaced or "borrowed" in a way that preserves retirement projections. In reality, a hardship withdrawal is a permanent depletion of capital.
The Immediate Tax and Penalty Hit
The moment a worker withdraws money from a 401(k) before the age of 59 ½, the IRS treats the transaction as taxable income. Furthermore, unless a specific exemption applies, the participant is subject to a 10% early withdrawal penalty. For an individual withdrawing the median amount of $1,900, the combined impact of federal income tax and the 10% penalty can easily exceed $400. Effectively, the worker loses nearly a quarter of the money they requested to taxes and fees before even paying the bill they were attempting to cover.
The Opportunity Cost: The Silent Thief of Growth
The most damaging consequence, however, is not the tax bill—it is the loss of compounding interest. Retirement accounts are designed to grow exponentially over decades. By removing $1,900 from an account at age 25, a worker is not just losing $1,900; they are losing the potential for that money to double or triple multiple times over the next 40 years. That single withdrawal could result in a shortfall of tens of thousands of dollars by the time the worker reaches retirement age, significantly diminishing their lifestyle in their golden years.
Demographic Vulnerabilities: Who Is at Highest Risk?
The How America Saves 2026 report highlights a stark divide based on income levels. Workers earning under $100,000 annually are 3.5 times more likely to initiate a hardship withdrawal than their higher-earning counterparts.
This is a structural reality rather than a behavioral one. Lower-income households frequently lack the "margin" in their monthly budgets to build a traditional liquid emergency fund. When a $1,900 car repair occurs, a high-earner may be able to absorb the cost through monthly cash flow or existing savings. For a worker earning $45,000 a year, the same bill represents a catastrophic event that threatens their basic housing or nutritional security. Consequently, the 401(k) becomes the only "savings account" they have access to, regardless of the prohibitive costs associated with withdrawing it.
Strategic Alternatives: What to Try Before Tapping the 401(k)
Financial experts emphasize that, while a hardship withdrawal is a tool, it should be the absolute last resort. Before permanently damaging a retirement future, individuals should explore several alternatives:
- The 401(k) Loan: Many employer-sponsored plans allow for a 401(k) loan. Unlike a hardship withdrawal, a loan is paid back over time through payroll deductions, and the interest paid on the loan goes back into the participant’s own account. It avoids the tax and penalty hit, provided the loan is repaid according to the plan’s terms.
- Emergency Fund Prioritization: Even if it begins with a small monthly contribution, building a liquid cash cushion is the most effective way to prevent future withdrawals. Financial planners suggest aiming for three to six months of living expenses.
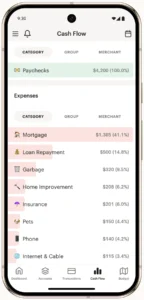
- Budgetary Audits: Using modern budgeting tools to identify "leaks" in monthly spending can help redirect even $50 to $100 a month into a high-yield savings account. As the data shows, consistent, modest savings can accumulate into a significant buffer over time, potentially covering the exact medical or repair bills that currently force people to tap their retirement funds.
Implications for the Future of Retirement
The record-breaking frequency of these withdrawals suggests a systemic issue. If 6% of the workforce is consistently forced to cannibalize their retirement savings, the long-term implication is a potential increase in poverty rates among future retirees.
Policymakers and employers are beginning to look at solutions, such as "sidecar" savings accounts—short-term, accessible savings buckets linked to 401(k) plans—that allow employees to save for emergencies without the tax hurdles of retirement accounts. Until such systemic changes are widely adopted, however, the burden remains on the individual to guard their retirement accounts as if their future quality of life depends on it—because, in a very real sense, it does.
Frequently Asked Questions
What constitutes a "Hardship" in the eyes of the IRS?
The IRS maintains a strict definition of hardship, generally limited to:
- Expenses for medical care for yourself, your spouse, or your dependents.
- Costs related to the purchase of a principal residence (excluding mortgage payments).
- Tuition and related educational fees for the next 12 months.
- Payments necessary to prevent eviction from your principal residence or foreclosure.
- Burial or funeral expenses.
- Expenses for the repair of damage to your principal residence that would qualify for a casualty deduction.
Is there any way to avoid the 10% penalty?
There are specific exceptions, such as for certain unreimbursed medical expenses that exceed 7.5% of your adjusted gross income, or if the withdrawal is related to a qualified birth or adoption. However, these are narrow; for the average worker, the penalty is almost always applicable.
Can I replenish the 401(k) after a hardship withdrawal?
No. Because the money is withdrawn as a distribution, it cannot be "put back." The IRS does not allow for the re-contribution of hardship withdrawals, making the impact on your long-term retirement balance irreversible.
Final Thoughts
Choosing between paying for a roof over your head today and having money in your bank account in thirty years is a choice no one should have to make. However, the data is clear: the path to financial independence requires protecting your retirement accounts from the emergencies of today. By prioritizing the creation of a modest liquid emergency fund, you are not just saving money—you are buying yourself the freedom to navigate life’s inevitable crises without sacrificing your future security. Start small, stay consistent, and keep your retirement funds as a "do not touch" vault whenever possible.