The Digital Revolution: How Fintechs Are Overhauling the Global Cross-Border Payments Landscape
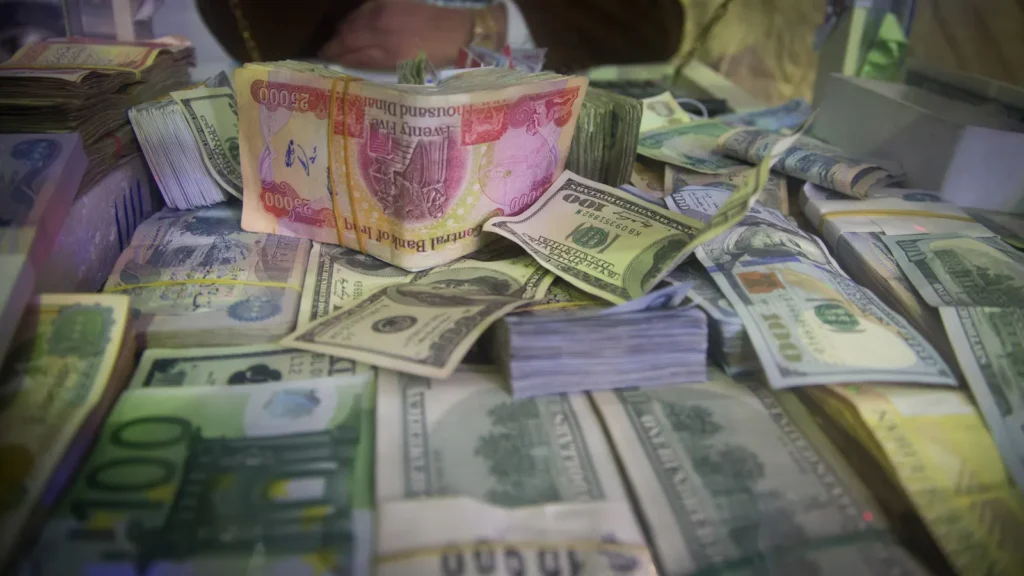
The global financial system is undergoing a quiet, high-stakes transformation. For decades, the cross-border payment market was the exclusive domain of legacy banking institutions, governed by the traditional correspondent banking model. Today, that monopoly is eroding. A new wave of agile fintech firms is aggressively capitalizing on modern technology to dismantle the inefficiencies of international money transfers, replacing archaic processes with real-time, transparent, and lower-cost alternatives.
As the industry pivots toward modernization, the relationship between banks and fintechs is evolving from pure competition to strategic, symbiotic partnerships. By integrating advanced tech stacks—ranging from blockchain-based ledgers to digitized invoicing—these newcomers are not just competing with banks; they are helping them rewrite the rules of global finance.
Main Facts: Deconstructing the Correspondent Banking Bottleneck
At the heart of the movement to modernize cross-border payments is a singular, driving objective: reducing the number of intermediaries.
In the traditional model, sending money across borders is akin to a game of "financial telephone." A bank in one country must maintain a relationship with a "correspondent bank" in the destination country. If the recipient does not hold an account at that specific correspondent bank, the funds must be routed through additional local banks. Every single "hop" in this chain represents a new entity that handles the transaction, and crucially, every entity demands a fee for its services.
"There can be multiple players involved in a cross-border transaction, which adds to the complexity and cost of the transaction," explains Mark Majeske, senior vice president of faster payments at fintech firm Alacriti.
This multi-hop architecture is the primary culprit behind the two greatest frustrations in international money transfers: high, opaque costs and slow processing times. When a sender initiates a payment, they often cannot see the full fee structure upfront because each intermediary deducts its own cut along the way. Fintechs are entering this space by offering two distinct paths to modernization:
- The Partnership Model: Fintechs provide the underlying infrastructure to help banks modernize their legacy tech stacks.
- The Direct-to-Consumer Model: Fintechs build standalone apps that facilitate transactions directly, bypassing the need for traditional bank-to-bank chains.
Chronology of a Disrupted Industry
The evolution of international payments has been marked by several distinct phases of technological adaptation:
- The Era of Correspondent Banking (Pre-2000s): Banks relied exclusively on the Swift (Society for Worldwide Interbank Financial Telecommunication) network to exchange payment instructions. While secure, the physical movement of money remained tethered to Nostro/Vostro account structures, which are capital-intensive and slow.
- The Fintech Emergence (2010–2018): Early-stage fintechs focused on front-end user experiences, making it easier for consumers to send money. However, these firms still largely relied on traditional banking rails in the background.
- The Blockchain and Stablecoin Pivot (2019–Present): With the maturation of distributed ledger technology (DLT), the industry began to shift toward "atomic settlement"—where the clearing and settlement of a transaction happen simultaneously. The integration of stablecoins—digital assets pegged to fiat currencies—has marked the current frontier of the industry.
- The Regulatory and Interoperability Focus (2024–2026): As noted in the August 2026 report by the U.S. Faster Payments Council, the industry is currently focusing on "bridging the gap." The emphasis has moved from simply inventing new technology to ensuring that these new digital rails can communicate seamlessly with legacy banking systems.
Supporting Data: Why Stablecoins and Blockchain Matter
The shift toward blockchain technology is not merely a trend; it is a structural response to the need for transparency. In a traditional system, a transaction’s journey is often opaque. By contrast, a transaction recorded on a blockchain is immutable and visible on a public, or permissioned, ledger.
"The blockchain centralizes money movement on a single ledger," says Aaron McPherson, principal of AFM Consulting. This is why global messaging networks like Swift are increasingly exploring blockchain integration—not to replace their messaging systems, but to utilize the efficiency of shared, synchronized ledgers.
The Role of Stablecoins
For many, stablecoins—digital assets valued in U.S. dollars—have become the preferred vehicle for cross-border liquidity. Their utility is particularly high in markets facing:
- Hyperinflation: When a local currency is volatile, the stability of a dollar-pegged asset provides a safe harbor for the recipient.
- Liquidity Constraints: Stablecoins allow for 24/7, real-time movement of funds, completely circumventing the weekend and holiday closures that often plague traditional banking systems.
Bo Berg, technical strategist at Avenue B Consulting, highlights that small and midsize banks are now the most active adopters. "Banks rely on fintechs to lift the archaic infrastructure often associated with cross-border payments," Berg notes. By outsourcing this to fintechs, smaller institutions can offer competitive international services without having to build costly, proprietary infrastructure from scratch.
Official Responses and Industry Perspectives
The transition to a modernized system is not without friction. While the benefits of speed and transparency are clear, there remains a "perception of risk" that holds back mass adoption.
The Risk Perception
"There is still a perception of risk around digital assets, and that impacts how ready recipients are to accept stablecoins for cross-border payments," says Enrico Camerinelli, a fintech strategic advisor for Datos Insights. This caution is shared by regulators, who require robust Anti-Money Laundering (AML) and Know Your Customer (KYC) compliance, regardless of the technology used.
The Focus on the Recipient Experience
The U.S. Faster Payments Council, through its cross-border work group, has been vocal about the necessity of interoperability. Mark Majeske, who chairs this group, emphasizes that technology is only as good as its utility. "Improving the recipient experience is key," Majeske states. "The goal is to make the experience better, faster, and easier for the recipient."
The Institutional Advantage
Despite the rapid ascent of fintechs, experts caution against writing off traditional banks. Matt Higginson, a partner at McKinsey & Co., points out that banks possess fundamental advantages that fintechs are still struggling to replicate.
- Regulatory Compliance: Banks have deep, long-standing relationships with regulators and a sophisticated framework for managing global compliance.
- Customer Trust: The "bank-customer relationship" remains a significant moat.
- Local Currency Access: Banks hold the licenses and the physical cash reserves in local currencies that are essential for the final "last mile" of a payment in many jurisdictions.
"Banks are still stronger in these areas," Higginson observes. "The question is when will fintechs be able to challenge banks on these fronts."
Implications: The Future of Cross-Border Payments
The modernization of cross-border payments implies a shift toward a "data-rich" financial ecosystem. It is not just about the money moving faster; it is about the information that moves with it.
Fintechs are currently spearheading the digitalization of transactional paperwork. By attaching invoices, purchase orders, and customs documentation directly to the payment data packet, they are reducing the administrative burden that currently plagues global trade. As Debbie Buckland, a senior director analyst for Gartner, notes, "They help figure out how to get the money moved in as few hops as possible."
Key Takeaways for the Future:
- Fee Transparency: As intermediaries are removed, the "hidden cost" of international transfers will likely vanish, leading to more competitive pricing for end-users.
- The "Hybrid" Bank: We are likely to see the rise of the hybrid bank—an institution that maintains its regulatory compliance and customer relationships while offloading its back-end infrastructure to specialized fintech partners.
- Regulatory Alignment: As blockchain adoption grows, global regulators will likely move toward standardized frameworks for stablecoins, which will further lower the barrier to entry for banks that have been sitting on the sidelines due to risk concerns.
In conclusion, the cross-border payment market is currently in the middle of a significant transition. While the traditional banking model served the world for decades, it is now being optimized by the very innovation that threatened to render it obsolete. The future of global finance will likely not be a binary choice between banks and fintechs, but a sophisticated, high-speed network where the best of both worlds—institutional trust and technological agility—converge to create a more efficient global economy.