The Blind Spot of Modern Markets: How Protectionism and Supply Shocks Threaten Global Inflation
By Şebnem Kalemli-Özcan
Published: October 21, 2026
Main Facts
In the current financial landscape, market sentiment is overwhelmingly dominated by a narrow set of macroeconomic anxieties. Investors, analysts, and policymakers are fixated on soaring public debt levels across advanced economies, persistent upward pressure on sovereign bond yields, and the dizzying, high-stakes valuations surrounding the artificial intelligence (AI) boom.
Yet, this narrow focus has created a dangerous blind spot. While Wall Street and global financial capitals debate the sustainability of tech-driven equity valuations and fiscal deficits, the underlying structural drivers of inflation—namely, supply shocks rooted in aggressive protectionism, trade fragmentation, and geopolitical instability—are being systematically ignored.
The fundamental thesis is straightforward yet deeply unsettling: anyone currently losing sleep over public debt and rising yields must urgently reckon with the supply-side disruptions that are actively being manufactured in the name of safeguarding domestic industries. Tariffs, trade barriers, export controls, and the weaponization of critical supply chains are quietly laying the groundwork for a resurgence of sticky, structural inflation. Markets have momentarily pivoted away from these risks, but economic reality will soon force them back to the forefront.
Chronology of Market Preoccupations
To understand how global markets arrived at their current state of selective amnesia, it is necessary to retrace the shifting narrative of economic anxiety over the past several years.
- Late 2024 to Early 2025: The Geopolitical Supply Shock Era
Global markets were acutely focused on tangible supply-side threats. Discussions centered heavily on the implementation and expansion of sweeping U.S. and European tariffs on key manufacturing and green-energy inputs. Simultaneously, maritime trade nerves were frayed by escalating conflicts in the Middle East, particularly threats and actual disruptions regarding the closure of the Strait of Hormuz—a critical chokepoint for global energy supplies. Inflation was viewed primarily through the lens of supply chain fragmentation and commodity price volatility. - Mid 2025: The AI Inflection Point
As technological advancements in generative AI accelerated, capital expenditure by major hyperscalers (such as Microsoft, Google, Amazon, and Meta) surged to unprecedented heights. Equity markets experienced a profound sector rotation, with tech valuations climbing to levels reminiscent of historical bubbles. Investor attention began to pivot rapidly away from traditional macroeconomic supply concerns toward the viability, monetization, and potential bust cycles of the AI boom. - Late 2025 to Early 2026: The Fiscal Reality Check
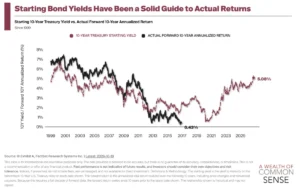
As central banks maintained higher-for-longer interest rates to combat post-pandemic inflation, the cost of servicing ballooning public debt took center stage. Bond markets revolted periodically against fiscal profligacy in the United States and Europe. Rising bond yields became the daily fixation of financial media, crowding out discussions regarding global trade policy. - October 2026: The Present Myopia
Today, from vantage points like Providence and other financial hubs, the ghosts of tariffs and geopolitical chokepoint blockades have ostensibly receded. Investors treat trade restrictions as background noise, assuming that supply chains have successfully "healed" from pandemic-era trauma. This complacency, however, ignores the cumulative, compounding nature of protectionist policies enacted over the intervening years.
Supporting Data and Economic Context
The disconnect between market perception and underlying economic fundamentals can be illustrated through several converging data points concerning fiscal health, trade restrictions, and price pressures:
- The Public Debt Burden:
According to recent International Monetary Fund (IMF) fiscal monitors, global public debt is projected to hover near historic highs, exceeding 90% of global GDP. In advanced economies like the U.S., debt-to-GDP ratios continue to test post-World War II records, keeping downward pressure on bond prices and driving term premia higher. - The Resurgence of Tariffs and Non-Tariff Barriers:
Data from trade monitoring institutions indicate that the number of active restrictive trade interventions—including targeted tariffs, local content requirements, and export bans on critical minerals (such as rare earths, lithium, and semiconductors)—has tripled compared to pre-2020 baselines. - The Cost of "Nearshoring" and "Friendshoring":
Corporate surveys reveal that over 65% of multinational manufacturers have relocated portions of their supply chains over the last three years. While these moves enhance geopolitical resilience, they come at a massive capital expenditure cost. The abandonment of hyper-efficient, least-cost global sourcing in favor of redundant, domestic, or allied-nation networks structurally raises unit production costs. - Persistent Services and Goods Inflation:
While headline consumer price index (CPI) figures retreated from their 2022–2023 peaks, core components—particularly goods prices, which had previously acted as a deflationary anchor due to globalization—have proven stickier than central banks anticipated. Every new tariff iteration acts as a hidden tax passed down to the end consumer.
Official Responses and Policymaker Dilemmas
Central bankers and fiscal authorities find themselves trapped in a difficult policy trilemma. They must balance debt sustainability, financial stability, and price stability against a backdrop of politically driven economic nationalism.
- Central Banks (The Fed, ECB, and BoE):
In public statements, central bank officials have increasingly acknowledged the structural nature of contemporary inflation. Unlike cyclical inflation driven purely by excess aggregate demand, supply-driven inflation caused by trade fragmentation cannot be easily cured by hiking interest rates without inducing severe economic slowdowns. However, monetary authorities remain publicly reticent about explicitly criticizing protectionist industrial policies, as trade policy falls strictly within the purview of elected legislatures and executive branches. - Governments and Trade Ministries:
In Washington, Brussels, and other major capitals, the defense of domestic manufacturing, national security, and strategic autonomy is treated as non-negotiable. Industrial policies—such as domestic subsidy packages and defensive tariffs—are framed as essential tools to protect local jobs and secure technological superiority over geopolitical rivals. Policymakers frequently downplay the inflationary trade-offs of these policies, arguing that short-term price increases are a necessary insurance premium against long-term strategic vulnerabilities. - International Financial Institutions:
Organizations like the WTO and the IMF have issued repeated warnings that the proliferation of trade fragmentation risks shaving percentage points off global GDP over the medium term. They emphasize that while national security concerns are valid, using the blunt instrument of broad-based protectionism inevitably leads to global welfare losses and entrenched price pressures.
Implications for the Global Economy
The willful blindness of financial markets to supply-side risks carries profound implications for investors, corporations, and everyday consumers alike.
1. The Return of Sticky Inflation
Markets are currently pricing in a smooth convergence of inflation rates down to central bank targets of 2%. This optimism relies on the assumption that global supply chains operate as they did in the 1990s and 2000s—fluidly, cheaply, and without political interference.
If protectionist measures continue to accumulate, any negative supply shock (be it a weather event, a labor strike, or a geopolitical flare-up) will trigger disproportionate price spikes. Inflation will not merely be a cyclical phenomenon; it will be structural, volatile, and permanently higher than the post-Cold War norm.
2. The Bond Market Trap
Investors fixated on public debt assume that bond yields are rising purely because of excessive sovereign borrowing supply. But a critical component of the term premium is inflation uncertainty. If trade barriers structurally boost inflation, bond vigilantes will demand even higher yields to compensate for the erosion of purchasing power. Consequently, fiscal policymakers will find debt-servicing costs eating an even larger share of national budgets, creating a vicious feedback loop between fiscal deficits and monetary policy tightening.
3. Corporate Margins and the AI Mirage
The corporate sector is currently bifurcated. On one hand, tech giants and AI beneficiaries enjoy outsized valuations based on transformative growth projections. On the other hand, the traditional industrial, manufacturing, and consumer goods sectors are grappling with rising input costs driven by fragmented supply chains. If structural inflation forces central banks to keep interest rates elevated for longer, the high-flying valuations of the tech sector—which rely on discounted cash flows from the distant future—will face a severe reckoning.
Conclusion
The financial markets’ current obsession with debt, yields, and AI is understandable, but it is dangerously incomplete. By ignoring the slow-burn supply shocks generated by rising trade barriers and nationalist economic policies, investors are preparing to fight the last war while a new inflationary regime takes root.
Until Wall Street and global policymakers reconcile the contradiction between wanting low inflation and supporting destructive trade fragmentation, the global economy will remain acutely vulnerable to the next unexpected disruption.