Balancing Ambition and Reality: A Financial Deep Dive into a Connecticut Couple’s Journey Toward Stability
In the heart of Connecticut, Brian and Michael—a 34-year-old couple preparing to celebrate their tenth anniversary—find themselves at a quintessential crossroads of modern adulthood. While their lives are rich in personal connection, two rescue kittens, and a shared passion for community engagement, the couple has reached a point where their financial trajectory feels misaligned with their long-term aspirations. Like many in their cohort, they are grappling with the tension between wanting to plant roots through homeownership and the persistent weight of consumer debt.
Their story, featured as a "Reader Case Study" on the popular personal finance platform Frugalwoods, offers a candid look at the challenges faced by middle-income households navigating the volatile economic landscape of the 2020s.

The Chronology of a Financial Reset
The past year has been a period of significant upheaval for Brian and Michael. Their journey toward financial clarity was catalyzed by two major life events that forced them to reconsider their long-term planning.
In late 2022, the couple was forced to vacate their long-term home—a cozy 600-square-foot studio that cost a manageable $945 per month. The subsequent search for a new residence during the turbulent 2022–2023 housing market proved to be an exhausting, 3.5-month ordeal. Amidst the chaos of packing and moving, they were also managing the unexpected veterinary expenses of two new kittens.
This period of instability disrupted their original timeline for entering the housing market, which had been set for late 2023. Today, they reside in a luxurious, industrial-style apartment in a converted mill. While the space provides them with the room to work and thrive, the transition served as a wake-up call regarding their financial vulnerability. They now recognize that their previous lack of liquid savings left them exposed during a time of crisis.
Supporting Data: The Financial Snapshot
To address their concerns, the couple provided a detailed breakdown of their financial health, revealing both strengths and areas requiring immediate intervention.
Income and Employment
The couple maintains a robust combined household income of approximately $167,544 annually, with a net take-home pay of $109,455.
- Brian serves as a quality assurance manager for a state-run hospital, a role he secured with encouragement from Michael. This position provides him with significant stability, including generous healthcare benefits and a pension.
- Michael works as a project coordinator for a state behavioral health agency and supplements his income through advocacy and disability leadership coordination, as well as occasional public speaking engagements.
The Debt Burden
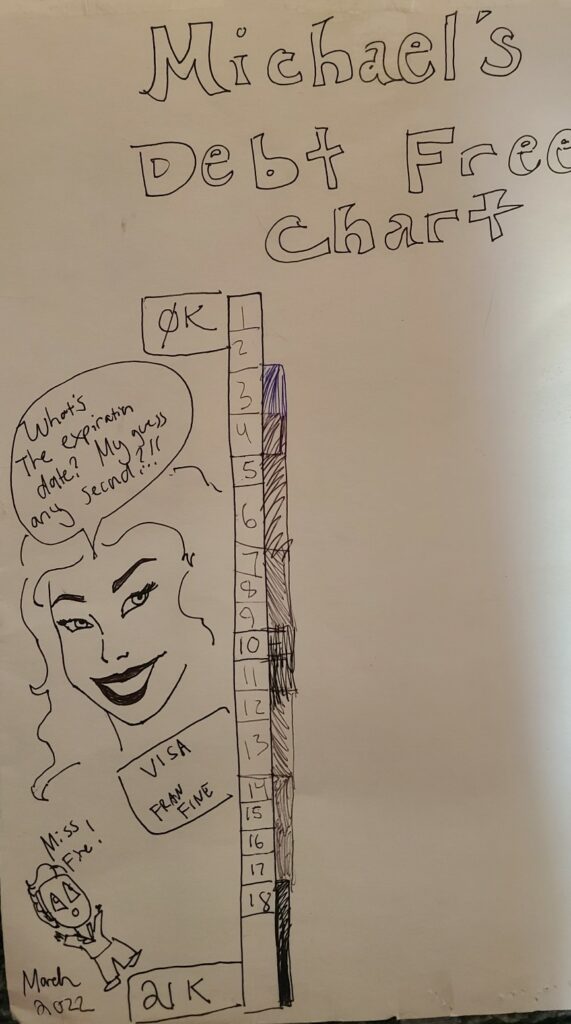
Despite their strong income, the couple is currently carrying $28,259 in consumer debt, primarily spread across three credit cards. While Brian successfully paid off $58,000 in student loans in previous years, he has found himself accumulating new consumer debt. The looming concern for the couple is the interest rate spike scheduled for November 2023, which will shift several of their current 0% or low-interest promotional balances into double-digit interest territory.
Assets and Investments
Their combined asset portfolio stands at approximately $91,250. This includes various retirement vehicles such as 401(k)s, a 403(b), a 457 plan, and a pension fund. However, they express concern that these accounts are underfunded and lack the diversification necessary to weather the long-term uncertainty surrounding Social Security and public pension stability.
Official Guidance: The Frugalwoods Perspective
Liz Frugalwoods, who hosts these case studies, emphasizes that Brian and Michael are in a much stronger position than they believe. "Brian seems disheartened," she notes, "but I don’t share his dismal outlook. A lot of people his age have the goal to achieve what he and Michael already have: a long-term partnership, stable careers, and a comfortable lifestyle."
The "Spreadsheet Problem" Philosophy
Frugalwoods argues that the couple’s issues are fundamentally "spreadsheet problems." By categorizing expenses into Fixed, Reduceable, and Discretionary, she suggests that the couple could potentially free up $4,456 per month to aggressively pay down their debt.
She advises against a permanent "austerity" mindset, which she fears could lead to a "boomerang" effect—where the couple feels deprived and subsequently overspends. Instead, she advocates for a short-term "spending detox" to eliminate discretionary costs, followed by a permanent, mindful approach to budgeting that aligns with their specific life goals.
The Hierarchy of Financial Priorities
In her analysis, Frugalwoods outlines a clear priority list for the couple:
- Debt Elimination: Focus on the high-interest credit card debt immediately to avoid future interest spikes.
- Emergency Fund: Build a robust cash buffer to prevent future "emergencies" (like vet bills or car repairs) from becoming new debt.
- Retirement Contributions: Maximize tax-advantaged accounts (401k, 403b, 457) before diverting funds to other savings goals.
- Homeownership: This is designated as a secondary goal. Buying a house should only occur after the debt is cleared and the emergency fund is fully replenished.
Implications for Future Planning
The case study highlights several critical lessons for professionals in their mid-30s.
The Education Question
One of the most debated topics in the couple’s plan is Brian’s desire to pursue a graduate degree. Frugalwoods provides a stark warning: "Only pursue a master’s degree if it is directly related to a significant salary increase." Without a guaranteed, iron-clad return on investment, she views further education as an unhelpful detour from their goal of becoming debt-free and achieving financial independence.
The Psychological Component of Debt
A recurring theme in the couple’s story is the "shame" they feel regarding their financial standing. This emotional weight is a common barrier to financial success. The guidance provided emphasizes that debt is not a moral failing; it is a mechanical issue. By separating their self-worth from their credit card balances, Brian and Michael can move from a state of emotional distress to one of tactical action.
The Power of "The Middle"
Ultimately, the goal for the couple is to move away from the cycle of "feast and famine." By identifying a "tenable middle ground"—a lifestyle that is sustainable and allows for savings without feeling like constant deprivation—they can begin to build the legacy they desire.
As they move forward, the couple’s ability to adhere to a rigid tracking system will be the true test. Their situation serves as a powerful reminder that while income is a crucial variable in wealth building, it is the discipline of consistent tracking and the courage to align spending with core values that define the path to long-term stability. For Brian and Michael, the next ten years are not just about "adulting"—they are about defining what a life of security and purpose truly looks like on their own terms.