Avant Eyes Banking Evolution: Fintech Giant Files for National Charter to Reshape Credit Access
By Industry Analysis Desk
Published September 23, 2026
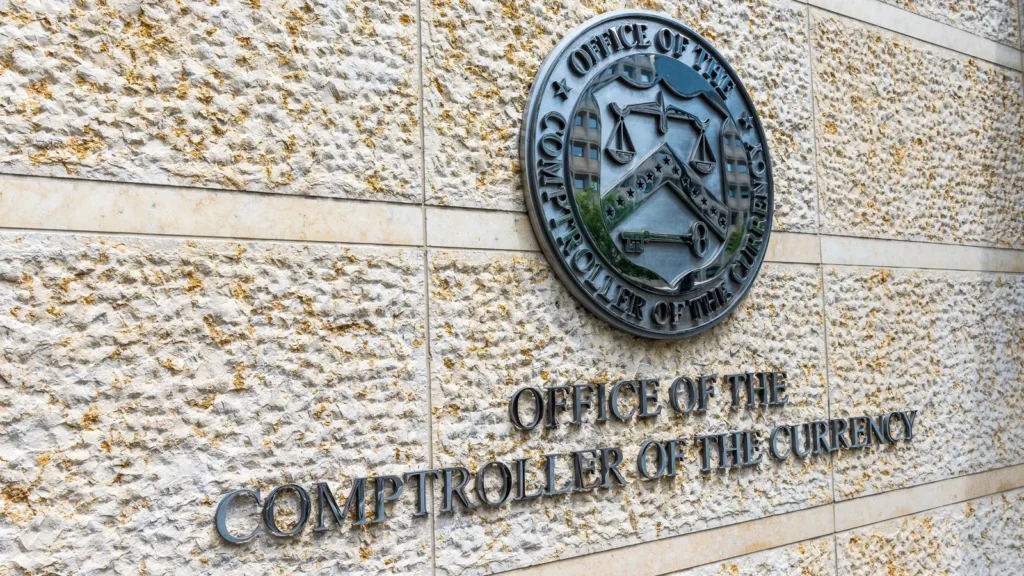
In a move that signals a tectonic shift in the landscape of digital finance, Chicago-based fintech powerhouse Avant has officially filed an application with the Office of the Comptroller of the Currency (OCC) to establish Avant Bank, N.A. This strategic maneuver marks the latest chapter in the company’s decade-plus evolution, transitioning from a specialized online lender into a full-service banking institution. If successful, the move will grant Avant the regulatory muscle to diversify its product suite, optimize its capital structure, and fundamentally alter how it serves the “middle-income” American demographic.
The Core Objective: Why a Charter Matters Now
For over thirteen years, Avant has functioned as a critical bridge between traditional credit institutions and consumers often labeled as "subprime" or "near-prime." By leveraging its proprietary machine learning engine, CreditOS, the firm has successfully bypassed the rigid constraints of traditional bureau-based scoring models to facilitate over $17 billion in credit.
However, operating as a non-bank lender comes with inherent inefficiencies, most notably the “cost of funds.” Currently, Avant must rely on third-party capital partners and market-based funding to back its loans. A national bank charter would fundamentally flip this model. By gaining access to federal deposit insurance and the ability to hold deposits, Avant would secure a lower-cost, more stable source of funding.
“We’ve spent more than thirteen years developing a data-driven approach to credit that serves this population at scale,” said Al Goldstein, co-founder and CEO of Avant, in a recent statement. “A national bank charter would further our mission, help reduce our cost of funds, and enable us to offer products under one regulatory framework.”
Chronology of an Evolution: From Startup to Institution
Avant’s journey to the doors of the OCC was not an overnight decision; it is the culmination of a long-term strategic roadmap:
- 2013: Avant is founded in Chicago with a mission to provide transparent, data-driven credit to middle-income Americans overlooked by legacy banks.
- 2015–2020: The firm scales rapidly, refining its CreditOS algorithm and expanding its product suite to include personal loans and credit cards.
- 2024: Amidst shifting macroeconomic conditions, the company begins preparing its regulatory infrastructure for a potential transition to a bank holding company.
- September 18, 2026: Avant formally submits its de novo bank charter application to the OCC.
- September 23, 2026: Public acknowledgment of the filing confirms the firm’s intent to enter the regulated banking sector.
This progression reflects a broader trend among successful fintechs that have realized that, while technology can disrupt the user interface of banking, the regulatory charter is the ultimate “moat” required to achieve sustainable, long-term profitability.
Supporting Data: The Credit Gap in America
Avant’s pivot is backed by stark economic realities. According to the Federal Reserve’s 2026 report on the economic well-being of U.S. households, roughly one-third of all American adults applied for credit within the previous year. Of that cohort, one-third were either outright denied or received significantly less credit than they requested.
This segment of the population—often referred to as the “missing middle”—is precisely where Avant has focused its efforts. By utilizing CreditOS, Avant analyzes non-traditional data points that standard credit bureaus ignore. As the economy faces ongoing volatility, the demand for these alternative scoring models is reaching an all-time high.
The firm’s argument for a charter is built on the premise of “efficiency for the consumer.” By cutting out the middleman in funding, Avant argues it can pass on savings to the end-user, potentially lowering interest rates for those who currently pay premiums for access to capital.

Official Responses and Strategic Alliances
The filing has been met with optimism from industry consultants who view the move as a validation of the “fintech-as-bank” model. Michele Alt, co-founder of the Klaros Group—a firm that consulted with Avant on the regulatory application—emphasized that this is a pivotal moment for financial inclusion.
“Avant has already facilitated over $17 billion in credit to those who are overlooked by the legacy financial system,” Alt noted. “The bank will build on Avant’s successful model to give these consumers access to affordable credit products and financial tools designed to help them move their financial lives forward.”
Goldstein, meanwhile, has been clear that the goal is not merely growth, but stability. “If approved, a bank charter would enable Avant Bank to operate under one regulatory framework, which supports more consistent access to Avant products no matter where a customer lives in the United States,” he said.
Implications: The Regulatory Landscape
Avant enters a crowded field. Since January 2025, the OCC has received 42 de novo charter applications. The regulator has maintained a cautious but open-minded stance:
- Approved: 27 charters
- Denied: 2
- Returned: 1
- Pending/Under Consideration: The remainder
The industry is watching closely, particularly in light of recent high-profile approvals like Mercury and Nubank. The OCC’s scrutiny is intense, focusing on capital adequacy, risk management protocols, and the applicant’s ability to adhere to stringent consumer protection laws.

Expanding Beyond Credit
A key implication of the charter is the potential for diversification. Currently, Avant is known primarily for credit cards and personal loans. As a bank, the firm would be empowered to offer savings accounts, checking products, and potentially even mortgage or small business lending tools.
“Reducing operational overhead and the cost of facilitating access to credit creates opportunities to pass those savings on to consumers and to reach segments of the population that the economics didn’t previously support,” Goldstein added.
The Road Ahead: Potential Hurdles
While the filing is a milestone, the path to approval is rarely linear. The OCC will conduct an exhaustive review of Avant’s technology stack, its historical lending data, and its internal compliance culture.
- Regulatory Compliance: Avant must demonstrate that its CreditOS is not only effective but also compliant with fair lending laws. The use of machine learning in credit underwriting often faces heightened scrutiny from federal regulators concerned about “black box” decisioning and potential algorithmic bias.
- Capital Requirements: As a national bank, Avant will need to maintain higher capital reserves than it currently does as a fintech. This will likely require the firm to tap into its existing investor base or seek new capital partners to meet the OCC’s Tier 1 capital requirements.
- Market Competition: The move will put Avant in direct competition with community banks and large national institutions that are also upgrading their digital offerings.
Conclusion
The filing for Avant Bank, N.A. represents more than just a bureaucratic shift; it is a declaration of maturity for the fintech sector. By seeking to operate under the OCC’s umbrella, Avant is signaling its transition from a disruptive newcomer to an established pillar of the financial system.
Whether the OCC grants the charter remains to be seen, but the intent is clear: the future of banking for middle-income Americans will be defined by institutions that can effectively merge the agility of machine learning with the stability and trust of a regulated national bank. For now, the industry watches and waits, as the “parade of fintechs” seeking the status of a chartered bank continues to grow, effectively reshaping the U.S. financial architecture one application at a time.