Memories Over Money: Why Financial Security Is Just the Foundation for a Rich Retirement
By Financial Planning Insights
Special to Personal Finance & Retirement Digest
Main Facts
In the world of personal finance, the ultimate goal is almost always framed around accumulation: building a healthy balance sheet, maximizing retirement accounts, minimizing tax liabilities, and securing a nest egg that can withstand the unpredictable storms of the economy. However, a growing philosophy among wealth managers and retirement specialists suggests that financial security is merely a means to an end, rather than the finish line itself.
At the core of this perspective is a simple, potent mantra often echoed by families and financial advisors alike: "Memories over money."
While it may sound counterintuitive coming from professionals dedicated to managing wealth, the consensus among financial planners, behavioral economists, and academic researchers is clear. Money acts as the base of Maslow’s hierarchy of needs—it provides the vital physical security, shelter, and stability required for human survival and peace of mind. Yet, beyond that critical threshold of financial security, the marginal return on additional wealth begins to flatten significantly.
True fulfillment, particularly in retirement and family life, relies on a triad of health, financial security, and deep social connections. When wealth is treated strictly as a scorecard, people risk hoarding assets at the expense of lived experiences. Conversely, those who successfully pivot from maintaining a strict "financial balance sheet" to curating a vibrant "memory balance sheet" consistently report higher levels of long-term life satisfaction and happiness.
Chronology
To understand how a fleeting impulse can transform into a profound lesson in wealth management, one only needs to look at a recent spontaneous trip to Seattle.
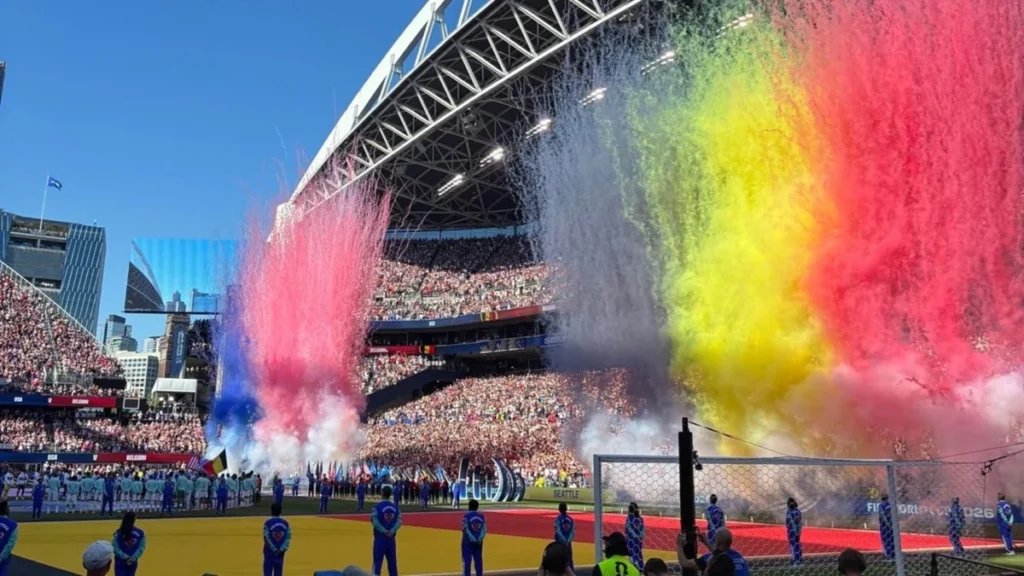
As the United States men’s national soccer team advanced through the 2026 World Cup tournament, the idea of attending a match crossed the mind of the president of Exit 59 Advisory. Initially, the concept was pushed aside. Too many excuses—logistics, cost, short notice, and the chaotic nature of daily life—piled up, making the trip feel impractical.
The turning point arrived just 24 hours before the match. In a moment of clarity, his wife delivered the decisive perspective shift: "Memories over money — just do it."
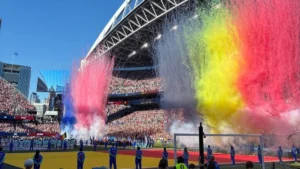
Acting on that encouragement, a whirlwind itinerary was locked in on the Sunday night before the U.S. squad squared off against Belgium in Seattle. The logistics were tight: a single flight, a one-night hotel stay, and a ticket to the stadium.
As sports fans across the country witnessed, the match ultimately did not end in favor of the United States. The team was eliminated in what would sadly be their final appearance of the 2026 tournament. Yet, despite the disappointing outcome on the pitch, the traveler returned home with zero regrets. The sequence—anticipating the event, experiencing the electric atmosphere in a packed stadium, and preserving the memory—delivered a masterclass in experiential value.
Supporting Data and Psychological Frameworks
The philosophy of prioritizing experiences over material possessions is backed by a robust framework of psychological research and financial theory.
The Three-Phase Return on Experiences
Unlike material goods—which often trigger a brief spike in satisfaction followed by rapid adaptation and depreciation—experiences provide value across three distinct phases:
- Anticipation: The psychological lift and excitement derived from planning and looking forward to an event.
- The Experience: The active engagement, sensory input, and emotional resonance during the event itself.
- The Memory: The enduring narrative, storytelling value, and emotional warmth retained long after the event has concluded.
Maslow’s Hierarchy and the Law of Diminishing Returns
Financial planners frequently utilize Maslow’s hierarchy of needs to contextualize money. At the foundation, capital is non-negotiable. Without a secure baseline of financial resources, individuals experience chronic stress, anxiety, and vulnerability, rendering higher-level pursuits difficult.
However, behavioral studies in economics consistently demonstrate that once an individual crosses the threshold of baseline financial security, the happiness derived from accumulating more wealth drops off sharply. Spending discretionary capital on shared experiences, travel, or community gatherings yields a far higher return on investment (ROI) in terms of personal well-being than luxury material upgrades.
Insights from Industry Leaders
Carl Richards, a renowned financial planner, former New York Times personal finance columnist, and prominent public speaker, frequently illustrates this dynamic through a simple Venn diagram sketch. One circle represents "experiences," and the other represents "people you love." The intersection—marked by an emphatic arrow—points directly to the directive: Spend money here.
Similarly, financial author Morgan Housel has extensively explored the art of spending, noting that true wealth is often invisible because it is spent on things that money cannot buy: freedom, time, relationships, and unforgettable moments.
Official Perspectives and Professional Insights
Financial advisory practices across the country are increasingly integrating life planning into traditional wealth management. Rather than merely asking clients how much they have saved for retirement, forward-thinking planners are asking a more probing question: "What do you actually want to do with the freedom your money buys?"
Advisors note that the most rewarding communications they receive from clients rarely revolve around portfolio milestones or tax-loss harvesting. Instead, the standout emails feature phrases such as:
- "I just got back from…"
- "I just booked…"
- "I just committed to…"
These messages are almost universally accompanied by reflections on shared time with family, spontaneous getaways, or long-planned adventures.
Financial planners emphasize that comprehensive retirement plans should always include specific line items for experiential spending. Building a robust financial plan is not meant to be an exercise in permanent deprivation; rather, it is designed to build a fortress of security that grants permission to spend boldly and guiltlessly on what matters most when the opportunity arises.
Implications
The "memories over money" mindset carries profound implications for individuals planning their retirement, raising families, or evaluating their work-life balance.
1. Reframing Childhood Memories
A common counter-argument against spending money on family travel or major events when children are very young is that "they won’t remember it." However, family adventures—even those involving chaotic moments, logistical hurdles, or unexpected illnesses—lay the emotional groundwork for family culture and resilience. Years down the line, these episodes transform from stressful travel mishaps into cherished family lore that sparks laughter and deepens bonds. If young children absorb the value of shared exploration, the impact on older children, teenagers, and adult grandchildren is magnified exponentially.
2. The Power of Contrast
Another vital psychological takeaway is the concept of contrast. Routine breeds monotony. The deep joy and invigoration experienced during a ridiculous, 24-hour whirlwind trip to a soccer match stem directly from how sharply it contrasted with the predictability of day-to-day life. If extraordinary experiences become mundane, they lose their magic. By deliberately stepping outside normal routines, individuals can reset their perspectives and inject vitality into their daily existence.
3. Consistency Over Grandiosity
Creating a memory-rich life does not always require transatlantic flights or expensive stadium tickets. Simple, consistent rituals—such as weekly extended-family dinners maintained over a decade—often yield the highest cumulative emotional dividends.
Conclusion
As wealth advisors look across decades of client relationships, a clear pattern emerges. Those who successfully transition their focus from guarding a static financial balance sheet to enriching a dynamic memory balance sheet experience a far more rewarding retirement. Financial security is essential, but it is ultimately a vehicle. The destination is a life well-lived, filled with stories to tell, connections to cherish, and the enduring realization that, at the end of the day, it is always memories over money.
Disclaimer: This article presents the views of contributing financial professionals and is intended for informational and educational purposes only. It does not constitute formal financial, tax, or legal advice. Readers should verify financial adviser credentials through the SEC (adviserinfo.sec.gov) or FINRA (brokercheck.finra.org) before entering into any advisory relationship.