The Digital Dollar Frontier: OCC Unveils Landmark Rules for Payment Stablecoins
In a move that marks a tectonic shift for the American financial landscape, the Office of the Comptroller of the Currency (OCC) officially released its final rule implementing the GENIUS Act on Wednesday. The regulation, which is scheduled to take effect on January 18, 2026, provides the first comprehensive federal framework for how banks and OCC-regulated entities can interact with, issue, and manage payment stablecoins.
By establishing clear guidelines for reserve backing, redemption rights, and risk management, the OCC is attempting to bring the burgeoning, often volatile, digital asset sector under the umbrella of traditional banking oversight. However, the rule arrives amidst a complex political backdrop, arriving after the dramatic failure of the legislative "Clarity Act" and concerns regarding the influence of private digital asset holdings within the executive branch.
The Chronology of a Regulatory Pivot
The path to the GENIUS Act implementation was far from straightforward. For years, the intersection of decentralized finance (DeFi) and traditional banking has been a site of intense lobbying and partisan friction.
The Legislative Struggle: From the Clarity Act to the GENIUS Act
The current framework is the successor to the "Clarity Act," a legislative proposal that dominated the 2025 Congressional session. The Clarity Act sought to codify a strict boundary between crypto-assets and traditional bank deposits. A central point of contention was the "yield question"—specifically, whether crypto firms should be permitted to offer rewards or interest-bearing incentives on stablecoin balances.
Bank trade groups were vocal in their opposition, fearing that if stablecoin issuers were allowed to use third-party intermediaries to circumvent a ban on interest, billions of dollars could migrate out of traditional deposit accounts, starving community banks of the liquidity needed for local lending.
Despite successfully passing the Senate Banking Committee in May 2025, the Clarity Act ultimately collapsed. The failure was largely attributed to mounting ethical concerns regarding potential conflicts of interest. Critics pointed to the massive income—reportedly $1.4 billion—that President Donald Trump derived from his family’s various crypto enterprises throughout 2025. This prompted a wave of Democratic-led calls for strict conflict-of-interest disclosures and robust language to prevent government officials from personally benefiting from the regulatory structures they helped design.
The OCC’s Regulatory Response
With the legislative route stalled, the OCC took the regulatory baton. The final rule released Wednesday represents the agency’s attempt to synthesize the intent of the Clarity Act while providing the practical guidance necessary for financial institutions to innovate safely. The agency has signaled that it will roll out the application and waiver processes in the coming months, marking the start of a new era of "supervised crypto-banking."
Decoding the Final Rule: A Case-by-Case Approach
The most anticipated—and debated—aspect of the new OCC rule is its stance on stablecoin yields. While the regulation explicitly bans direct yield payments from issuers to stablecoin holders, it provides significant regulatory "wiggle room" by opting for a case-by-case evaluation of third-party arrangements.
The Yield Conundrum
In its text, the OCC acknowledges the complexity of the modern digital asset ecosystem: "Depending on the facts and circumstances, a payment to payment stablecoin holders through an intermediary might be made solely in connection with the holding, use, or retention of a payment stablecoin or might be made, at least in part, for other reasons."
This nuance suggests that while the "spirit" of the law is to prevent stablecoins from functioning as unregulated, interest-bearing savings accounts, the OCC recognizes that some transaction-based incentives may be legitimate business expenses or operational rewards rather than interest. The rule clarifies that transaction-based payments that do not amount to yield, or are not tethered strictly to the act of holding the asset, may be permitted.
The "Omissions": AML and BSA
Notably, the rule remains silent on critical areas related to the Bank Secrecy Act (BSA), anti-money laundering (AML) protocols, and sanctions administered by the Office of Foreign Assets Control (OFAC). The OCC noted that these parameters are currently being developed in a separate, coordinated rulemaking process with the Treasury Department. By separating these concerns, the OCC is likely attempting to establish the fundamental banking framework first, before layering on the complex, inter-agency compliance requirements necessary to satisfy national security and financial crime mandates.
Official Responses and Strategic Implications
The reception to the final rule has been polarized, reflecting the broader tension between technological optimism and institutional caution.
The Treasury’s Vision
Treasury Secretary Scott Bessent, in a statement that drew parallels to the historic National Currency Act of 1863, described the rule as a "watershed moment." By invoking the legacy of Abraham Lincoln, Bessent framed the GENIUS Act as a necessary evolution of the American financial system to maintain its global standing. Echoing the pro-crypto sentiment of the current administration, Bessent reaffirmed the goal of cementing the United States as the "crypto capital of the world," suggesting that the regulation is not merely a restriction, but a competitive strategy.
The Regulator’s Stance
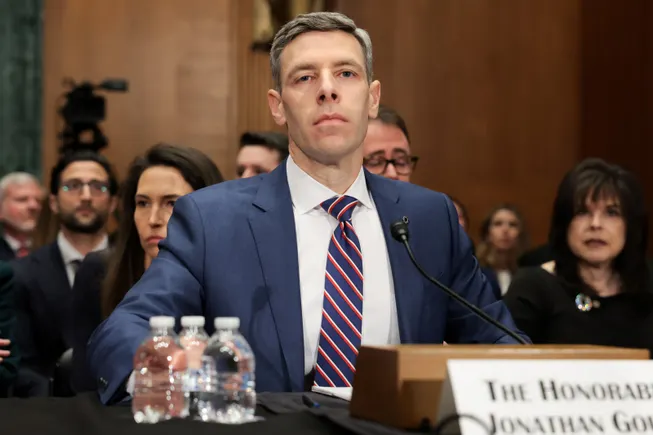
Comptroller of the Currency Jonathan Gould emphasized the "responsible growth" aspect of the rule. "The OCC is drawing on its longstanding supervisory expertise to support responsible growth and innovation for this new industry," Gould stated. By prioritizing "strong standards for reserve backing and redemption," the OCC is effectively telling the crypto market that it is welcome to participate in the banking system, provided it adheres to the same safety and soundness standards that have governed banks for over a century.
The Community Banking Warning
Conversely, the Independent Community Bankers of America (ICBA) remains highly skeptical. The trade group has been a vocal critic of the potential impact of stablecoins on the grassroots economy. Their research suggests that widespread adoption of payment stablecoins could trigger a decline of at least $850 billion in community bank lending.
"We remain focused on ensuring the OCC’s policies protect against the risks that payment stablecoins pose to community bank lending, local communities, and financial stability," the ICBA stated. The group continues to press for rigorous operational limits and the strict enforcement of the prohibition on interest payments, fearing that any regulatory "wiggle room" will be exploited by large, non-bank fintech entities to the detriment of local depositors.
Economic Implications: A Balancing Act
The implementation of the GENIUS Act creates a new, regulated pathway for the integration of digital assets into the US economy. The implications are far-reaching:
- Systemic Stability: By requiring stablecoin issuers to hold transparent, high-quality reserves, the OCC aims to prevent the "run on the bank" scenarios that have historically plagued crypto-assets.
- Institutional Adoption: With a federal framework now in place, traditional banks are more likely to begin issuing their own payment stablecoins or partnering with established, compliant providers. This could lead to faster, cheaper settlement times for cross-border payments.
- The "Liquidity Drain" Risk: As the ICBA points out, the potential shift of deposits from traditional accounts into stablecoins remains a significant macroeconomic risk. If stablecoins become the preferred medium for short-term liquidity, the traditional deposit-based lending model could face a structural contraction.
- Regulatory Evolution: The OCC’s promise to "closely monitor" the industry signals that this rule is a baseline, not a final destination. As the technology matures, we should expect regular updates to the supervisory framework to address emerging risks in cybersecurity, cross-chain interoperability, and decentralized governance.
As the industry prepares for the January 18 effective date, all eyes will be on how the OCC interprets its "case-by-case" mandate. The agency is walking a tightrope: too much leniency could invite systemic risk and jeopardize the banking system, while too much rigidity could stifle the very innovation that the Treasury Secretary is so eager to cultivate.
Ultimately, the GENIUS Act serves as a testament to the fact that digital assets are no longer a peripheral concern. They have arrived at the center of American fiscal policy, and for the first time, the federal government has a clear, albeit complex, roadmap for their integration into the bedrock of the global financial system. The coming years will reveal whether this framework provides the stability necessary for growth or if it merely formalizes the risks of a new, digital frontier.