Navigating the Complexities of Inheriting a Family Home With Siblings
Inheriting a residential property alongside your siblings may sound like a straightforward blessing, but it frequently triggers a complex cascade of legal, financial, and emotional hurdles. Unlike a liquid bank account or a stock portfolio, a house cannot be easily divided down the middle. One sibling may desperately want to sell the property to fund a down payment or retirement, while another hopes to preserve it as a sentimental anchor for the family.
What happens next depends on a intricate mix of estate plans, how the deed was titled, and applicable state laws. Because a family home is often the single largest asset passed down through generations, making informed decisions is critical to safeguarding both your financial health and your familial relationships.
Main Facts: What It Means to Co-Own an Inherited House
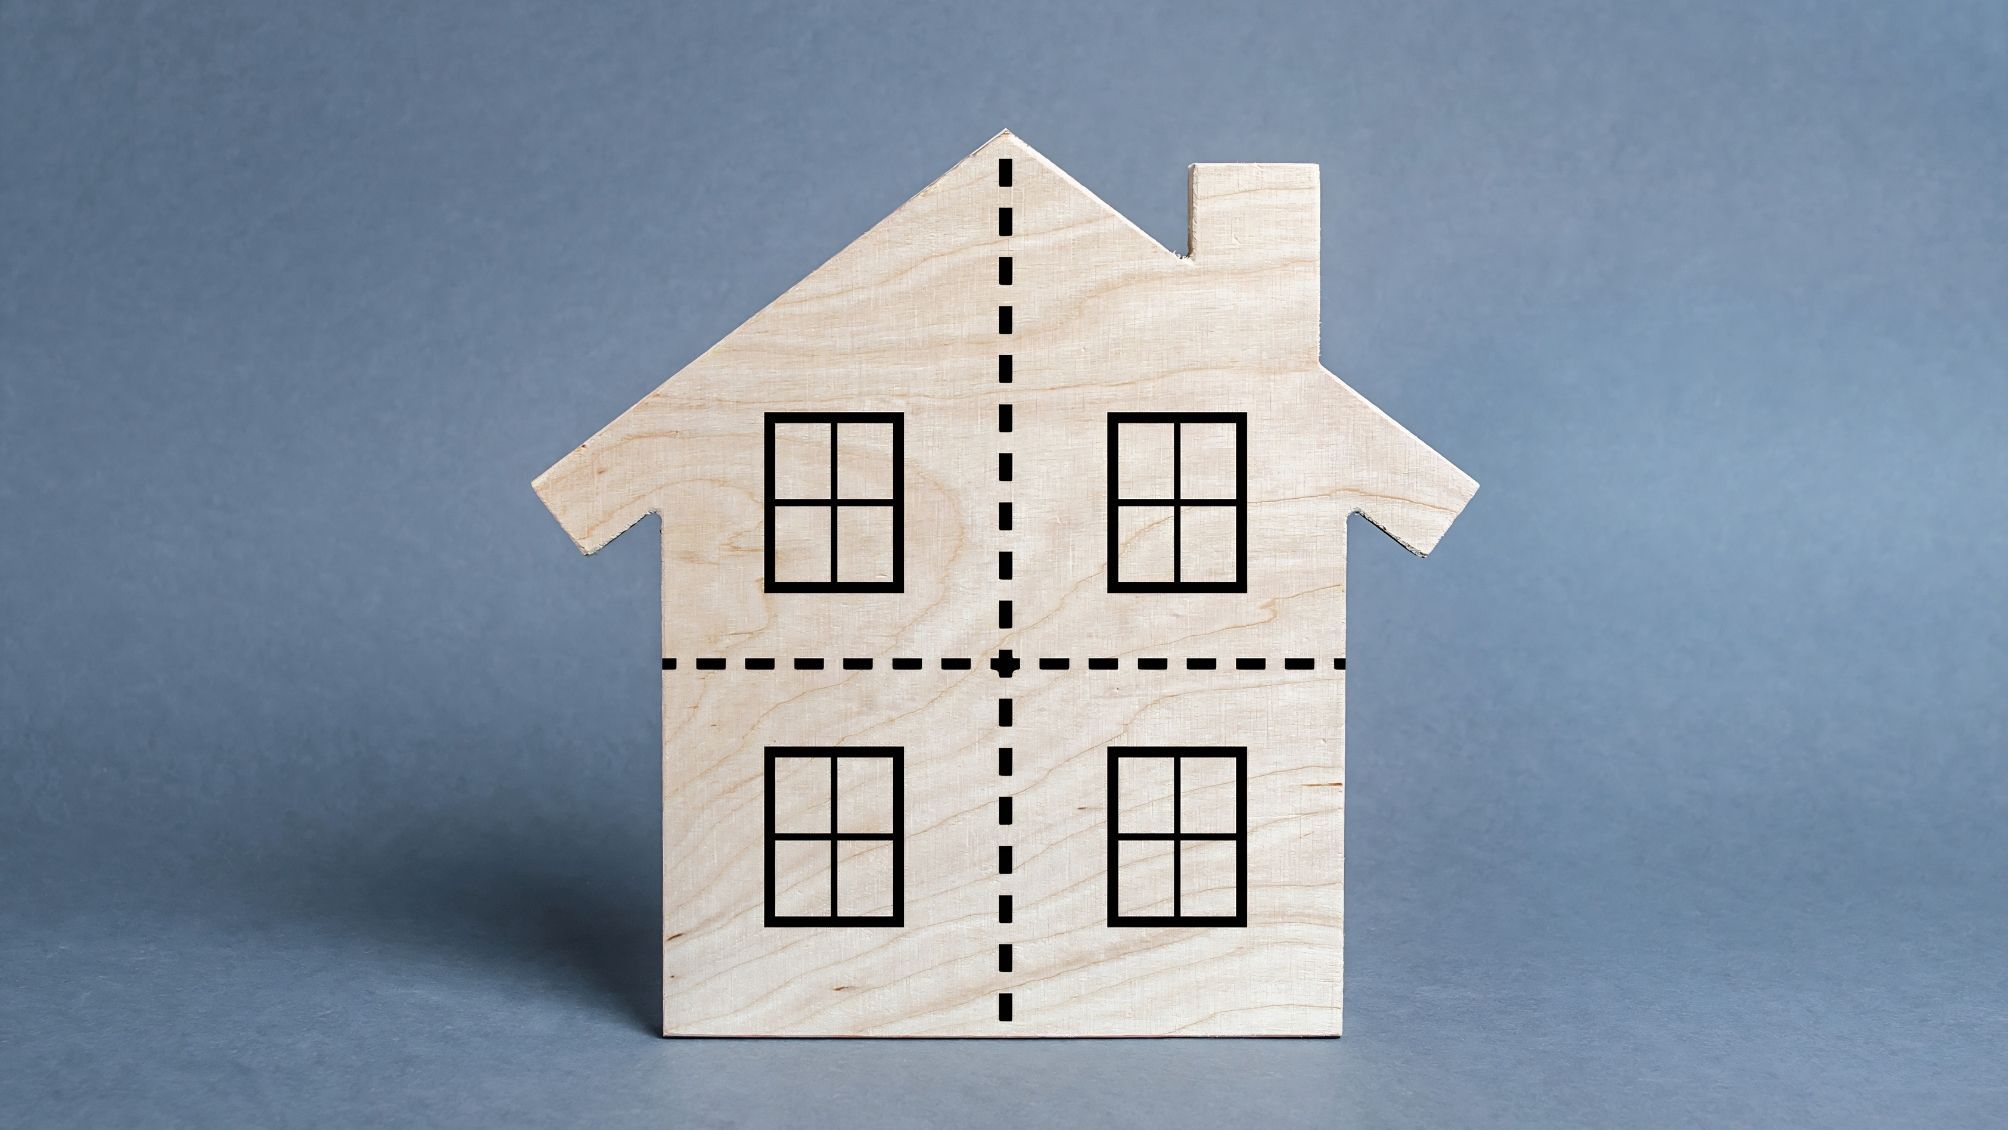
When parents leave a home to multiple beneficiaries, the children rarely receive a neatly carved-out physical portion of the property. Instead, they typically acquire a shared co-ownership interest. If a home is left equally to three siblings, for instance, each generally holds a one-third undivided interest in the entire property.
Immediate control of the real estate is rarely guaranteed. If the home is wrapped up in an estate that must pass through probate, an executor or personal representative retains legal authority to manage the property while the estate is administered. Properties transferred through living trusts or specific beneficiary deeds, however, may bypass probate entirely and transition to heirs more swiftly.
Hidden Obligations and Liabilities
Before determining the future of the home, beneficiaries must establish precisely what they are inheriting. This requires investigating:
- Outstanding mortgages and home equity loans.
- Delinquent or upcoming property tax bills.
- Mechanics’ liens, utility arrears, or other encumbrances tied to the property.
The estate’s attorney or executor can provide essential clarity regarding who holds legal title, when control transfers to the heirs, and which debts must be resolved before the property can be sold or transferred.
Chronology: The Step-by-Step Process of Managing an Inherited Property
Handling an inherited home requires a structured timeline to prevent administrative chaos and financial strain.
Phase 1: Probate and Estate Administration
Upon the passing of a parent, the estate enters administration. During this period, the court-appointed executor secures the property, ensures it is insured, and pays ongoing bills from estate funds. Heirs should avoid making unilateral alterations or moving into the home during this phase without the executor’s formal consent.
Phase 2: Valuation and Ownership Transfer
Once probate concludes or the trust provisions take effect, title officially transfers to the beneficiaries. At this stage, heirs must secure an independent, professional appraisal. A neutral valuation provides an objective baseline for buyouts, sales, or tax reporting.
Phase 3: Immediate Financial Management
Even if the ultimate goal is to sell the house, the estate settlement process can take months. During this interim period, ongoing costs—such as utilities, lawn maintenance, homeowner’s insurance, and mortgage payments—accumulate. Heirs must establish a written agreement detailing who pays these short-term expenses and whether those payments will be reimbursed from final sale proceeds.
Phase 4: Resolution (Keep, Sell, or Buyout)
Heirs must ultimately choose one of three paths:
- Sell the home: Liquidating the property and dividing the net proceeds according to ownership shares.
- Buyout: One or more siblings purchase the ownership shares of the other heirs.
- Co-ownership: Retaining the home as a shared investment or vacation property (the most legally complex option).
Supporting Data: The Generational Disconnect on Inheritance
Data from a Morning Consult survey commissioned by Kiplinger for the Trillion Dollar Talk campaign highlights significant perceptual gaps between parents and their adult children regarding inheritances, real estate, and taxation.
- Real Estate as Wealth: 33% of parents state that real estate will make up the single greatest share of their children’s inheritance. Conversely, only 24% of adult children expect real estate to dominate their inheritance portfolio.
- Tax Expectations: 34% of adult children anticipate paying taxes on their inheritance, while only 20% of parents expect their children to face a tax burden.
- Equal Distribution: 71% of parents with multiple children intend to divide their estates equally, but only 47% of adult children expect an equal split.
- Family Friction: Among adult children with siblings, 33% believe that inheriting assets is likely to spark conflict among family members. Furthermore, when asked what they most wanted to know about their parents’ estate plans, 11% specifically requested clarity on asset distribution and division.
Official Guidelines: Tax Implications and Professional Resources
Navigating the tax landscape of an inherited home requires careful attention to federal and state regulations.
The Stepped-Up Basis Rule
Generally, inheriting property does not trigger federal income tax on the asset’s total value at the time of receipt. However, selling the property introduces capital gains tax considerations, moderated by the crucial concept of the stepped-up basis.
Under current tax law, the tax basis of inherited property is adjusted (stepped up) to its fair market value as of the date of the original owner’s death.
- Example: If a parent purchased a home for $150,000 decades ago, and it is valued at $400,000 when they pass away, the children’s tax basis becomes $400,000. If the heirs subsequently sell the home for $420,000, they only owe capital gains tax on the $20,000 appreciation above the stepped-up basis, rather than the $270,000 gain calculated from the original purchase price.
State-Level Considerations
In addition to federal rules, heirs must look closely at state estate or inheritance taxes, which vary widely depending on where the deceased resided. Because tax codes are notoriously intricate, financial advisors strongly recommend consulting a certified public accountant (CPA) or estate tax professional before finalizing a buyout or executing a sale.
Implications: Managing Family Dynamics and Conflict Resolution
A residential property carries a heavy dual nature: to one sibling, it is a financial asset capable of funding a retirement account or clearing student debt; to another, it is a cherished shrine filled with decades of childhood memories. These competing emotional priorities often fuel severe familial friction.
When Agreements Break Down
If co-heirs reach an absolute deadlock, one owner cannot unilaterally sell the entire property without the consent of the others. However, depending on state law, a disgruntled co-owner can petition the court for a partition action.
A partition action forces a legal review that often results in a court-ordered sale of the property, with proceeds distributed among the owners according to their legal shares. Because court-ordered litigation is notoriously expensive, time-consuming, and emotionally draining, it should always be viewed as an absolute last resort.
Best Practices for Preserving Relationships
To minimize tension and prevent fractured family dynamics, experts recommend several proactive measures:
- Separate Sentiment From Finance: Acknowledge the emotional value of the home, but require any sibling wishing to retain the property to mathematically prove they can independently shoulder the mortgage, property taxes, insurance, and maintenance costs.
- Put Everything in Writing: Formalize agreements regarding interim expense payments, occupancy rules (such as whether an occupying sibling must pay fair-market rent), and reimbursement structures.
- Engage Neutral Professionals: When informal family meetings stall, enlist the services of an estate attorney, a professional mediator, or a fee-only financial planner to guide objective decision-making.
- Initiate Early Conversations: The best time to discuss the fate of a family home is long before the inheritance becomes an immediate reality. Open communication between parents and children regarding estate plans can dramatically reduce post-loss confusion and align expectations.