The Retirement Paradox: Why Booming Markets Make Leaving the Workforce Both Tempting and Treacherous
October 25, 2026
By Ben Carlson (Adapted and Expanded for Professional Financial Journalism)
Main Facts: The Great Early Retirement Wave and the Market Peak Paradox
Financial planning presents a uniquely cruel psychological paradox: individuals receive countless "at-bats" to practice minor financial decisions—such as daily budgeting, discretionary spending, and routine investing—yet face life-altering milestones with virtually no rehearsal. While a person might choose multiple homes, secure several mortgages, or pivot through various career paths across a lifetime, retirement is fundamentally a one-shot event. Short of reincarnation, everyone enters their golden years under a "trial by fire" scenario.
This finality is what makes the transition into retirement profoundly nerve-wracking. Future retirees are perpetually haunted by a barrage of unanswerable "what-ifs":
- What if inflation outpaces historical projections?
- What if portfolio returns fall flat over the next decade?
- What if you hand in your resignation right on the cusp of a brutal bear market?
- What if your savings simply run dry before you do?
Timing, as it turns out, is everything, and right now, market conditions are tempting a massive wave of workers to make the leap. Confidence is riding high across the board. Driven by a historic, multi-year bull market in equities and soaring residential real estate values, household balance sheets look robust. Anyone who has held risk-bearing assets throughout this recent cycle is outperforming historical averages.
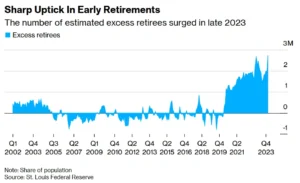
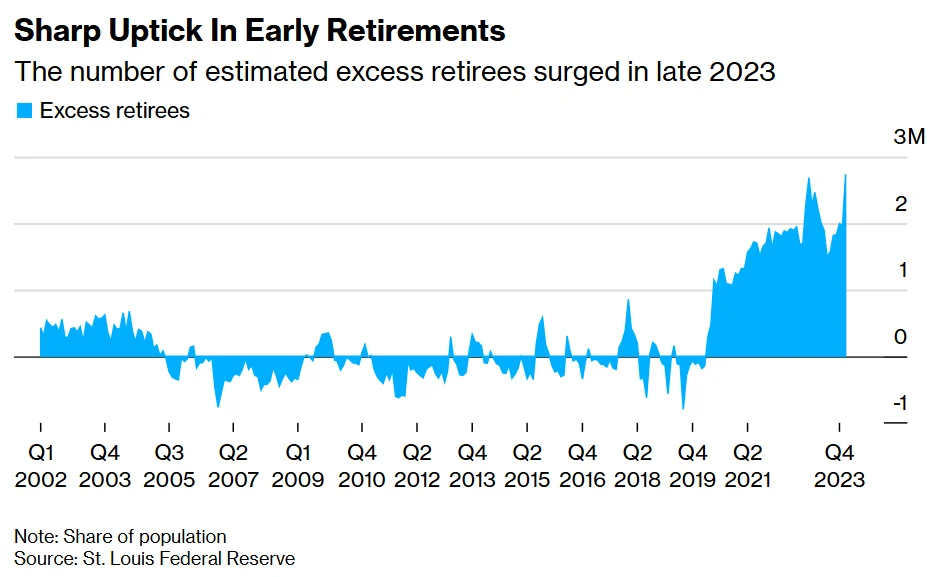
Consequently, a profound psychological and demographic shift is underway. A wave of early retirements is sweeping the nation, heavily documented by financial tracking groups like Bloomberg, which recently highlighted a sustained, upward trajectory in early exits from the labor force. No one naturally dreams of retiring during a market downturn; human instinct drives people toward the exits precisely when asset prices are cresting. Yet, financial historians and researchers warn that this very surge in confidence may plant the seeds of future financial vulnerability.
Chronology: A Historical Look at Retirement Timing and Market Cycles
To understand the perils of retiring at a market peak, one must look back at how economic cycles have historically punished—and occasionally spared—new retirees.
- The Dot-Com Precipice (March 2000): Consider the cautionary tale of a specific couple who chose to retire right at the absolute peak of the dot-com bubble in March 2000. Immediately following their departure from the workforce, the broader stock market plunged by roughly 50% in what became one of the longest and most grinding bear markets in modern economic history.
- The Global Financial Crisis (2007–2009): Just as equities clawed their way back toward recovery years later, the Great Financial Crisis struck, sending the market into a freefall of nearly 60%. For this specific couple, the stock market effectively went nowhere for the entire first decade of their retirement. By all conventional metrics, it was a financial nightmare scenario.
- The Post-Pandemic Boom (Early 2020s – 2026): Fast-forward to the present era, and a strikingly similar psychological dynamic is playing out. Following years of post-pandemic monetary stimulus, tech-driven equity rallies, and real estate appreciation, workers are once again exiting the workforce in droves.
The historical timeline demonstrates that economic environments do not wait for workers to adjust their retirement clocks. While the 2000-era couple survived through a disciplined mix of asset diversification, aggressive cash management, intelligent portfolio rebalancing, and sheer spending flexibility, their survival highlights a core truth: retirement longevity is expanding, and modern retirees must prepare to navigate 20, 30, or even 40 years of shifting economic landscapes.
Supporting Data: The University of Missouri Study and Sequence of Return Risk
The dangers of retiring at market highs are not merely speculative; they are backed by empirical academic research. Morningstar’s personal finance expert Christine Benz recently spotlighted a pivotal 2012 study conducted by researchers at the University of Missouri that illuminates this exact behavioral trap.
The study revealed a counterintuitive and sobering reality: workers overwhelmingly choose to retire precisely when the stock market is cresting and confidence is at a peak. However, this behavioral tendency drastically undermines a portfolio’s structural durability. Unless a newly minted retiree immediately shifts the vast majority of their holdings out of risk assets and into guaranteed income vehicles like annuities, they expose themselves to severe systemic vulnerabilities.
This vulnerability is formally known in financial science as Sequence of Return Risk.
- The Mechanics of the Risk: Sequence of return risk refers to the mathematical reality that the timing of your investment returns matters just as much as the average return itself. Experiencing negative or flat returns right at the outset of your retirement—while simultaneously liquidating portfolio shares to fund living expenses—causes permanent structural damage to your asset base.
- The Math of Selling Low: When you are forced to sell depressed assets to pay for basic living costs, you lock in losses. Those shares can never participate in the subsequent market recovery, drastically accelerating the depletion rate of your nest egg.
When above-average market returns induce a false sense of security, retirees often overlook this danger. They lean heavily into their inflated account balances, unaware that they are walking straight into a sequence-of-returns trap.
Official Responses and Expert Insights: Perspectives from the Industry
As market valuations remain elevated and early retirement rates surge, financial luminaries are sounding notes of caution while offering tactical solutions.
In a recent collaborative discussion on the Talking Wealth platform, Christine Benz joined financial commentator Ben Carlson to dissect the complexities of retiring at the tail-end of a historic bull market. The dialogue focused heavily on moving beyond naive retirement projections and adopting modern defensive strategies.
According to Benz and Carlson, modern retirees must abandon rigid, outdated withdrawal templates and instead embrace dynamic frameworks. Key strategies discussed included:
- The Bucket Strategy: Dividing portfolio assets into distinct "buckets" (cash for short-term needs, fixed income for medium-term stability, and equities for long-term growth) to insulate living expenses from short-term market downturns.
- The 4-Year Rule and Spending Flexibility: Adapting traditional withdrawal guidelines by incorporating a dynamic "4-year spending rule," which advocates for tighter expenditure controls or cash reserves designed to cover multi-year market droughts without forcing the sale of depressed equities.
- The 10-Year Retirement Plan: Structuring asset distribution windows to ensure that the first decade of retirement—the most critical danger zone for sequence-of-return risk—is fully armored against catastrophic market drawdowns.
Experts emphasize that while individuals cannot control macroeconomic shocks or bear markets, they retain total control over how their portfolios are structured before the transition day arrives.
Implications: Stress-Testing Your Plan for the Worst-Case Scenario
The ultimate implication for today’s prospective retirees is clear: a booming economy and a high portfolio balance are fantastic launchpads, but they are insufficient guarantees of a secure, multi-decade retirement.
Because retirement is a one-way street with no trial runs, approaching the transition with uncritical optimism is a dangerous gamble. Whether current market conditions ultimately manifest as the worst time to retire in a generation or merely a minor bump in a long bull run remains to be seen. However, prudent financial planning requires preparing for the worst while hoping for the best.
Financial advisors strongly recommend that anyone contemplating an early exit from the workforce take the following steps:
- Comprehensive Stress-Testing: Run portfolio simulations under adverse scenarios, assuming high inflation, prolonged stagnant equity returns, and immediate bear-market contractions upon day one of retirement.
- Build Contingency Liquidity: Ensure that at least two to four years’ worth of living expenses are safely stashed away in cash or ultra-short-term, risk-free instruments. This prevents the panic-selling of equities during a market crash.
- Embrace Lifestyle Flexibility: Build a spending plan that can absorb temporary contractions. Being willing to trim discretionary travel or delay major capital expenditures during severe market downturns can preserve a portfolio’s longevity indefinitely.
Confidence and portfolio values may currently sit at all-time highs, but true financial peace of mind comes not from a rising market tide, but from a resilient plan built to weather the storms that will inevitably follow.