The Sam Vimes Retirement Tax Trap: Why Deferring Taxes Now Leaves You with "Wet Feet" Later
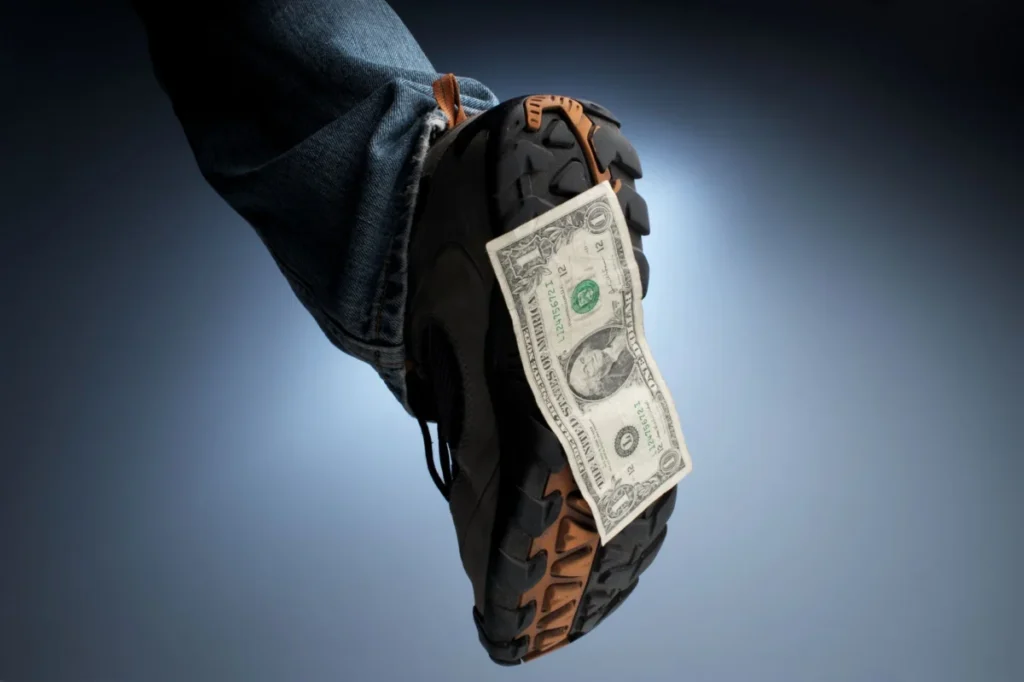
Applying a classic economic parable from Terry Pratchett’s Discworld reveals how everyday retirees can patch their nest eggs against hidden tax spikes without needing an immediate fortune.
Main Facts
In his 1993 Discworld novel Men at Arms, Captain Samuel Vimes immortalized an economic reality known to the working class: the "boots theory" of socioeconomic unfairness. A wealthy man can afford a $50 pair of durable leather boots that last a decade, while a poor man, restricted by an immediate $10 budget, must buy cheap cardboard-soled shoes that disintegrate every year. Over ten years, the poor man spends $100 and still suffers from wet feet, while the rich man preserves both his investment and his comfort.
In retirement planning, the traditional advice to maximize pre-tax 401(k) and IRA contributions mimics this exact economic trap. Deferring taxes during your working years feels like a prudent, frugal choice—yielding immediate tax relief and employer matches. However, doing so without a long-term exit strategy is the financial equivalent of buying cardboard-soled boots. It trades a minor, short-term savings for a compounding tax liability that explodes down the road in the form of higher federal tax brackets, mandatory withdrawals, and Medicare surcharges.
Fortunately, retirees do not need a multi-million-dollar cash reserve to protect their portfolios. Just as a resourceful worker can patch an old pair of boots, retirees can utilize low-cost levers—such as micro-conversions, strategic account sequencing, and qualified charitable distributions—to systematically plug tax leaks year by year using the funds they already possess.
Chronology
To understand how modern retirees fall into the deferred-tax trap, it helps to trace the timeline of a typical saver’s financial life:
- The Working Decades (Ages 25–65): Savers are inundated with standard financial guidance: maximize pre-tax accounts, lower your adjusted gross income (AGI), and bank the immediate tax savings. Compound growth builds massive balances inside traditional 401(k)s and IRAs, but every dollar of growth represents future taxable income.
- The Retirement "Gap Years" (Ages 65–72/75): The critical transition window after retiring from a primary career but before government-mandated withdrawals begin. During these early years, earned income drops to zero, creating a unique window of low tax brackets before Social Security and forced distributions kick in.
- The RMD Threshold (Ages 73–75): Under current federal rules, Required Minimum Distributions (RMDs) force retirees to pull mandatory percentages out of their pre-tax accounts annually. This injects unwanted taxable income directly into their tax returns, frequently pushing them into higher marginal brackets whether they need the cash flow or not.
- The Legacy and Late-Stage Years: Unmanaged accounts compound the tax burden upon the retiree’s death, passing heavy tax liabilities onto heirs who inherit traditional IRAs and must drain them within a strict ten-year window.
Supporting Data: The Four "Tax Leaks"
Without proactive orchestration, four primary financial mechanisms act as the "cardboard soles" of retirement, steadily eroding wealth through avoidable government levies and surcharges.
1. Required Minimum Distributions (RMDs)
When individuals reach ages 73 to 75, federal law dictates that pre-tax accounts must start shedding cash. Because traditional IRA and 401(k) withdrawals count as ordinary income, these mandatory distributions can instantly inflate a retiree’s tax baseline.
- The Fix: Implement "micro-conversions" during the retirement gap years. Moving small chunks of money—such as $1,000 annually—from a traditional IRA to a Roth IRA systematically chips away at future RMD liabilities. Because marginal tax brackets are filled incrementally, a retiree can manage conversions at the lowest possible rates (e.g., 10% to 22%), keeping the tax cost as low as $100 to $220 per year.
2. The Social Security "Tax Torpedo"
Unmanaged pre-tax withdrawals do not exist in a vacuum; they stack directly on top of Social Security benefits. This triggers a complex statutory formula that can render up to 85% of a retiree’s Social Security income fully taxable.
- The Fix: Blend tax-free Roth withdrawals or Health Savings Account (HSA) funds to pay for discretionary expenses like travel or home renovations. By drawing down taxable brokerage accounts up to the 0% long-term capital gains threshold—or utilizing tax-loss harvesting—retirees can satisfy cash needs without artificially raising their ordinary income baseline.
3. Medicare IRMAA Surcharges
In retirement, a single extra dollar of taxable income can trigger an exponential financial penalty. Crossing the Income-Related Monthly Adjustment Amount (IRMAA) threshold automatically increases monthly premiums for Medicare Parts B and D two years down the line, costing thousands of dollars out of pocket.
- The Fix: Adopt the "three-bucket" withdrawal strategy, coordinating funds across taxable, tax-deferred, and tax-free accounts. Keeping your Modified Adjusted Gross Income (MAGI) smoothly distributed prevents you from accidentally stepping over IRMAA cliff edges.
4. Charitable Waste
Donating cash directly out of a checking account ignores powerful tax-slashing mechanisms available to older adults.
- The Fix: For individuals aged 70½ or older, a Qualified Charitable Distribution (QCD) allows direct transfers of up to $111,000 per person annually from an IRA to a qualified charity. This satisfies charitable impulses and reduces future RMDs without adding a single dollar to taxable income. Furthermore, standard deduction filers can leverage upcoming charitable tax deductions to capture savings on direct contributions.
Official Responses and Expert Perspectives
Financial planners, tax accountants, and economists widely agree that the "one-size-fits-all" approach to retirement savings—namely, deferring taxes at all costs—is fundamentally flawed for the middle class.
Industry analysts point out that while high-income earners with vast non-retirement assets can easily afford the hefty upfront tax bill required to convert traditional accounts to Roth IRAs, everyday savers cannot. Consequently, financial experts are increasingly championing "bracket management" and incremental tax planning.
"The traditional advice assumes tax rates will be lower in retirement, or that your income will naturally drop," notes retirement tax strategist Liam Vance. "For many savers, neither assumption holds true. Between pensions, Social Security, and required distributions, retirees often find themselves in higher tax brackets than they were in their peak earning years. Without a deliberate plan to drain pre-tax accounts in a controlled manner, the government becomes your primary retirement beneficiary."
Implications for Everyday Savers
The broader implication of the Vimes "boots theory" applied to personal finance is that structural economic systems naturally favor those with upfront liquidity. However, recognizing this trap is the first step toward neutralizing it.
Retirees and pre-retirees must shift their mindset from passive tax avoidance during their working years to active tax management during retirement. This requires a fundamental pivot:
- Audit Your Asset Mix: Review where your wealth is concentrated. If 90% or more of your retirement savings sit in pre-tax accounts, you are sitting on a ticking tax time bomb.
- Map Your Gap Years: Calculate the exact window of time between your retirement date and the onset of RMDs. Use this low-income window to clear out pre-tax balances incrementally.
- Consult Professionals: Because tax laws, state-level variations, and Medicare brackets are intensely personal, engaging a fiduciary financial planner or certified public accountant to map out a multi-year withdrawal sequence is essential.
Ultimately, keeping your financial feet dry does not require an inherited fortune or millions in liquid cash. By making small, deliberate adjustments—filling low tax brackets, utilizing gap years, and sequencing withdrawals thoughtfully—everyday savers can protect their hard-earned nest eggs from premature erosion and ensure predictable, stable income for decades to come.
Disclaimer: This article is for educational purposes only and does not cover state income tax laws. The content does not constitute financial, legal, or tax advice.