The 2027 Rental Gold Rush: Why Institutional Shifts are Creating Unprecedented Opportunities for Individual Investors
In the current real estate landscape of 2027, a narrative of hesitation has taken hold. As interest rates remain elevated compared to the historic lows of the early 2020s, many prospective investors have retreated to the sidelines, waiting for a market "correction" that may never arrive in the form they expect. However, according to real estate veteran and Rent to Retirement CEO Zach LeMaster, this collective hesitation is exactly what is creating the most significant wealth-building window in recent memory.
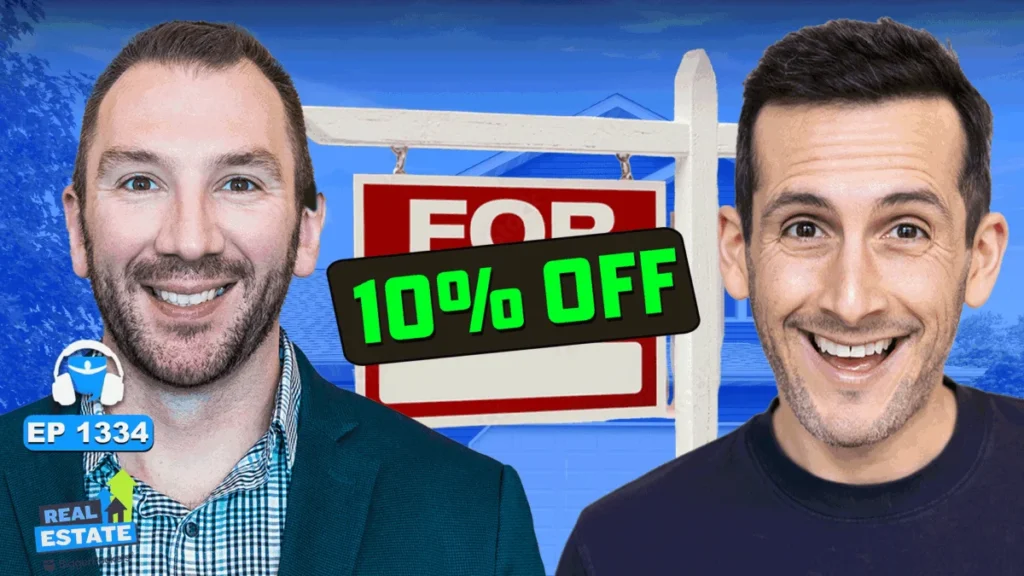
For the savvy investor, the current environment is not a deterrent—it is a filter. By moving away from the "herd mentality" and leveraging the specific pressures currently faced by national homebuilders, individual investors are now securing discounts of 10% to 15% on new construction properties—deals that were previously reserved for institutional conglomerates.
The Evolution of an Investor: From Military Optometry to Real Estate Mastery
To understand the strategy, one must understand the architect behind it. Zach LeMaster’s journey into real estate did not begin in a boardroom, but in the sterile environment of an Air Force clinic. A former military optometrist, LeMaster utilized the VA loan program—a tool often underutilized by service members—to acquire his first property: a duplex in North Dakota.
"I didn’t have any money to put down early in my career, so that worked out," LeMaster explains. "I house-hacked it before I even knew the term existed."
Following his initial success, LeMaster faced the classic investor’s dilemma: the scarcity of capital and the desire for higher returns. His early foray into out-of-state investing in Chicago’s Southside proved to be a "hard-knock" education. Dealing with low-income housing authorities and the constant "death by a thousand paper cuts" of maintenance proved that simply buying property is not enough; one must have a system.
That failure became the bedrock for Rent to Retirement. By refining a process that prioritized turnkey operations, strong management teams, and growth-oriented markets, LeMaster transitioned from a full-time medical professional to a full-time real estate executive, proving that consistency in any market cycle is the ultimate hedge against volatility.
Chronology of a Strategy: Consistency Over Timing
LeMaster’s philosophy is rooted in the concept of dollar-cost averaging, applied to the housing market. Since 2013, he has purchased rental properties every single year—through high rates, low rates, and market uncertainty.
The Foundation Years (2013–2018)
During this period, LeMaster learned the limitations of local investing. He realized that for a busy professional, the "pride of ownership" that comes with managing one’s own properties is often a liability. He shifted his focus to out-of-state markets, learning that building a robust team is more important than the ability to physically drive by a property.
The Optimization Phase (2019–2024)
As his portfolio grew, the focus shifted from simple cash flow to tax efficiency. LeMaster began utilizing advanced strategies like cost segregation studies, 1031 exchanges, and Opportunity Zones. He learned that while cash flow is the "tangible" goal for beginners, true wealth is generated through the interplay of leverage, appreciation, and tax-deferred growth.
The Current Opportunity (2025–2027)
In the current, more challenging interest rate environment, LeMaster has pivoted toward new construction. He argues that builders today are under immense pressure to clear their balance sheets, and they are willing to offer incentives that individual investors can capitalize on.
Supporting Data: Why Builders are the "New" Motivated Seller
The current opportunity in the market is driven by a unique confluence of factors: high inventory for builders, political pressure on institutional investors, and a cooling of the "frenzy" that characterized 2021-2022.
- The 10% Baseline: LeMaster asserts that any investor buying new construction in the Southeast—specifically in growth markets in Alabama, Georgia, the Carolinas, and Florida—should be negotiating a minimum of 10% in concessions.
- Institutional Pullback: Increased regulatory scrutiny on large-scale REITs and institutional buyers (like Blackstone) has left builders with excess inventory. This creates a vacuum that individual investors are now stepping into.
- The "Sunbelt" Shift: About 80% of current high-growth activity is concentrated in the Sunbelt. These areas are characterized by population growth and a persistent housing shortage, providing a floor for property values.
Official Perspectives: The "New Normal" in Financing
During a recent discussion, Dave Meyer of BiggerPockets and LeMaster agreed that the term "high interest rates" is a misnomer. They characterize the current 6-7% range as a return to "normal" after a decade of artificially suppressed rates.
The Role of Creative Financing
To navigate these rates, investors are increasingly turning to:
- Builder-Paid Rate Buydowns: Instead of asking for a price reduction, savvy investors are asking the builder to buy down the interest rate, potentially securing a 3% or 4% rate for the life of the loan.
- DSCR (Debt Service Coverage Ratio) Loans: These loans focus on the property’s income potential rather than the borrower’s personal tax returns, allowing for faster scaling.
- Adjustable-Rate Mortgages (ARMs): While historically "taboo," LeMaster notes that 5, 7, or 10-year ARMs are becoming viable tools for investors who plan to refinance once rates stabilize or drop, providing immediate cash flow relief in the interim.
Implications: The Long-Term Investor’s Advantage
What does this mean for the person looking to start or expand their portfolio in 2027? It means the strategy must shift from "hunt for the unicorn" to "hunt for the process."
1. The Death of the "Handy" Investor
LeMaster warns against the common mistake of trying to do everything yourself. Unless you are a professional flipper, your time is better spent on "portfolio-level strategy." The most successful investors in 2027 are those who outsource maintenance, management, and renovations to experts, allowing them to scale across multiple states simultaneously.
2. The Power of Tax Efficiency
For those who feel their cash flow is being eaten by interest rates, the answer lies in the tax code. LeMaster highlights the "short-term rental loophole" and cost segregation as essential tools. By accelerating depreciation, an investor can often offset their active income—a move that effectively increases their "take-home" yield without needing a single dollar more in rent.
3. Resilience Through New Construction
New construction serves as a hedge against the "noise" of older properties. With builder warranties, lower maintenance costs, and the ability to attract higher-quality tenants, new homes in the Southeast offer a "set it and forget it" model that allows investors to focus on the next acquisition rather than the last repair.
Final Outlook: The 2027 Mandate
The overarching message from industry experts is clear: the window of opportunity is not found in the headlines, but in the negotiations. The builders who need to move inventory are not waiting for the "perfect" buyer; they are looking for the prepared buyer.
For those willing to study the fundamentals—identifying growth markets, negotiating concessions, and utilizing tax-advantageous financing—the next few years could be the most lucrative chapter of their investment careers. As LeMaster puts it, "Time is your biggest partner in real estate investing." By choosing to act now, while others are paralyzed by the fear of interest rate volatility, investors are effectively buying into the next decade of appreciation at a discounted entry point.
The 2027 rental property market is not a place for those looking for an easy, passive "get-rich-quick" scheme. It is, however, an exceptional environment for the disciplined investor who understands that wealth is not made when the market is easy—it is made when the market requires you to be smart.