The Great Housing Grind: Why the Market Correction Is Spreading and Deepening
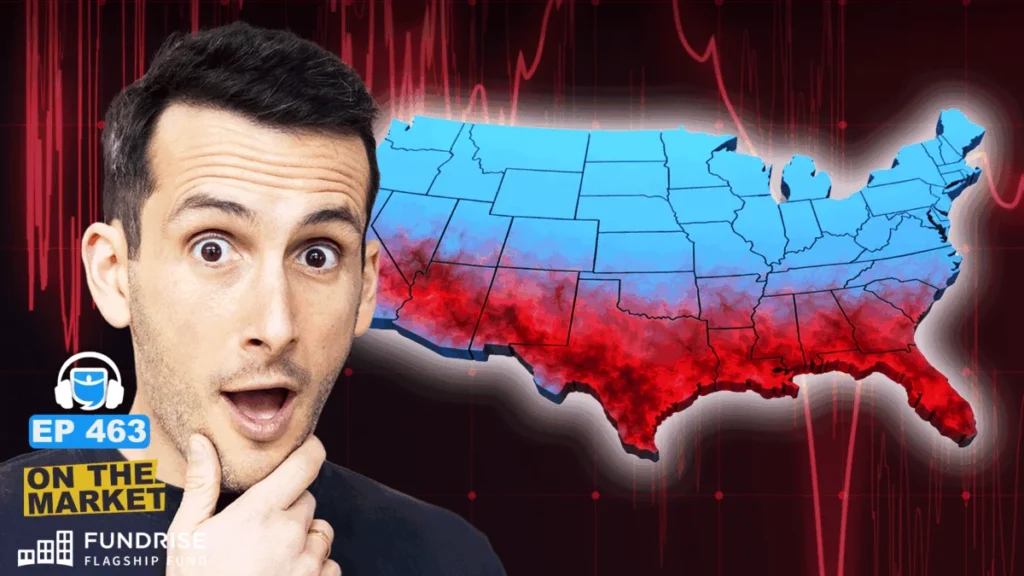
The American housing market is currently undergoing a structural shift that is proving to be far more complex than simple headlines suggest. For years, observers have debated whether the sector was headed for a catastrophic crash or a rapid "pop" back to affordability. According to Dave Meyer, Chief Investment Officer at BiggerPockets and host of the On the Market podcast, both narratives miss the mark. Instead, the data points to a persistent, grinding, and increasingly widespread housing correction—one that is no longer confined to the Sunbelt.
As the market enters a new phase, the insulation that once protected the Northeast and Midwest is eroding. With high mortgage rates, cooling demand, and shifting seller behavior, the housing sector is moving into a period of prolonged adjustment.
The State of the Correction: Beyond Nominal Prices
To understand the current market, one must distinguish between "nominal" and "real" home prices. On the surface, the median home price appears to be holding steady or inching upward. However, this figure is deceptive. When adjusted for inflation, home prices have been in a consistent decline for four years.
"Everything else going up, hopefully including wages, faster than home prices—that restores affordability," Meyer explains. "But if a property goes up one-and-a-half percent and everything else goes up three-and-a-half percent, your home price is not keeping up with inflation. That is a real, real decline."
According to data from the Case-Shiller index and the Calculated Risk Blog, inflation-adjusted home prices are currently approximately 4.8% below their 2022 peak. While this does not qualify as a "crash" by historical standards, the steady accumulation of these declines—averaging about 1.25% annually over four years—indicates a sustained, structural correction.
Chronology: From Sunbelt Struggles to National Trend
The narrative of the housing correction began in the Sunbelt. Markets like Austin, Texas, and various hubs in Florida saw significant price pullbacks early on, largely due to an oversupply of new construction and a rapid decline in demand after the COVID-19 pandemic.
For much of 2023 and early 2024, the Northeast and Midwest remained remarkably insulated, buoyed by lower inventory levels and relative stability. However, that divide is closing.
Recent data reveals a "rotation" in the market. While inventory in the South has begun to stabilize as sellers pull back from listing properties they cannot sell at their desired price, the correction is now gaining momentum in previously "safe" regions. Inventory in the Midwest is up 10% year-over-year, and the Northeast has seen a 9% increase. Metros like Detroit, Indianapolis, Baltimore, and Washington, D.C., which were previously performing well, are now showing clear signs of deceleration.
Supporting Data: The Hidden Reality of Concessions
The most critical factor obfuscating the true state of the market is the prevalence of seller concessions. In many cases, the price on a contract is not the price the buyer actually pays. Instead, sellers are increasingly utilizing rate buydowns, cash-back-at-closing, and repair credits to entice buyers.
Current data from Redfin indicates that approximately 45% of homes sold now involve some form of seller concession. This represents a significant shift from the pandemic era, where concessions were virtually non-existent. In some markets, such as Nashville and Atlanta, the rate of concessions is as high as 73% and 76%, respectively.
Furthermore, 16% of listings are now seeing both a price cut and a concession, a clear indicator of seller motivation. In the new construction sector, the situation is even more pronounced: nearly two-thirds of new homes involve concessions, with builders—who typically avoid lowering base prices to protect their development comps—offering an average price reduction of 6%. When these factors are accounted for, the "nominal" gains reported in national headlines appear largely illusory.
Supply and Demand: The Mechanics of the Grind
The housing market remains trapped in a state of low-velocity exchange, driven by two primary forces: the "lock-in effect" and stagnant demand.
The Demand Side
Demand is currently being pressured by three distinct factors:
- Mortgage Rates: Elevated rates remain the primary inhibitor, keeping buyers on the sidelines and making homeownership unaffordable for a large segment of the population.
- Macroeconomic Uncertainty: Concerns over job security—particularly in the tech and white-collar sectors—have led many potential buyers to adopt a wait-and-see approach.
- Inflation: Persistent inflation in non-housing costs has reduced the discretionary income that households might otherwise put toward a down payment or mortgage service.
Purchase applications, as tracked by the Mortgage Bankers Association, have plummeted to roughly half of their long-term average, and pending home sales have hit their lowest point in three years.
The Supply Side
While the "lock-in effect" remains strong—with roughly 50% of homeowners holding mortgages below 4%—inventory is slowly rising. Existing inventory recently surpassed 1.6 million units for the first time since 2019. More importantly, the rate of de-listings has dropped by 13% year-over-year. This suggests that sellers who previously would have pulled their homes off the market rather than lower their prices are now capitulating to the new reality, resulting in an increase in active, motivated listings.
Official Perspectives and Market Implications
The industry consensus, often characterized by "rosy real estate boosterism," continues to suggest that relief is just around the corner. However, evidence suggests otherwise. Real wage growth remains negative, and there is no clear catalyst for a significant drop in interest rates in the short term.
For investors, the implications of this environment are clear: discipline is the only path to success.
Strategic Recommendations:
- Ignore Market Appreciation: Investors should underwrite deals based on current cash flow and value-add potential, assuming zero market-wide appreciation for the next 12 to 24 months.
- Aggressive Negotiation: In a market where nearly half of all deals involve concessions, buyers should not hesitate to demand them. If a seller is unwilling to offer a concession or lower the price to 10–15% below current comps, the best move is often to walk away.
- The "Value-Add" Play: Because market-wide appreciation is unlikely, the only way to manufacture equity is through forced appreciation—renovations, operational improvements, or purchasing assets significantly below market value.
- Monitor Labor Data: The true "black swan" risk to this correction is a dramatic shift in the unemployment rate. Should the U.S. economy experience significant job losses, the "correction" could escalate into a more severe decline. As long as unemployment remains relatively stable, the market is likely to continue its current, painful grind.
Conclusion: Navigating the New Normal
The housing market is not currently on the verge of a 2008-style collapse, but it is undoubtedly in a period of extended weakness. The "safe" havens of the Northeast and Midwest are catching up to the realities faced by the Sunbelt, and the correction is becoming more widespread by the day.
For the average homeowner or investor, this is a time for caution. The era of easy, speculative gains is over, replaced by a market that rewards those who are patient, analytical, and uncompromising in their investment criteria. While the prospect of a prolonged correction may be daunting, it also provides a unique opening for those who have the capital and the discipline to capitalize on motivated sellers and negotiate from a position of strength. The market is not crashing, but it is changing—and those who refuse to adapt to the new equilibrium do so at their own peril.