Navigating the Expat Financial Crossroads: A Case Study in Planning for an Uncertain Future
For many, the expatriate experience represents the pinnacle of personal and professional freedom. It is a chance to reset, explore new cultures, and enjoy a lower cost of living while building a unique life abroad. However, beneath the veneer of international travel and local immersion lies a complex web of long-term financial uncertainty.

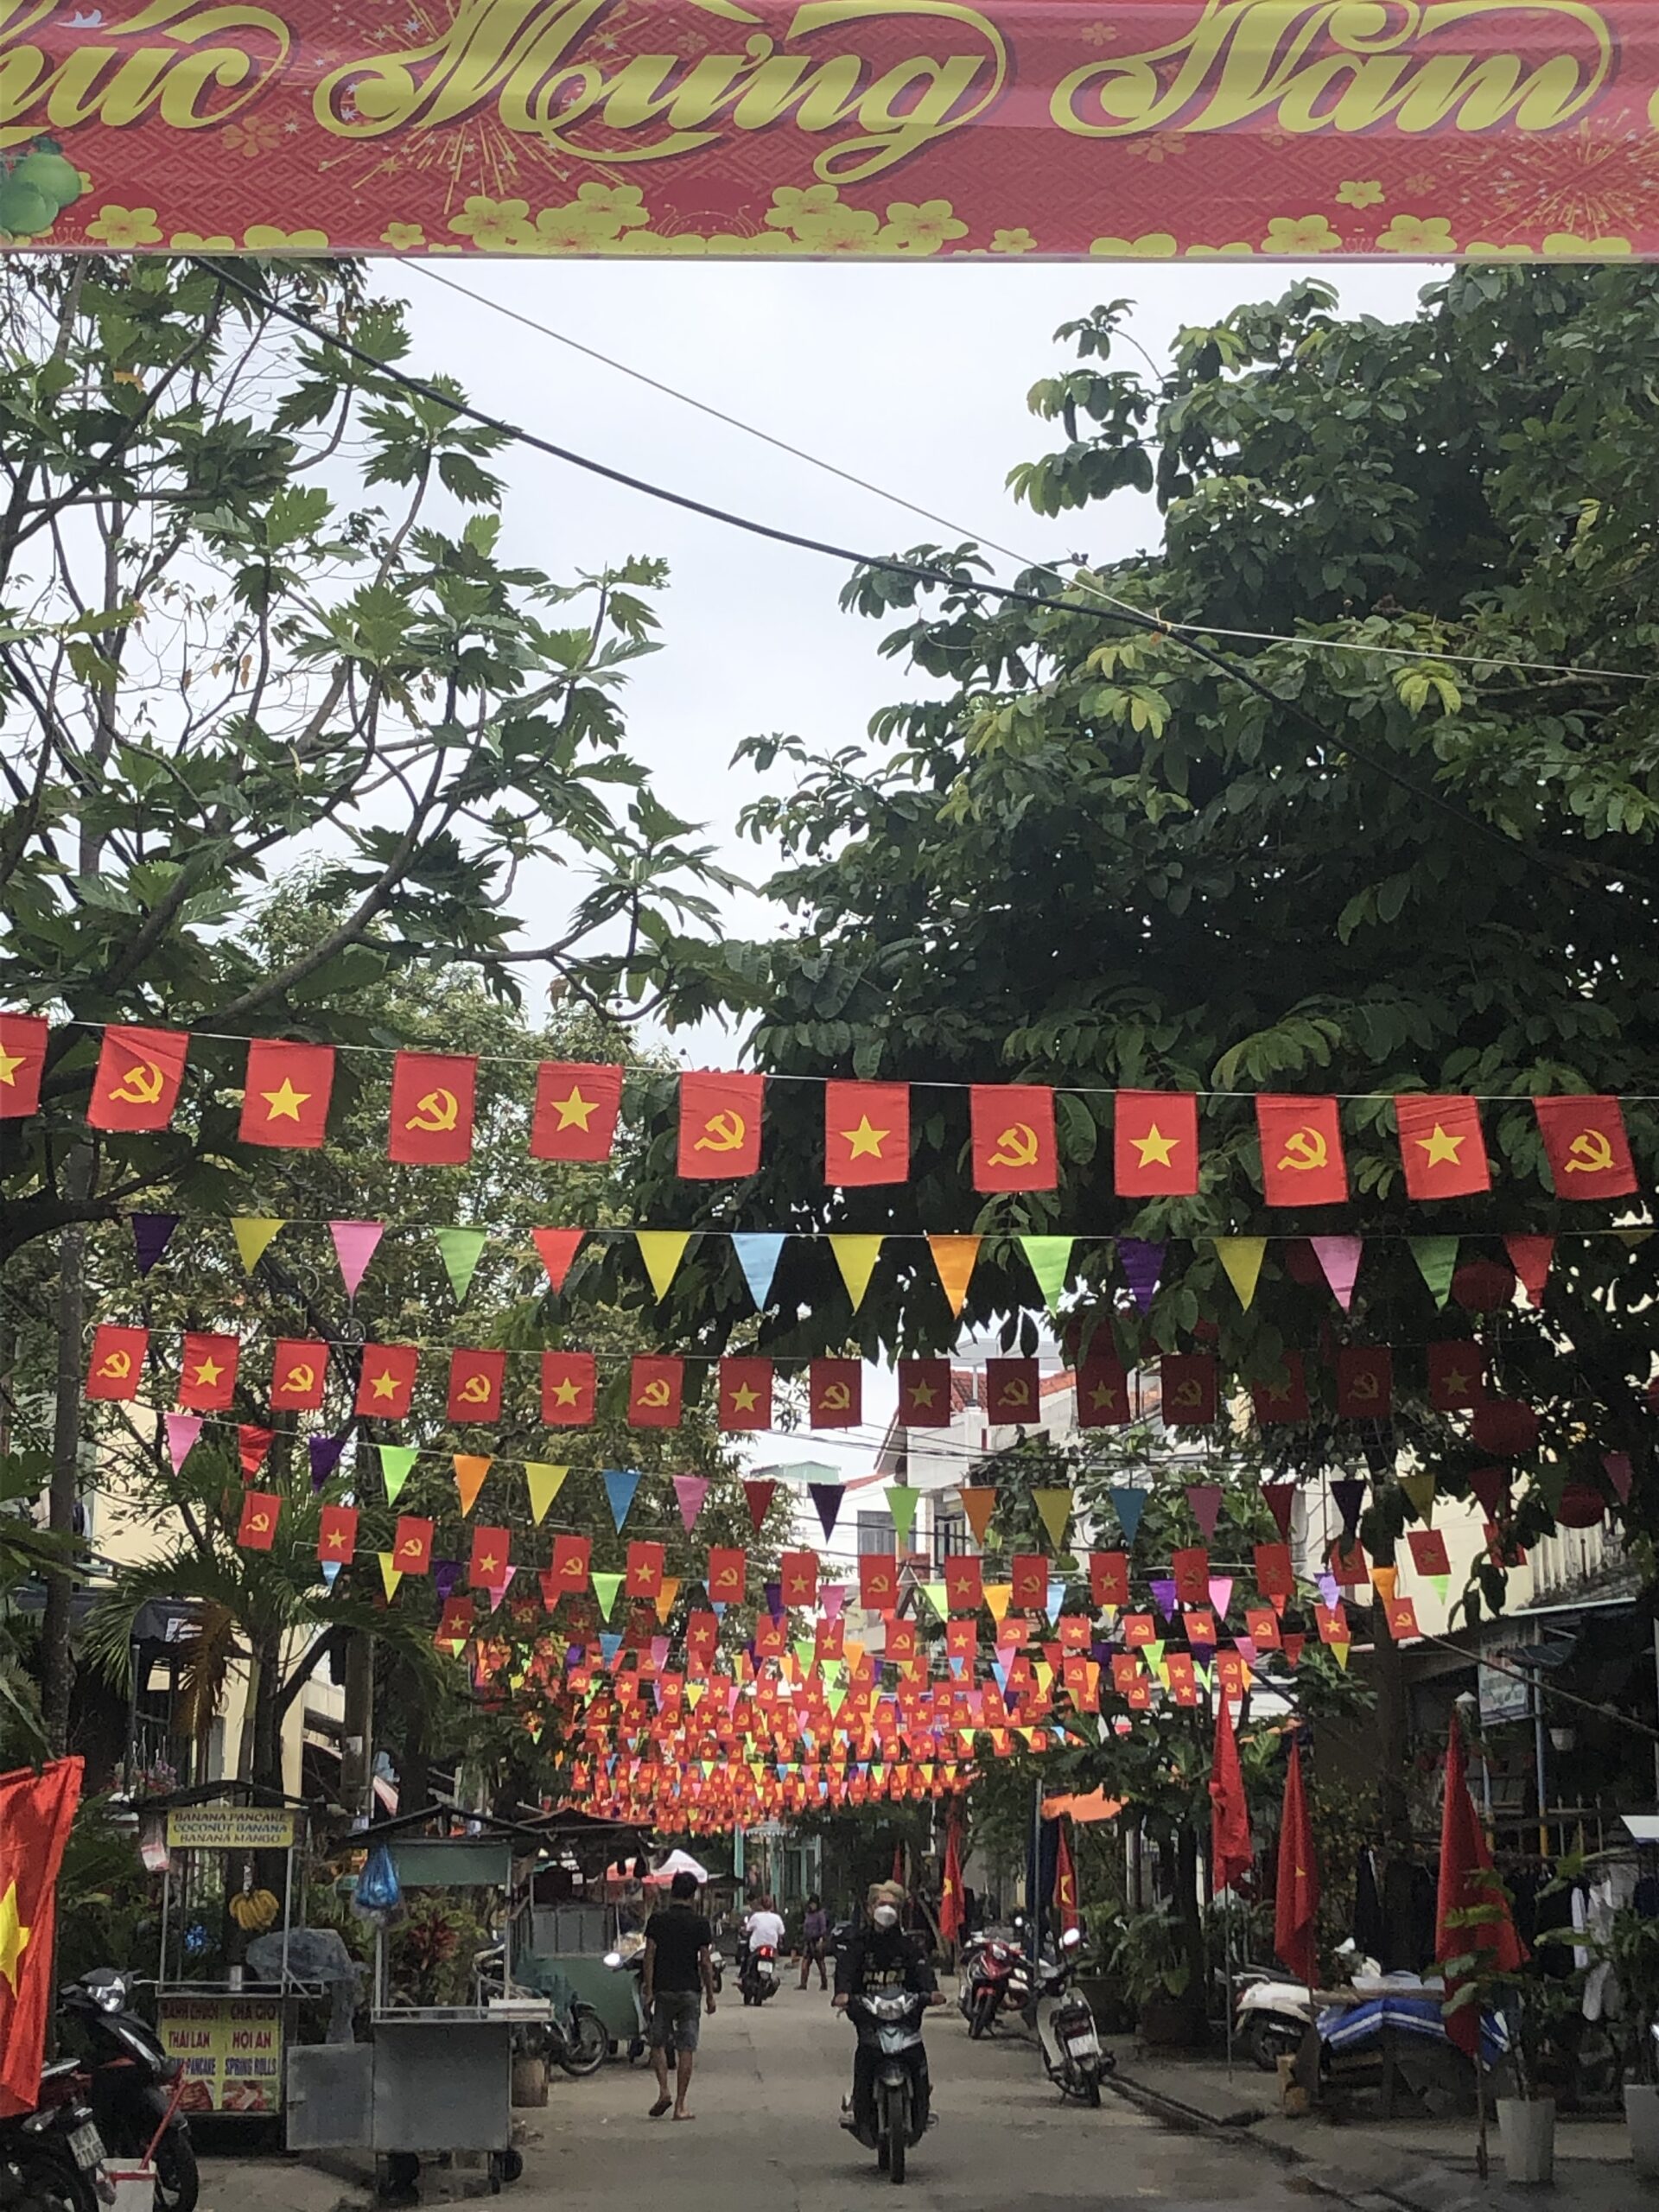
Laura, 32, and her husband Ethan, 38, are currently living this dual reality. Having relocated from Philadelphia to Hanoi, Vietnam, two years ago, the couple has leveraged the benefits of an international school salary and a significantly lower cost of living to pay down debt and invest in their personal passions. Yet, as they look toward an eventual return to the United States, they find themselves grappling with the anxiety of the unknown.
The Current Landscape: A Life in Transition
Laura and Ethan’s current lifestyle in Hanoi is marked by professional growth and financial stability. Ethan, a teacher at an international school, enjoys a compensation package that covers housing and flights, while Laura, a former software engineer, is currently pursuing a Master’s degree in Public Health.

Despite their current comfort, the pair is at a critical juncture. They have reached a point where they are debt-free, having aggressively paid off $140,000 in student loans over the last five years. However, their transition back to the U.S.—whenever that may be—looms large. They are worried about the high costs of American real estate, the burden of potential mortgages, and the feeling that their retirement savings have stalled during their time overseas.

Chronology of Their Financial Journey
The couple’s path to financial wellness has been deliberate and intense:

- The Early Years: Shortly after meeting, the couple prioritized debt eradication. Ethan cleared $80,000 in student loans, followed by Laura, who paid off $60,000 within 11 months.
- The Transition Abroad: Two years ago, they moved to Hanoi for Ethan’s teaching position. This shift allowed them to dramatically reduce their monthly expenses to approximately $1,741.
- The Education Phase: During the past year, both pursued advanced education. Ethan completed an accelerated Master’s in Education, while Laura began her Master’s in Public Health.
- The Present: They are now in a "holding pattern," living primarily on cash savings, while Laura focuses on her studies. They possess a net worth of over $235,000, yet feel a persistent, gnawing anxiety about their lack of a long-term roadmap.
Supporting Financial Data
The couple’s financial picture is one of high liquidity and low overhead, which serves them well in Vietnam but leaves them vulnerable to inflation and future market shifts.

Assets Overview
- Cash Savings: Their primary house-savings vehicle, a high-yield savings account, holds $76,500. Combined with other cash holdings, they have over $104,000 in liquid capital.
- Retirement Holdings: They have accumulated approximately $112,555 across various accounts, including a 401k, 403b, and a state teacher’s pension (PSERS).
- Investments: A taxable brokerage account holds $18,783, though the couple admits to being unfamiliar with the specific securities held within the account.
Monthly Expenses
Living in Hanoi has provided a masterclass in frugal living. Their monthly subtotal is just $1,741. Key highlights include:

- Groceries: $250/month (including alcohol and household goods).
- Transportation: $60/month (motorbike maintenance and fuel).
- Rent: $0 (covered by Ethan’s employer).
Expert Analysis and Strategic Recommendations
Financial consultant Liz Thames (Mrs. Frugalwoods) notes that while Laura and Ethan feel "behind," they are actually in a strong position. The primary challenge is not a lack of resources, but a lack of a clear strategy for when they return to the States.

The Case Against Buying a Home in Cash
Laura’s question regarding whether to pay for a future home in cash is a common one for those who are debt-averse. However, the recommendation is clear: do not pay cash for a home unless your wealth is infinite.

Paying cash creates a significant "opportunity cost." If the couple takes the $76,500 (and future savings) and invests it in a diversified index fund, they are likely to see historical returns that far outpace the interest saved by avoiding a mortgage. Furthermore, a home is an "illiquid asset." If an emergency arises, one cannot easily pull cash out of a home’s walls to pay for medical bills or unemployment expenses.

Retirement Contributions for Expats
The question of whether expats can contribute to IRAs while abroad is nuanced. It hinges on the "Foreign Earned Income Exclusion" (FEIE). If they exclude all their income, they cannot contribute to an IRA. They must ensure they have "taxable" income remaining after deductions to be eligible. The recommendation is to consult a tax professional specializing in expat filing to see if they can utilize the Foreign Tax Credit (FTC) instead, which might keep more doors open for retirement contributions.

Optimizing Investment Vehicles
The couple’s current investment portfolio is fragmented across multiple accounts from former employers. The suggested roadmap includes:

- Rollover: Consolidate old 401k and 403b accounts into a single IRA. This grants them control over the investment choices and fee structures.
- Asset Allocation: Move away from high-fee funds and toward low-cost, total-market index funds (e.g., VTSAX or equivalent).
- Expense Ratios: Conduct an audit of current investment holdings to ensure they are not losing significant percentages to management fees.
Implications for the Future
The path forward for Laura and Ethan is less about making a single "correct" decision and more about managing the psychological transition back to a high-cost environment.

Mitigating Anxiety
Laura’s anxiety is a symptom of living in a state of flux. To mitigate this:

- Automate Savings: Once they return to the U.S. and resume full-time employment, the priority should be setting up automated contributions to retirement and long-term investment accounts immediately upon receiving their first paychecks.
- Avoid "Cash-Hoarding" Long-Term: While cash is king during their current transition, it is not a growth vehicle. As their plans solidify, they must transition from a "saving for a house" mindset to a "building long-term wealth" mindset.
- Accept the Unknown: The couple must recognize that it is impossible to plan for every variable—housing costs, child-rearing, and market conditions. By maintaining their frugal habits, they are building a safety net that will support them regardless of the specific outcome.
Ultimately, Laura and Ethan are not falling behind. They are in a period of intentional investment in their education and their future. By consolidating their accounts, understanding the mechanics of their retirement options, and resisting the urge to tie up all their capital in a single real estate asset, they will be well-equipped to handle the challenges of their inevitable transition home.