Navigating Love and Ledger: The Complete Guide to Financial Planning for Late-In-Life Romances
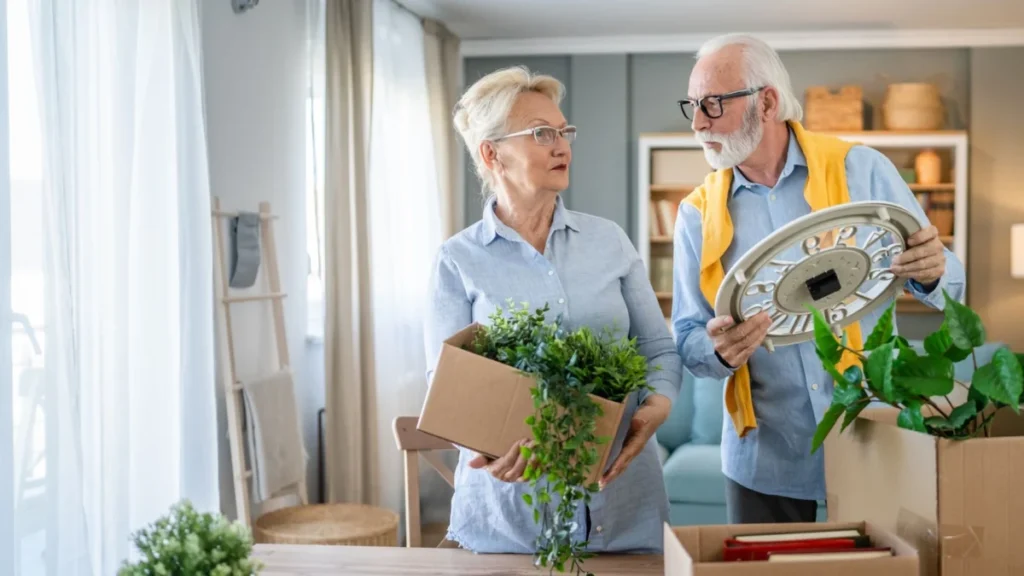
Finding love later in life is often depicted in popular culture as a peaceful, straightforward chapter. After decades of career-building, raising children, and navigating the unpredictable twists of life, discovering a companion to share your golden years can bring a profound, renewed sense of possibility.
However, the reality of merging lives in your 50s, 60s, 70s, or beyond is rarely simple. Modern late-in-life romance rarely happens in a financial vacuum. Instead, it collides with a complex web of pre-existing assets and obligations: real estate holdings, retirement accounts, complex trusts, active business interests, adult children, and legacy estate plans.
According to demographic data from the U.S. Census Bureau, the average age of widowhood in the United States is just 59. Meanwhile, a widely cited longitudinal study reveals that divorce rates among adults aged 50 and older—a phenomenon frequently termed "gray divorce"—have more than doubled over the past 30 years, currently accounting for nearly 35% of all total divorces nationwide. Concurrently, the number of adults between the ages of 40 and 59 marrying for the very first time has more than quadrupled.
The result of these shifting demographic trends is an unprecedented surge in older adults entering, or re-entering, the dating and partnership market. Yet, the way couples choose to formalize these relationships is evolving just as rapidly.
1. The Rise of "Gray Cohabitation" and Its Hidden Risks
For those who decide to formally couple up later in life, a growing number are opting to cohabitate—either as a precursor to marriage or as a permanent alternative to it.
Data from the National Center for Family & Marriage Research illustrates a dramatic culture shift. In the year 2000, fewer than 1 million adults aged 50 and older lived with an unmarried partner. By 2022, that figure skyrocketed to approximately 4.6 million—representing a nearly fivefold increase in just over two decades.
While living together offers companionship without the legal hurdles of a traditional marriage, it does not eliminate financial risk. In many ways, cohabitating without a legal framework can amplify financial vulnerability, because fewer automatic legal protections apply to unmarried partners, and those protections vary wildly from state to state.
The Legal Vulnerability of Unmarried Couples
Married couples benefit extensively from domestic relations and family law, which govern statutory rules regarding asset division, spousal support, and inheritance rights if a relationship terminates or a spouse dies.
Unmarried couples, conversely, generally receive only the protections they explicitly put into writing.
- The Real Estate Trap: If you move into a home owned entirely by your partner, contribute your personal funds toward extensive renovations, or commingle day-to-day living expenses without a formal agreement, you could walk away with little—or absolute nothing—if the relationship dissolves.
- The Death of a Partner: If your unmarried partner passes away without naming you in a valid will, trust, or beneficiary designation, you typically possess zero legal claim to their estate. Adult children or other biological relatives can legally inherit the home you shared, leaving a surviving partner unhoused and financially devastated.
Whether you choose a traditional marriage, a civil union, or long-term cohabitation, taking proactive, deliberate steps to protect each other financially is vital to building a stable, enduring partnership.
2. Chronology of a Modern Partnership: From Dating to Legacy Planning
Integrating two fully established adult lives requires patience and a structured approach. Financial planners and estate attorneys generally recommend a chronological roadmap for couples moving toward a serious commitment:
Phase One: The Conversational Foundation (Dating to Exclusive Commitment)
Before moving in together or discussing marriage, couples must move past surface-level romance into financial transparency. This phase is about peeling back the layers of individual financial histories. It requires sitting down to review complete balance sheets, understanding current income streams, and identifying obligations to ex-spouses (such as alimony or child support) or adult children.
Phase Two: The Operational Structure (Cohabitation or Pre-Engagement)
Once a couple decides to share a roof or pool resources, informal understandings are no longer sufficient. This is the critical juncture for drafting cohabitation agreements, establishing joint operational accounts for shared household expenses while keeping legacy assets separate, and mapping out potential worst-case scenarios.
Phase Three: Formalization and Legal Binding (Marriage or Long-Term Settlement)
For those marrying, this phase involves prenuptial agreements. For those cohabitating, it involves comprehensive estate planning, updating beneficiary designations on retirement accounts and life insurance policies, executing powers of attorney, and establishing healthcare directives.
Phase Four: Ongoing Review and Maintenance
Because late-in-life relationships often involve dynamic family structures—such as aging parents, newly born grandchildren, or shifting business ventures—couples must review their financial and legal alignment annually or following major life events.
3. Uncovering the "Money Story"
It is virtually impossible to protect one another financially until you fully comprehend what each partner brings to the table, both in terms of tangible assets and psychological baggage.
Taking Full Stock of the Balance Sheet
Partners should exchange a comprehensive snapshot of their financial health, including:
- Current net worth calculations
- Present and future retirement income sources (Social Security, pensions, annuities)
- Outstanding debts, mortgages, and liabilities
- Legal obligations stemming from previous divorces or child-rearing
- Ownership stakes in private businesses or partnerships
- Real estate holdings and geographic liabilities
- Existing estate plans, wills, and trusts
Beyond the Numbers: The Psychological Money Script
However, compiling a balance sheet is only half the battle. Couples must also discuss how their wealth was originally accumulated and what emotional hurdles shaped their financial journeys. These details comprise your "money story"—deeply ingrained behavioral patterns, anxieties, and triggers regarding money.
Consider two common scenarios:
- The Guarded Inheritor: One partner may have inherited substantial wealth following a bitter, contentious family estate dispute. Consequently, they may be deeply protective, private, and guarded about financial transparency.
- The Trauma of Gray Divorce: The other partner may have navigated a painful gray divorce where marital assets were weaponized during legal proceedings, leaving them deeply anxious about the prospect of merging bank accounts or signing financial documents.
Understanding these historical narratives—far beyond the raw numbers on a spreadsheet—allows both partners to approach financial discussions with empathy, patience, and reduced defensiveness. Recognizing the root cause of a partner’s financial anxiety transforms a tense negotiation into an act of mutual care.
4. Agreeing on Priorities and Contingencies
Just as each partner brings a distinct financial history, they also bring unique priorities, fears, and long-term goals.
In a late-in-life romance, these priorities can sometimes appear to clash:
- One partner may be hyper-focused on bridging a significant wealth disparity between the two households.
- The other partner may be primarily concerned with preserving generational wealth and inheritance rights for their biological children while simultaneously trying to fund a shared retirement and travel lifestyle.
- A partner who has relocated into their significant other’s home may quietly wonder: What happens to me if they pass away first? How do we fairly divide property taxes, maintenance costs, and daily living expenses?
Confronting "What If" Scenarios
Transparent communication is the bedrock of resolving these tensions. Couples should actively walk through hypothetical scenarios together long before an emergency strikes:
- What occurs if one partner requires long-term care or assisted living facilities?
- How will adult children from previous marriages be treated in the event of death or incapacity?
- If we separate, how are improvements made to a individually owned home handled?
Addressing these uncomfortable "what if" scenarios proactively helps align expectations, minimize future family conflict, and craft a bespoke plan that honors the needs of both partners and their broader families.
5. Formalizing the Plan: Legal Instruments and Structures
Good intentions and verbal promises are entirely insufficient when modern family dynamics become legally complex. If you want your final wishes honored and your chosen partner protected, you must rely on legally binding documents. Furthermore, there is no universal template; the ideal strategy depends entirely on your specific circumstances.
Key Legal Tools for Late-in-Life Couples
- Cohabitation Agreements: For unmarried couples sharing a roof, this contract outlines property rights, financial contributions, debt responsibilities, and how assets will be split if the relationship ends. Crucially, it can establish whether a surviving partner has the right to remain in a home owned by the deceased partner.
- Prenuptial and Postnuptial Agreements: For couples marrying later in life, these agreements protect pre-existing assets, clarify inheritance rights for adult children, and streamline potential legal proceedings, protecting both parties from unforeseen financial liability.
- Wills and Living Trusts: Trusts—particularly QTIP (Qualified Terminable Interest Property) trusts—are immensely popular in blended families. They allow a surviving spouse to receive income or use of an asset (such as a home) for the remainder of their life, while legally guaranteeing that the underlying principal eventually passes to the deceased partner’s biological children.
- Beneficiary Designations: Retirement accounts (IRAs, 401(k)s) and life insurance policies pass independently of a will. Keeping these designations up to date is vital to ensure your intended partner is actually the recipient of these funds.
- Financial and Medical Powers of Attorney: In the event of sudden incapacitation, a partner without legal power of attorney may be barred from making medical decisions or managing financial affairs, leaving total control in the hands of biological relatives who may be hostile to the relationship.
Building the right structure requires more than simply checking boxes on an internet legal form. It requires partnering with a collaborative team of professionals, including an estate planning attorney, a certified public accountant (CPA), and a qualified financial advisor.
6. Implications: Viewing Transparency as an Act of Love
The ultimate takeaway for older adults navigating new love is simple: The goal of financial planning is never to protect yourself from your partner; it is to protect your relationship with your partner.
By removing ambiguity, couples can ensure that the life they are building together—regardless of whether it features a marriage certificate or a cohabitation lease—is anchored in clarity rather than dangerous assumptions.
The couples who navigate late-in-life romances most successfully are rarely those with the simplest family trees or perfectly matched net worths. Rather, they are the individuals who possess the courage to have uncomfortable conversations early, implement robust legal safeguards, and view complete financial transparency not as a sign of distrust, but as one of the highest expressions of mutual love and commitment.
Disclaimer: This article is designed for informational purposes only and does not constitute formal legal, tax, or financial advice. Readers should consult with licensed professionals, such as estate planning attorneys or certified financial planners, regarding their specific personal situations. Adviser records can be independently verified via the SEC (adviserinfo.sec.gov) or FINRA (brokercheck.finra.org).