Rebuilding Trust: Inside Carlos Iafigliola’s Strategic Overhaul of Amerant Bancorp
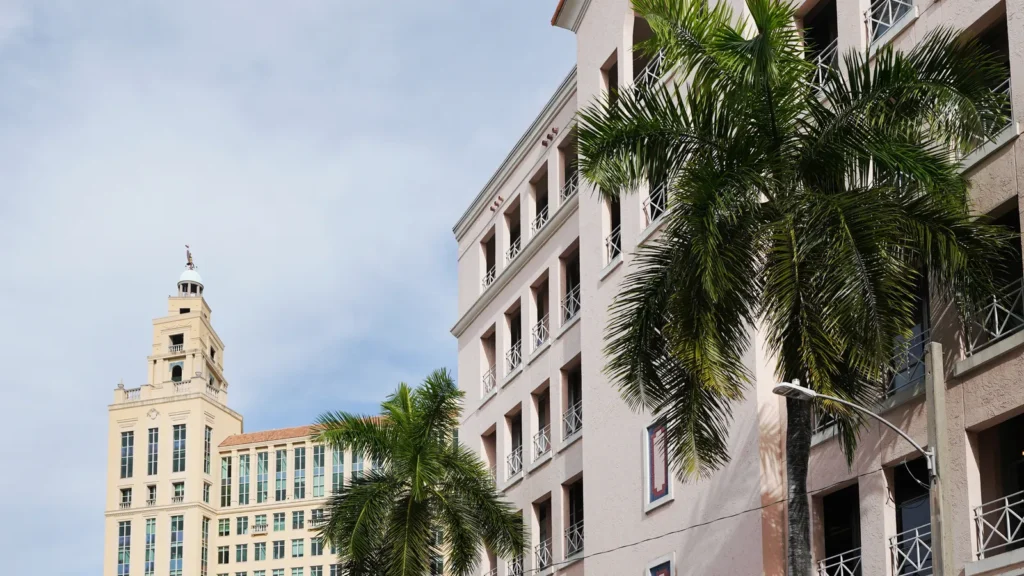
The financial landscape in South Florida is notoriously competitive, characterized by a mix of massive national players and nimble, community-focused institutions. For the $10.3 billion-asset Amerant Bancorp, the last eighteen months have been a period of intense introspection, structural reorganization, and a fundamental shift in risk appetite. Since taking the helm as President and CEO in May 2026—following an interim stint—Carlos Iafigliola has been the architect of a comprehensive credit turnaround designed to restore institutional credibility and stabilize the bank’s balance sheet.
The Catalyst for Change: A Tumultuous Transition
The seeds of the current transformation were sown during a period of significant volatility in late 2025. Following the abrupt departure of former CEO Jerry Plush, the Coral Gables-based bank found itself under scrutiny from analysts and investors alike. The friction point was clear: a deteriorating loan portfolio that signaled potential vulnerabilities in Amerant’s commercial real estate (CRE) and broader commercial lending segments.
The instability became public when Amerant reported its third-quarter 2025 earnings. Nonperforming assets (NPAs) had surged to $140 million, up from $98 million just a quarter prior. The market reaction was swift, with Piper Sandler analyst Stephen Scouten noting that the rise in problem assets had “put pressure on management credibility.” The transition period was costly, with the bank logging $3.8 million in separation expenses tied to the executive change. For Iafigliola, the task was twofold: manage the immediate fallout of the executive transition while executing a deep-tissue diagnostic of the bank’s entire asset base.
A Chronology of the Turnaround
The overhaul did not happen overnight; it was a methodical, phase-driven process that began in the final months of 2025 and continues to evolve today.
Phase 1: The Diagnostic (Q4 2025)
Upon stepping into the leadership role, Iafigliola prioritized transparency. The bank initiated a rigorous, third-party review of its loan portfolio. According to Iafigliola, the mandate was to analyze "every single loan." This exhaustive audit served as the bedrock for the bank’s subsequent strategy, allowing management to identify toxic exposures and initiate a process of "risk recalibration."
Phase 2: Structural and Personnel Realignment (Late 2025 – Q1 2026)
Recognizing that culture is as critical as policy, Iafigliola oversaw the appointment of Lee Ann Cragg as Chief Credit Officer. Under her guidance, the bank began the arduous process of overhauling internal credit systems, updating policies, and refining the underwriting procedures that had previously allowed risk to accumulate. This period also saw the bank simplify its operational structure, narrowing its focus to two primary business lines: domestic and international banking.
Phase 3: Progressive Stabilization (Q2 2026 – Present)
By the second quarter of 2026, the fruits of this labor began to appear. While NPAs had peaked at roughly $187 million in Q4 2025—a direct consequence of the aggressive portfolio cleansing—they finally began a downward trend in Q2 2026, dipping to $186.6 million. More importantly, the NPA ratio as a percentage of total assets improved, moving from 1.93% in the first quarter to 1.81% in the second.
Analyzing the Data: A Tale of Two Markets
The bank’s financial trajectory in 2026 illustrates the complexity of balancing risk mitigation with growth. While Amerant successfully increased its gross loans by $112 million to $6.9 billion in Q2, this figure masks a more surgical strategy: the intentional exit from high-risk loan segments.
The bank’s deposit strategy also reflects a shift toward quality over quantity. While domestic deposits dipped by approximately 2% to $5.13 billion—largely due to the deliberate exit of a high-cost, large fund provider, as noted by CFO Sharymar Calderon Yepez—the international segment saw significant growth. Specifically, deposits from Venezuela grew by nearly $500 million, reaching $2.5 billion. Iafigliola characterizes these as "operating deposits tied to essential industries," suggesting a stable and mission-critical client base rather than volatile speculative capital.
Official Perspectives: The “Household Approach”
Central to Iafigliola’s vision is the concept of the “household approach.” He argues that many large national banks lose the ability to serve clients effectively because they compartmentalize commercial needs from wealth management.
“When you think about a business owner and their company, we are kind of a one-stop solution for them,” Iafigliola said in a recent interview. He contends that larger lenders suffer from a lack of internal coordination, where different silos fail to communicate, ultimately harming the client experience. By positioning Amerant as a centralized, relationship-focused bank, he aims to capture market share in South Florida, specifically targeting the professional services, logistics, and education sectors.
These sectors, particularly firms generating $50 million or less in annual revenue, are the “sweet spot” for Amerant. In these tiers, the bank can maintain a direct, intimate relationship with business owners, ensuring that credit decisions are made with a holistic view of the client’s financial life.
Strategic Implications: What Lies Ahead
Despite the progress, Iafigliola remains pragmatic. "There’s still more work to do," he acknowledges, noting that while the foundation is set, the bank must now focus on sustainable growth. The goal is to move from the "recalibration" phase into a period of proactive expansion, specifically within the domestic commercial segment.
The Competitive Landscape
The South Florida market is notoriously saturated. According to FDIC data as of June 2026, Amerant holds 2.36% of the deposit market share in the tri-county area of Miami-Dade, Broward, and Palm Beach, and 0.37% in Tampa’s Hillsborough County. To grow these numbers, the bank is betting that its new "credit culture" will serve as a competitive differentiator. By being more disciplined in its underwriting, the bank hopes to avoid the cyclical credit pitfalls that plagued its peers during the 2025 downturn.
Operational Culture
The shift in credit culture is perhaps the most difficult aspect of the transformation. Changing how a bank embraces risk is not just about changing software or policy manuals; it is about changing the mindset of the lending officers on the ground. Iafigliola believes that the bank is now successfully aligning its lending appetite with its internal risk tolerance, ensuring that future loan production is of higher quality.
Conclusion: A Bank in Transition
As Amerant Bancorp approaches its next earnings announcement on October 23, the industry will be watching closely to see if the downward trend in NPAs holds and if the commercial loan pipeline continues to show the "quality over quantity" growth that management has promised.
For Carlos Iafigliola, the past year has been a masterclass in crisis management and corporate restructuring. By excising risk, simplifying the bank’s structure, and doubling down on a relationship-based model, he has steered Amerant away from the precipice of a credit crisis. The bank is undoubtedly in a stronger position than it was in late 2025, but the challenge remains to prove that these changes are not merely a temporary reaction to bad news, but a sustainable model for long-term growth in one of the most dynamic banking markets in the United States.
The path forward, as Iafigliola puts it, is built on the established foundation of the last year. The question remains whether that foundation is deep enough to support the ambitious growth targets he has set for the firm’s commercial portfolio. As the bank prepares for its next chapter, the focus will remain on diligent execution and the continued, disciplined management of every single loan.