Fed Overhauls Stress Testing Framework: A Balancing Act Between Stability and Predictability
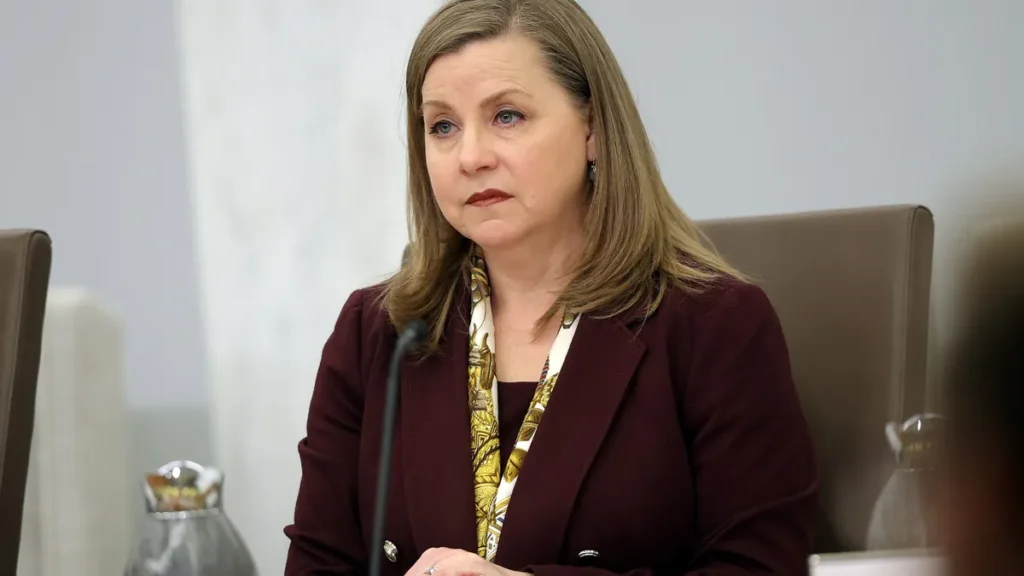
By Financial News Desk
Published September 30, 2026
In a move that marks a significant pivot in the Federal Reserve’s regulatory philosophy, the central bank finalized two landmark rules on Wednesday aimed at reshaping how the nation’s largest financial institutions are stress-tested. The updates, which have been under intense scrutiny since they were first proposed last October, are designed to introduce a higher degree of transparency into the Fed’s modeling process while simultaneously smoothing out the volatile swings in capital requirements that have long frustrated bank executives and investors alike.
The decision represents a major victory for industry advocates who have spent years lobbying for greater clarity in the Fed’s "black box" modeling, while simultaneously highlighting a widening ideological rift within the Board of Governors regarding the future of post-crisis financial oversight.
The Core Changes: Transparency and Stability
Under the new regulatory framework, the Federal Reserve has committed to a more collaborative approach regarding its stress-testing scenarios. The primary components of the rule changes are twofold:
- Public Scrutiny of Scenarios: The Fed will now be required to invite public comment on annual stress-test scenarios and any material changes to the underlying models. This is a departure from the previous regime, where the Fed’s methodology was largely opaque to the institutions it regulated.
- Dual-Shock Stress Testing: To ensure robustness, banks will be evaluated against two distinct global market shock components annually. The final capital requirement will be determined by the shock that generates the more significant loss, ensuring that the most conservative risk assessment governs the institution’s capital buffer.
- Smoothing Volatility: Perhaps the most significant change for bank balance sheets is the shift in how the Stress Capital Buffer (SCB) is calculated. Starting in 2028, the Fed will use a two-year rolling average of annual test results to determine the SCB. According to Fed estimates, this mechanism could reduce year-to-year volatility in capital requirements by as much as 50%.
Additionally, the central bank has issued a request for public comment on a proposed revision to how it measures noninterest income. This technical shift is aimed at better accounting for the diverse fee-income models utilized by modern financial institutions, with a 60-day window for feedback following its publication in the Federal Register.
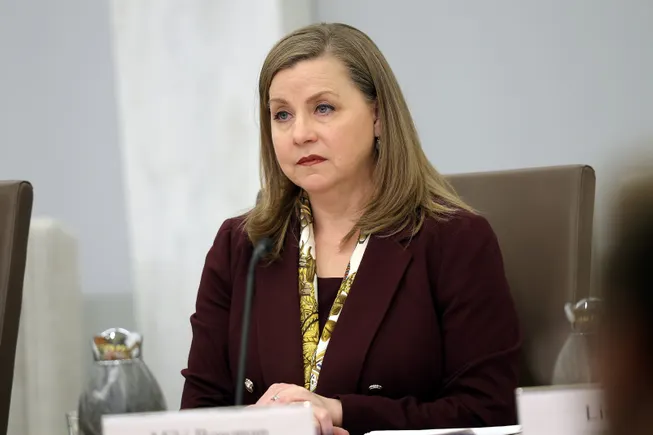
A Chronology of Conflict and Compromise
The journey to these finalized rules has been anything but smooth. The regulatory tension surrounding stress testing has been building since the post-2008 era, but it reached a boiling point in late 2024.
- December 2024: The Fed attempted to implement adjustments to its stress-testing methodology to address concerns regarding volatility. However, the move was met with immediate legal resistance. Trade groups, including the American Bankers Association (ABA) and the Bank Policy Institute (BPI), filed a lawsuit alleging that the Fed’s processes lacked the transparency and procedural rigor required by the Administrative Procedure Act.
- October 2025: Facing mounting pressure from the industry and the ongoing legal challenges, the Fed unveiled a new proposal that mirrored the transparency-focused reforms finally passed today.
- March 2026: Fed Vice Chair for Supervision Michelle Bowman signaled a shift in tone, emphasizing that the stress test—while essential—needed to be "transparent, granular, and risk-sensitive" to maintain its legitimacy.
- September 2026: Following months of discourse and industry feedback, the Board of Governors voted 6-1 to finalize the rules, formally codifying the new era of collaborative regulation.
Supporting Data and Technical Rationale
The rationale behind these changes is rooted in the "volatility problem." Under the old system, banks often faced unpredictable capital requirements that fluctuated significantly due to minor tweaks in the Fed’s proprietary models. This unpredictability hindered long-term capital planning, often forcing banks to hold excessive amounts of capital to guard against a sudden, model-driven "spike" in requirements.
By averaging the results over two years, the Fed aims to dampen the impact of idiosyncratic shocks or temporary model adjustments. The inclusion of two global market shock scenarios is intended to act as a safeguard, ensuring that even with the "smoothing" effect, banks remain sufficiently capitalized against the most extreme plausible market conditions.
The proposed revision to noninterest income measurement is equally technical. As banks shift away from traditional net interest margin models toward more diversified fee-based revenue streams, the old modeling frameworks had become increasingly inaccurate. By soliciting industry input, the Fed hopes to create a model that captures the nuances of modern financial services without sacrificing the "stress" element of the test.
The Ideological Divide: A 6-1 Split
The 6-1 vote in favor of the rules underscores a significant disagreement within the Fed’s leadership. While the majority, led by Michelle Bowman, views these changes as a necessary evolution for a mature regulatory system, the lone dissenter—former supervision czar Michael Barr—offered a sharp rebuke.

Barr argued that while transparency is a noble goal, it comes at a dangerous cost. "Disclosure of the stress test models and annual public comment processes on model changes and scenarios will make the stress tests less responsive to emerging risks," Barr stated.
He warned that the new process would lead to "calcified models," effectively allowing banks to "optimize their balance sheets to the test" rather than focusing on the actual underlying risks of their operations. For Barr, the rigor and conservatism of the stress test are its most valuable traits; by making the process more "dynamic" and open to public debate, he fears the Fed is diluting the very mechanism that keeps the financial system stable.
Implications for the Banking Industry
The reaction from the private sector has been overwhelmingly positive. The ABA and BPI, having been the primary catalysts for the legal challenges of 2024, hailed the final rules as a triumph for "better policy."
1. Capital Planning and Efficiency
For the banking sector, the primary benefit is predictability. With a two-year rolling average for the SCB, CFOs can engage in more sophisticated capital management, potentially freeing up capital for dividends, share buybacks, or lending. The industry argues that this is not a weakening of standards, but rather a move toward efficiency that will ultimately benefit the broader economy by lowering the cost of capital.
2. The End of the "Black Box" Era
The era of the Fed operating in a vacuum regarding model adjustments is effectively over. By opening the process to public comment, the Fed is essentially inviting the banking industry to act as a "peer reviewer" of its regulatory tools. While this will undoubtedly improve the accuracy of the models, it also invites the risk of "regulatory capture," where the regulated parties exert undue influence over the tools used to supervise them.

3. Future Legal Precedent
The path taken here—using the Administrative Procedure Act to force the Fed into a more transparent, comment-heavy process—sets a significant precedent. It suggests that major financial regulators may face increased procedural hurdles in the future. Agencies will now have to weigh the speed of regulatory implementation against the risk of protracted legal battles that could tie up rules in court for years.
Conclusion: A New Regulatory Normal
The Federal Reserve’s decision to finalize these rules is a acknowledgment that the post-2008 regulatory environment has reached a point of maturity where the focus must shift from pure "shock and awe" to sustainable, predictable oversight.
As Michelle Bowman noted in her remarks, the goal is to provide the public with "greater assurance" that risks are being monitored. However, as the dissent from Michael Barr highlights, the real test of this new framework will not be in the calm of a stable market, but in the next period of financial turbulence. If the "calcified models" fail to identify a new, emerging threat because they were too focused on satisfying public input or maintaining year-over-year smoothness, the Fed may find itself returning to a more aggressive, less transparent approach.
For now, the banking industry has gained the transparency it craved, and the Federal Reserve has traded a degree of unilateral control for a more collaborative—and potentially more stable—regulatory architecture. Whether this creates a more resilient system or merely a more predictable one remains the central question for the years to come.