General Motors Nears Finish Line on EV Restructuring, Bolstered by Strong Cash Flow and Decades-Strong Balance Sheet
DETROIT — General Motors is rapidly closing the chapter on a massive and costly pivot in its corporate strategy. According to statements made by Chief Financial Officer Paul Jacobson, the legacy automaker is entering the final stretch of its electric vehicle (EV) restructuring initiative. The sweeping overhaul, which began in earnest during the latter half of 2025, has required billions of dollars in charges to right-size production capacity and align the company’s manufacturing footprint with a shifting automotive market.
Despite an industry-wide cooling of consumer demand for brand-new battery-electric vehicles—a trend that has forced major competitors like Ford and Honda to scale back or outright scrap upcoming EV lineups—GM appears uniquely insulated. Backed by a transformed balance sheet that Jacobson describes as "arguably stronger than it’s been in decades," GM is leaning on rigorous capital allocation and a multi-year cash flow surge to weather economic headwinds, fund future innovations, and prepare for potential macroeconomic downturns.
Main Facts
The overarching narrative centers on General Motors successfully absorbing the financial blows of its EV restructuring while maintaining robust financial health. Key elements of the company’s current positioning include:
- Substantial Completion of Restructuring Costs: GM’s financial reports indicate that the material charges associated with right-sizing EV capacity are largely behind the company. The $2.3 billion in incremental restructuring charges recorded for the quarter ending June 30 substantially finalized the bulk of these expenses.
- Massive Cumulative Outlays: Since the second half of 2025, GM has logged a cumulative $10.9 billion in EV-related restructuring charges as it adjusted production targets and supply chains to meet shifting consumer adoption rates.
- Exceptional Free Cash Flow Generation: Over the past decade, GM has dramatically elevated its financial productivity. While the first half of the decade saw the company average roughly $3 billion in free cash flow, that figure has more than tripled to over $10 billion annually over the last five years.
- Confident 2026 Projections: For the full-year 2026, GM has projected its adjusted automotive free cash flow to range between $9.5 billion and $11.5 billion, underscoring resilient core operations despite a turbulent macroeconomic backdrop.
- The Industry Landscape: The broader automotive sector continues to grapple with decelerating retail demand for brand-new electric vehicles. According to recent data from Cox Automotive, new EV sales have faced severe year-over-year slumps, even as used EV transactions and alternative powertrain configurations gain traction among budget-conscious buyers.
Chronology of the EV Restructuring and Financial Turnaround
To understand how General Motors arrived at its current position of financial strength, it is necessary to examine the timeline of its strategic pivot and the evolution of its balance sheet over the past ten years.
The Foundation: A Decade of Capital Discipline (2016–2024)
When Paul Jacobson stepped into the role of GM Chief Financial Officer in 2020, the company was already executing a quiet transformation focused on portfolio optimization and disciplined capital deployment. Shedding unprofitable regional footprints, optimizing internal combustion engine (ICE) truck and SUV profitability, and laying the groundwork for a future software- and electrification-driven portfolio became the guiding pillars of management’s philosophy.
This multi-year effort steadily repaired GM’s credit profile and liquidity. By shifting the baseline of free cash flow from an average of $3 billion to more than $10 billion per year, the automaker built a formidable financial fortress capable of absorbing heavy capital expenditures.
The Pivot and Heavy Charges (Late 2025–Mid 2026)
As initial consumer adoption curves for premium-priced electric vehicles began to flatten across the United States, automakers were forced to reassess aggressive production targets. In the latter half of 2025, GM initiated a comprehensive restructuring of its EV manufacturing ecosystem to better match supply with actual market demand.
This restructuring did not come cheap. Over successive quarters, GM accumulated $10.9 billion in EV-related charges. This total included a $2.3 billion hit for the quarter ending June 30, which Jacobson highlighted as the milestone that "substantially completed" the material non-cash and cash charges expected for right-sizing capacity.
Current Operations and Future-Facing Investments (Mid-to-Late 2026)
By July 2026, during the release of the second-quarter earnings report, Jacobson was able to pivot the narrative from cost containment to operational execution. With the heavy lifting of the restructuring phase nearly complete, GM turned its attention toward ensuring that current capital investments are funneled into the vehicle architectures and battery technologies slated to hit showrooms over the next three to six years.
Supporting Data: Financial Metrics and Market Realities
GM’s sunny outlook stands in sharp contrast to a cautious broader automotive market, making the company’s underlying data critical to evaluating its strategy.
Free Cash Flow and Balance Sheet Strength
The cornerstone of GM’s defensive and offensive capabilities is its cash generation. The leap from a $3 billion average free cash flow in the early 2010s to a consistent $10+ billion run-rate over the last five years represents a structural shift in profitability.
For full-year 2026, management’s guidance anticipates adjusted automotive free cash flow between $9.5 billion and $11.5 billion. According to Jacobson, this performance allows the company to comfortably fund ongoing operations, return capital to shareholders, and invest heavily in next-generation product portfolios without compromising liquidity.
The Shifting EV Consumer Landscape
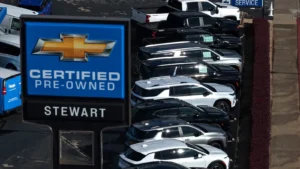
GM’s decision to right-size its EV capacity was heavily influenced by broader macroeconomic and consumer shifts. According to a September 15 report by Cox Automotive, consumer interest in electric vehicles has evolved, pivoting away from expensive new models toward used options and a wider diversity of brands.
- New EV Sales Performance: While new EV sales in August 2025/2026 experienced a minor 2.5% tick upward on a month-over-month basis (reaching an estimated 78,895 units), this figure still represents a staggering 47% contraction compared to the same period in the previous year.
- Used EV Market Surge: Conversely, the secondary market is thriving. Cox Automotive found that sales of pre-owned electric vehicles jumped by nearly 26% month-over-month and 14.7% year-over-year during the comparable tracking period, illustrating that affordability remains a primary driver for EV adoption.
Industry-Wide Retrenchment
GM is not alone in feeling the friction of the EV transition. Competitors have been forced to reevaluate capital allocation plans to protect their bottom lines. For instance, Honda Motor Co. booked significant financial hits due to hefty EV charges, while Ford Motor Company has repeatedly delayed, downsized, or canceled planned EV platforms in favor of hybrid and profitable internal combustion vehicle offerings. GM’s ability to absorb its $10.9 billion in restructuring charges without imperiling its credit rating highlights the distinct advantage of its legacy cash-cow segments—primarily full-size trucks and large SUVs.
Official Responses and Executive Insights
Addressing analysts and investors during recent earnings calls and financial updates, CFO Paul Jacobson emphasized that disciplined capital allocation has been the primary catalyst behind GM’s resilience.
"That discipline combined with the performance of the company has been a huge catalyst for us that we plug into our capital allocation philosophy," Jacobson remarked. He stressed that while cutting costs and right-sizing capacity were essential steps, management’s primary focus remains forward-looking: "Invest in the business because it’s critical that we’re already working on the vehicles that are going to be dazzling customers 3, 4, 5, 6 years and beyond."
Furthermore, Jacobson addressed the perennial concern of economic cyclicality and the threat of an impending recession. Highlighting robust cash flow as the ultimate corporate shield, he noted that maintaining positive free cash flow through a downturn is his ultimate benchmark for success.
"And while I’ve said I don’t wish for a recession, much like a final exam in college or university, you’re ready for it, right?" Jacobson quipped when responding to an analyst’s question regarding macroeconomic pressures and inflation. "Nobody wants to take the final, but you find a point at a time that you’re ready for it."
Implications for General Motors and the Automotive Industry
The conclusion of GM’s EV restructuring phase carries profound implications for both the company’s competitive standing and the wider automotive ecosystem.
1. Operational Agility in a Volatile Market
By ripping the Band-Aid off early and absorbing $10.9 billion in restructuring charges, GM has freed itself from the financial drag of over-projected EV production lines. The company is no longer forced into a binary choice between losing money on oversupplied electric vehicles or idling plants without a plan. Instead, its manufacturing footprint is now flexible, capable of pivoting between ICE, hybrid, and electric architectures depending on where consumer demand actually lands.
2. A Fortress Balance Sheet as a Competitive Moat
As borrowing costs remain elevated and inflation squeezes consumer discretionary spending, automakers require deep liquidity to survive downturns. GM’s projected $9.5 billion to $11.5 billion in free cash flow for 2026 gives it an enviable war chest. While weaker competitors may be forced to curtail research and development budgets or delay critical technological advancements, GM can comfortably fund its long-term roadmap.
3. Long-Term Product Competitiveness
Jacobson’s emphasis on "dazzling customers 3, 4, 5, 6 years and beyond" signals that GM views the current EV slowdown as a temporary speed bump rather than a permanent rejection of electrification. By maintaining heavy R&D investments during a period of market consolidation, GM aims to emerge with second- and third-generation EV technologies—such as more cost-effective battery chemistries and advanced software-defined vehicle platforms—that address the cost and range barriers currently holding back mass adoption.
Conclusion
General Motors has successfully navigated one of the most expensive and turbulent strategic pivots in modern industrial history. With its $10.9 billion EV restructuring bill largely settled, a resilient cash flow engine churning out upwards of $10 billion annually, and a balance sheet fortified against economic shocks, the automaker stands prepared for whatever macroeconomic or automotive market storms lie ahead.