Beyond the Hype: Why Stablecoins Fall Short in Closing the Global Financial Inclusion Gap
SEATTLE — Over the past fifteen years, the architecture of global finance has undergone a quiet revolution. In low- and middle-income countries, account ownership has surged from a meager 42% in 2011 to 75% today. This dramatic expansion is largely attributable to the rise of innovative, low-cost banking models—most notably mobile money—which successfully dismantled technological barriers by allowing users to access accounts via basic, text-based mobile phones.
Yet, a stubborn and stark divide remains. Today, 1.3 billion adults—more than half of them women—remain entirely excluded from the formal financial system. Lower-income consumers across the developing world continue to struggle to find, access, and afford the tailored financial products and services required to build economic resilience.
In recent years, a chorus of fintech advocates and blockchain enthusiasts has aggressively touted stablecoins as the ultimate technological silver bullet—the innovation that will finally bring the world’s unbanked poor into the formal economic fold. However, a closer examination of ground-level realities, economic data, and emerging alternatives reveals that this digital asset hype is largely unwarranted. True financial inclusion will not be achieved by the latest cryptocurrency pilot, but by building open, interoperable, and data-driven financial infrastructure.
Main Facts: The Reality of Financial Inclusion and Digital Currencies
The debate surrounding stablecoins—cryptocurrencies whose values are pegged to a stable asset, typically the US dollar—often centers on their theoretical accessibility. Proponents argue that because stablecoins operate on decentralized blockchain networks, they bypass traditional banking gatekeepers, offering instant, borderless transactions.
However, the fundamental premise of these arguments collapses when measured against the baseline requirements of everyday financial inclusion:
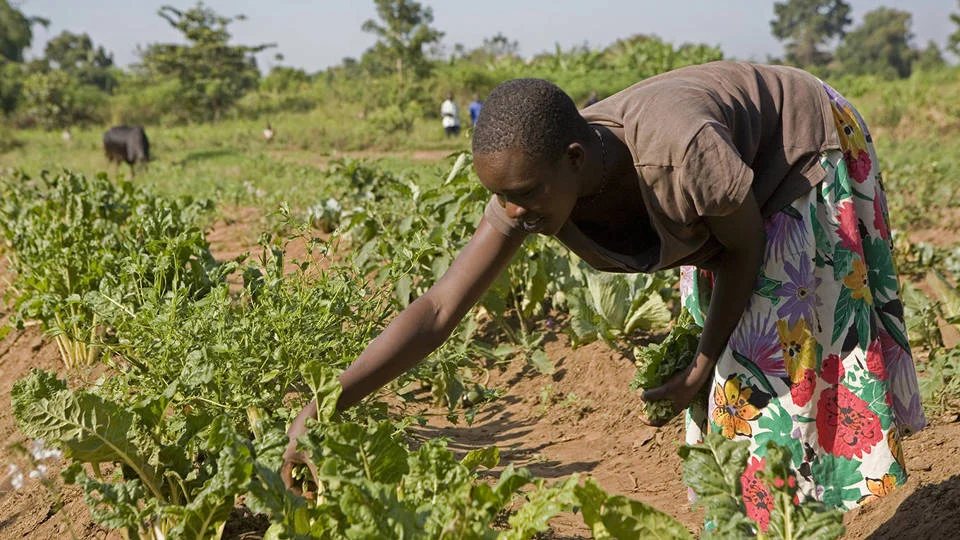
- The Accessibility Gap: Everyday domestic payments form the cornerstone of financial inclusion. While traditional mobile-money accounts can be accessed on rudimentary phones via simple USSD text messages, stablecoins demand a smartphone, reliable internet data connectivity, and a significantly higher degree of digital literacy. For a female smallholder farmer in rural Kenya equipped only with a basic feature phone, stablecoins offer zero utility.
- Transaction Realities: Data indicates that the vast majority of stablecoin transactions are not used for purchasing groceries or paying school fees, but are instead confined to speculative cryptocurrency trading and digital asset exchanges.
- The Risk Burden: Even where governments have heavily subsidized and promoted Central Bank Digital Currencies (CBDCs)—such as in China and Nigeria—uptake has remained muted. Consumers see little practical advantage over existing digital payment rails. Furthermore, stablecoins can inadvertently shift financial risk from the payer to the payee, particularly when market trading values deviate from face value.
Chronology: The Evolution of Global Financial Access
To understand why stablecoins are a misallocation of focus, it is helpful to trace how financial inclusion has historically advanced, and where global initiatives are currently concentrating their efforts:
- 2011–2015 (The Mobile Money Boom): The landscape shifted dramatically with the proliferation of telecommunications-backed financial services. Platforms like M-Pesa in East Africa demonstrated that financial access did not require brick-and-mortar bank branches; it required a network of local cash-in/cash-out agents and a basic mobile phone.
- 2018–2021 (The Rise of Cross-Border Fintech): Specialized money-transfer operators like Wise and Remitly optimized international remittances, driving down costs and making cross-border transfers more accessible to lower-income families than traditional wire services.
- 2020–Present (The Stablecoin Pitch & CBDC Experiments): Blockchain advocates began positioning stablecoins as cross-border remittance solutions. Simultaneously, major emerging economies launched state-backed digital currencies. Concurrently, international bodies began focusing on connecting domestic instant payment systems.
- The Present Day (The Data-Driven Lending Frontier): The cutting edge of financial inclusion has shifted away from payment rails and toward alternative credit scoring. By leveraging consented non-traditional data—such as satellite imagery, agricultural yields, and mobile-money transaction histories—institutions are beginning to offer collateral-free loans to previously unbanked populations.
Supporting Data: Examining Remittances, Cross-Border Payments, and Lending
Proponents frequently argue that stablecoins excel in cross-border payments, citing the ability to send dollar-backed tokens globally in seconds for minimal fees. While the technological transfer is fast, the operational reality introduces hidden frictions.
For instance, a recipient receiving stablecoins in Kampala, Uganda, must still convert those digital tokens into Ugandan shillings. The local market for stablecoin-to-fiat conversion is a minute fraction of the deep liquidity pools drawn upon by traditional banks and established money-transfer operators. Consequently, end-to-end exchange rates offered by platforms like Wise or Remitly frequently provide superior value, alongside far easier user interfaces for low-income recipients.
While traditional cross-border bank transfers remain notoriously slow and expensive, the global financial community is actively solving this through systemic integration rather than cryptocurrency adoption. The G20 Roadmap for Cross-Border Payments champions the linking of domestic instant-payment systems. A prime example is the Nexus payment system, which seamlessly links domestic instant payment infrastructures across India, Malaysia, the Philippines, Singapore, and Thailand.
Furthermore, data is revolutionizing credit access. In Ethiopia, regulatory reforms permitting secure data exchange enabled the Cooperative Bank of Oromia to launch "Michu," a lending product that evaluates borrowers based on transaction data rather than traditional physical collateral. Within its first year, Michu built a customer base where over one-third of the borrowers were women.
Official Responses and Policy Initiatives
Governments and institutional funders are increasingly recognizing that sustainable financial inclusion requires structural regulatory reform and data infrastructure rather than speculative digital assets.
Agricultural financing provides a compelling blueprint. Farmers historically struggle to secure loans because traditional banking models demand extensive transaction histories, despite most agricultural commerce occurring in cash. To bridge this gap, governments are scaling up data collection on land ownership, crop variations, and localized weather patterns verified via satellite imagery—data originally gathered for agronomic advisory services.
When shared with explicit consumer consent, these datasets allow lenders to accurately project a farmer’s income and structure loan repayments to align precisely with their seasonal cash-flow cycles.
A notable institutional response is Ethiopia’s National Agri-Finance Implementation Roadmap (NAFIR). Launched jointly by the National Bank of Ethiopia and the Ministry of Agriculture, NAFIR supplies lenders with structured, actionable data via the OpenAgriNet system. By utilizing these predictive models, lenders can identify high-value opportunities for farmers—such as investing in solar-irrigation pumps—which simultaneously lowers default risks, reduces loan pricing, and increases agricultural yields.
Similar data-driven methodologies are being deployed to revolutionize agricultural insurance. Instead of forcing farmers to wait months for a claims adjuster to assess crop damage following a drought, insurers utilize satellite verification to trigger automatic, instant payouts the moment dry-spell thresholds are crossed.
Implications: The Path Forward for Global Finance
The trajectory of global financial inclusion will not be determined by which cryptocurrency or stablecoin achieves dominance. Rather, it will be decided by the openness, competitiveness, and interoperability of our broader financial systems.
To genuinely close the remaining 1.3-billion-person gap, stakeholders must pivot their focus toward three foundational pillars:
- Interoperable Infrastructure: Policymakers must prioritize building and funding robust, interoperable payment rails that allow commercial banks, mobile-money providers, and modern fintech firms to exchange funds frictionally, both domestically and across borders.
- Regulatory and Data Capacity: International funders must direct capital toward strengthening regulatory frameworks and secure data-sharing infrastructure. While less glamorous than launching a high-profile cryptocurrency pilot, these investments yield exponential systemic impact.
- Product Innovation Over Asset Focus: Financial institutions must leverage alternative, consented data to design innovative products tailored to the real-world economic needs and income-generating opportunities of low-income populations—moving far beyond legacy models that prioritize past wealth or physical collateral.
Ultimately, the democratization of finance does not require inventing a new currency from scratch. It requires opening up the pipes, connecting existing systems, and putting actionable data to work for the people who need it most.