The Fiscal Precipice: How America’s Mounting Debt Threatens Future Stability
By Kenneth Rogoff
Published: October 1, 2026
Section: Economics / Global Finance
Main Facts
High national debt levels do not inherently spell immediate doom for a sovereign superpower, but they transform into systemic hazards when macroeconomic conditions shift—specifically when rising interest rates compound borrowing costs while policymakers remain paralyzed by political inaction.
In the United States, this dynamic has moved from a theoretical long-term concern to an acute vulnerability. Despite a backdrop of sustained economic growth, the U.S. federal deficit hovers stubbornly at approximately 6% of Gross Domestic Product (GDP). Rather than using periods of economic expansion to rebuild fiscal buffers, the federal government continues to run massive budget shortfalls.
Under the administration of President Donald Trump, the political appetite for fiscal consolidation or deficit reduction is virtually nonexistent. Instead, tax cuts, spending commitments, and political pressures to maintain short-term economic momentum have taken precedence.
Consequently, America’s fiscal trajectory resembles a high-speed locomotive hurtling along a winding mountain track, with engineers too afraid to touch the brakes for fear of political fallout. Even if an immediate catastrophe is avoided, economists increasingly question the rationale of pushing the debt burden ever higher when the economy is not in crisis. When the next inevitable shock—whether a severe recession, a financial panic, or a major geopolitical conflict—arrives, the United States risks finding its policy toolkit dangerously depleted.
Chronology of the Modern U.S. Debt Build-Up
To understand how the United States arrived at its current fiscal impasse, it is necessary to examine the historical milestones that accelerated federal borrowing over the past two decades.
- 2007–2009 (The Global Financial Crisis): The Great Recession marked a turning point in modern fiscal policy. To rescue the domestic banking system and stimulate aggregate demand, the federal government deployed massive rescue packages, driving the national debt sharply upward as tax revenues plummeted.
- 2017 (The Tax Cuts and Jobs Act): Under the first Trump administration, sweeping tax reforms lowered corporate and individual tax rates. While proponents argued the cuts would pay for themselves through accelerated growth, independent fiscal watchdogs noted that the legislation added trillions of dollars to the long-term national debt projections.
- 2020–2021 (The Pandemic Response): The COVID-19 pandemic necessitated unprecedented fiscal intervention. Bipartisan relief packages totaling over $5万 billion flooded the economy, preventing a total depression but pushing the national debt-to-GDP ratio past 100% for the first time since World War II.
- 2022–2024 (The Inflation Shock and Rate Hikes): To combat post-pandemic inflation, the U.S. Federal Reserve embarked on one of the most aggressive tightening cycles in its history, raising the federal funds rate from near-zero to over 5%. This shift drastically increased the servicing costs on the newly accumulated national debt.
- 2025–2026 (The Current Impasse): Entering 2026, despite solid headline GDP growth and a resilient labor market, federal deficits remain structurally stuck at roughly 6% of GDP. Political polarization and election-cycle pressures block any meaningful legislative efforts toward fiscal discipline.
Supporting Data and Economic Metrics
The severity of the current U.S. fiscal position is best illustrated by hard economic data compiled by nonpartisan budget institutions, central banks, and international financial bodies.
- The Deficit-to-GDP Ratio: At approximately 6%, the current U.S. federal deficit is historically high for a non-recessionary period. Standard macroeconomic theory dictates that governments should run surpluses or low deficits during economic expansions to create "fiscal space" for downturns.
- Interest Payments vs. Discretionary Spending: Net interest payments on the federal debt have exploded. In recent fiscal years, servicing the national debt has surpassed total spending on national defense, consuming an unprecedented share of federal tax revenues. Every dollar spent paying interest on past borrowing is a dollar that cannot be allocated toward infrastructure, education, research, or national security.
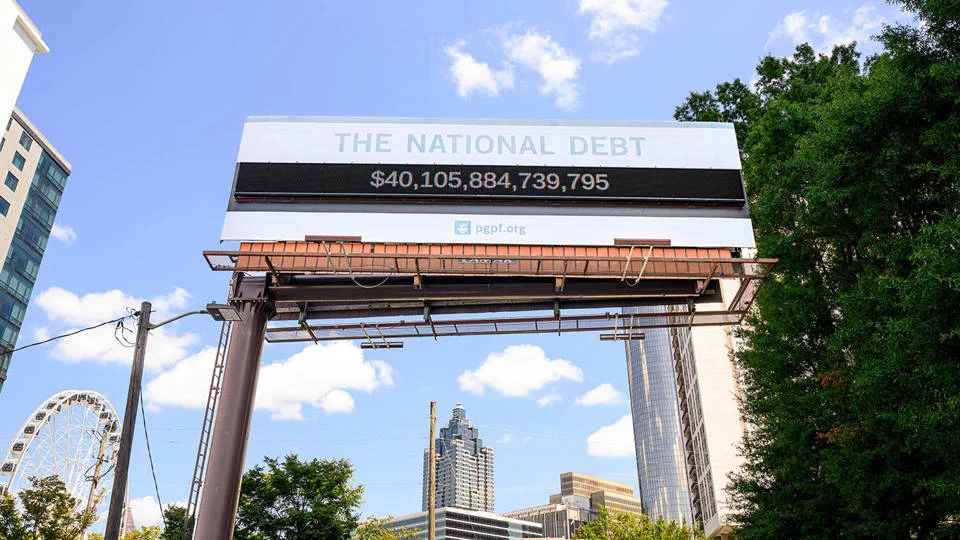
- Debt-Held-by-Public Projections: According to projections by organizations like the Committee for a Responsible Federal Budget (CRFB) and the Congressional Budget Office (CBO), the debt-to-GDP ratio is on a relentless upward path, threatening to surpass historic post-WWII highs within the decade.
- Global Comparisons: While other advanced economies—such as Japan and several European nations—also grapple with high debt loads, the unique status of the U.S. dollar as the world’s primary reserve currency has historically insulated America from sudden capital flight. However, economists warn that this exorbitant privilege is not infinite and can erode if domestic fiscal governance deteriorates too far.
Official Responses and Political Realities
The political landscape in Washington reveals a deep disconnect between economic warning signs and policy action.
The Executive Branch Perspective
The administration of President Donald Trump has consistently prioritized pro-growth policies centered on deregulation, domestic energy production, and tax competitiveness. From the White House’s viewpoint, aggressive fiscal austerity risks choking off economic momentum. Proponents of current policies argue that nominal GDP growth will ultimately outpace the growth of the debt, rendering the debt-to-GDP ratio manageable over the long term. Furthermore, political leaders face fierce voter resistance to any proposals that involve cutting popular entitlement programs or raising broad-based taxes.
Congressional Gridlock
In Congress, partisan divisions preclude comprehensive fiscal reform. While fiscal conservatives routinely sound the alarm over soaring deficits, they are often divided on where to cut spending—with defense, healthcare, and social security representing untouchable "third rails" of American politics. Meanwhile, progressive lawmakers advocate for increased federal investment financed by higher taxes on corporations and high-income earners, but these proposals lack the bipartisan consensus required to pass a deeply divided legislature.
Independent Watchdogs and Central Bankers
Federal Reserve officials, while maintaining political neutrality, have repeatedly cautioned that unsustainable fiscal trajectories could complicate monetary policy. When high government borrowing coincides with persistent inflation, central banks find themselves caught between fighting price pressures and preventing disorderly disruptions in sovereign debt markets. Independent watchdogs, such as the Peterson Foundation and the CRFB, continue to issue urgent advisories, warning that waiting for a full-blown crisis before addressing the deficit will leave lawmakers with agonizingly painful choices.
Implications for the Future
The compounding nature of high debt and rising interest rates carries profound implications for the domestic and global economy.
1. The Shrinking Policy Toolkit
When the next major crisis hits—whether it is a geopolitical conflict, a severe recession, or a financial panic—governments traditionally rely on massive fiscal stimulus to stabilize society and markets. A nation already running a 6% deficit with a debt-to-GDP ratio scaling historic peaks has severely compromised its fiscal firepower. Attempting to borrow trillions more during an emergency could trigger a loss of confidence in U.S. Treasury securities, leading to spiking bond yields, currency depreciation, and imported inflation.
2. Crowding Out Private Investment
As the federal government continuously floods the market with new Treasury issuances to finance its deficits, it absorbs a massive share of available global savings. This dynamic can "crowd out" private-sector investment by driving up real interest rates. Businesses seeking capital for innovation, green energy transitions, and technological research face higher borrowing costs, ultimately dragging down long-term productivity growth.
3. Vulnerability to Shocks
Financial markets are notoriously fickle when it comes to sovereign debt. While the U.S. dollar remains the bedrock of international trade and finance, prolonged fiscal negligence invites creeping skepticism from foreign central banks and institutional investors. A sudden shift in market sentiment could force a rapid and disorderly adjustment, characterized by austerity measures forced not by political foresight, but by market panic.
Conclusion
America’s fiscal train is racing along a treacherous route. While the tracks appear stable for the moment, the refusal of political leaders to tap the brakes during a period of economic growth is a dangerous gamble. Without a renewed commitment to medium-term fiscal sustainability, the United States risks sacrificing its economic resilience and leaving future generations to navigate a crisis of avoidable proportions.