Navigating the AI Paradox: Artificial Intelligence, Sectoral Shifts, and the Future of the Renminbi’s Real Exchange Rate
By Miao Yanliang
Published: September 30, 2026
Section: Economics
Main Facts
The intersection of artificial intelligence (AI) and macroeconomic policy is reshaping structural economic debates across the globe, but nowhere is the dynamic more complex than in China. As Beijing accelerates its national strategy to integrate advanced machine learning, automated logistics, and generative AI into the broader economy, economists are increasingly focused on where these productivity gains will manifest.
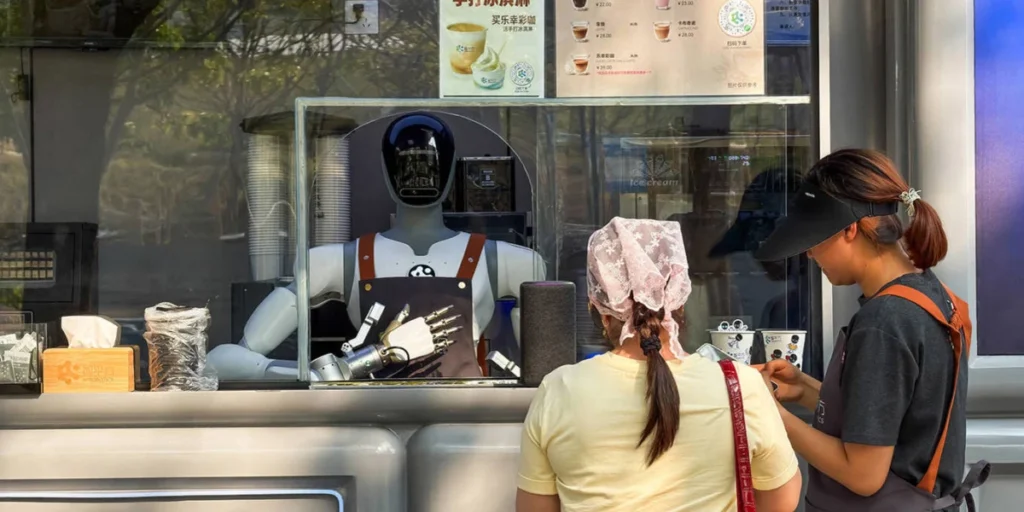
According to leading economic analyses, the primary productivity dividends of AI in China are poised to materialize not within the high-profile tradable manufacturing sector—where automation and digital efficiencies are already relatively mature—but within the sprawling, domestically focused non-tradable services sector. This shift carries profound implications for relative price dynamics, domestic consumption, and international trade balances.
Specifically, rapid technological advancement in services—such as healthcare, education, legal consulting, hospitality, and domestic logistics—is expected to drive down the relative prices of these non-tradable goods and services. Under traditional macroeconomic frameworks, such a deflationary structural shock in the non-tradable sector relative to trading partners exerts downward pressure on the real effective exchange rate (REER) of the renminbi.
However, this downward pressure on relative prices presents a major policy puzzle. If lower prices in services translate directly into suppressed nominal income growth for workers in those sectors, domestic demand could falter, exacerbating China’s historical structural imbalance of high savings and insufficient domestic consumption.
Consequently, a central policy imperative for Beijing in the coming years will be ensuring that the unprecedented productivity gains generated by AI are not monopolized by capital or restricted to select technological conglomerates, but are instead broadly and equitably shared across the workforce. Doing so is the single most effective way to decouple technological deflation from economic stagnation, guaranteeing that productivity-driven price adjustments do not come at the expense of household income and aggregate demand.
Simultaneously, these structural real-economy dynamics play out against a backdrop of recent currency fluctuations. Following a volatile period in the early 2020s, the renminbi has staged a notable and sustained recovery against the United States dollar since the second half of 2025. This rebound has revitalized debate among currency traders, institutional investors, and policymakers regarding the currency’s medium-term trajectory, its vulnerability to external shocks, and how technological shocks will interact with traditional monetary policy levers.
Chronology: The Evolution of China’s Currency and AI Integration Strategy
To understand how artificial intelligence intersects with the renminbi’s valuation in 2026, it is vital to trace the institutional and market milestones that have defined China’s economic landscape over recent years.
-
2021–2022: The Post-Pandemic Divergence and Monetary Divergence
As global central banks aggressively raised interest rates to combat post-pandemic inflation, the People’s Bank of China (PBOC) maintained a relatively accommodative monetary stance to support domestic growth, which was weighed down by protracted real estate adjustments. This monetary policy divergence created persistent downward pressure on the renminbi, testing the central bank’s management capabilities. -
2023: The Generative AI Boom and National Strategy Formulation
Following the global explosion of generative AI applications, the Chinese government elevated the "Digital China" initiative and AI integration to top national priorities. Industrial policy began heavily subsidizing computing power, semiconductor domestic substitution, and AI research and development. However, early applications focused heavily on industrial automation and export-oriented manufacturing optimization. -
2024: Broadening the Technological Scope
Recognizing the limits of manufacturing-only automation, policymakers and industry leaders began aggressively pushing AI adoption into service-oriented industries. Financial technology, automated customer service, AI-assisted healthcare diagnostics, and smart urban administration emerged as primary testing grounds for productivity enhancement. -
Second Half of 2025: The Renminbi Rebound
Driven by stabilizing property market indicators, structural current account surpluses, and shifting expectations regarding global monetary easing, the renminbi began a decisive recovery against the greenback. This resurgence broke prolonged bearish sentiment and triggered intense debate in financial circles regarding the currency’s fair value and long-term appreciation ceiling. -
Early to Mid-2026: The Productivity-Exchange Rate Nexus Emerges
By 2026, economists began modeling the macroeconomic feedback loops of widespread service-sector AI adoption. Analysts increasingly noted that while AI boosts total factor productivity (TFP), its differential impact on tradable versus non-tradable sectors creates unique pressures on the real exchange rate, setting the stage for the current policy debate on income distribution and demand generation.
Supporting Data: Macroeconomic Indicators and Sectoral Projections
Evaluating the structural shift in China’s economy requires examining empirical data concerning productivity differentials, exchange rate movements, and sector-specific contributions to Gross Domestic Product (GDP).
1. Renminbi Performance Against the US Dollar (2025–2026)
- Q3 2025: The offshore renminbi (CNH) touched cyclical lows before finding a robust technical and fundamental floor, moving into a sustained appreciation channel.
- H1 2026: Backed by persistent trade surpluses and moderated capital outflows, the renminbi appreciated by approximately 4.2% against a basket of major trading partner currencies on a nominal basis.
- Current Standing (September 2026): The currency trades within a stable band, though analysts note a widening divergence between its nominal strength and the theoretical adjustments implied by structural productivity shocks in non-tradable services.
2. Sectoral Productivity and Price Dynamics
- Manufacturing (Tradable Sector): Having absorbed decades of industrial robot integration and digital supply chain management, annual TFP growth in manufacturing is projected to normalize at around 3.5% to 4.5%.
- Services (Non-Tradable Sector): Historically characterized by Baumol’s cost disease—where productivity lags behind manufacturing, leading to persistently rising relative prices—the services sector is experiencing a structural break. AI integration in areas such as legal tech, automated translation, digital finance, and routine medical screening is projected to jolt service-sector TFP growth to upwards of 5% annually through 2030.
- The Balassa-Samuelson Effect Inverted: Traditional economic theory dictates that higher productivity in tradable goods drives up real exchange rates. However, because China’s AI-driven productivity surge is concentrated heavily in non-tradable services, the relative price of services falls. This compresses the domestic consumer price index (CPI) relative to trading partners, dampening the real exchange rate unless nominal adjustments offset the shift.
3. Consumption and Income Share Metrics
- Household Income Share: Household consumption as a percentage of GDP in China has historically hovered near 38–40%, significantly below the global average of roughly 60%.
- Wage Distribution Vulnerability: Empirical studies on technological displacement indicate that without proactive fiscal redistribution, early-stage AI adoption in services risks widening the skill premium, leaving routine-service workers vulnerable to wage stagnation or displacement.
Official Responses and Policy Perspectives
Policymakers in Beijing, alongside central bankers at the People’s Bank of China and researchers at premier economic institutions, are actively debating how to navigate the complex feedback loop between technological innovation, currency valuation, and domestic economic rebalancing.
The People’s Bank of China (PBOC) Perspective
Monetary authorities have consistently emphasized the importance of maintaining basic stability in the renminbi’s exchange rate within a managed floating exchange rate regime based on market supply and demand, referenced to a basket of currencies.
Senior PBOC officials have noted that while capital flows and market sentiment dictate short-term fluctuations, long-term currency valuation is anchored by fundamental economic productivity. Regarding the AI-driven productivity shift in non-tradable services, central bank researchers have pointed out that monetary policy alone cannot resolve structural imbalances. If technological deflation pulls down the real exchange rate, the central bank must coordinate closely with fiscal authorities to ensure that monetary easing does not inadvertently fuel asset bubbles, but instead supports the real economy’s transition.
Ministry of Finance and Structural Reform Agencies
The National Development and Reform Commission (NDRC) and the Ministry of Finance have increasingly focused on the distributional aspects of the digital and AI economy. Recognizing that technological efficiency can inadvertently widen wealth inequality if gains accrue solely to capital owners, official policy guidelines have emphasized:
- Inclusive Digital Infrastructure: Subsidizing small and medium-sized enterprises (SMEs) in the service sector to adopt AI tools, preventing monopolistic concentration.
- Labor Market Reskilling: Launching nationwide vocational training programs aimed at transitioning routine service workers into roles that complement, rather than compete with, artificial intelligence.
- Social Safety Net Enhancement: Expanding unemployment insurance, healthcare access, and pension support to buffer against transitional labor market shocks caused by automation.
Implications: What the AI-Renminbi Nexus Means for the Global Economy
The convergence of artificial intelligence, sectoral productivity shifts, and renminbi dynamics carries profound implications not only for China’s domestic economic stability but also for global trade, multinational corporations, and international financial markets.
1. For China’s Domestic Rebalancing
The holy grail of China’s macroeconomic policy for over a decade has been transitioning from an investment- and export-driven growth model to one anchored by domestic consumption. If AI-driven productivity gains in services lead strictly to falling prices without corresponding increases in disposable income, the structural propensity to save will intensify, frustrating efforts to rebalance the economy.
Conversely, if policymakers successfully implement redistribution policies—such as strengthening public services, enhancing social security transfers, and supporting wage growth—the productivity dividend will directly translate into higher household consumption. This would establish a virtuous cycle of sustainable, consumption-led growth.
2. For International Competitiveness and Trade Partners
The downward pressure on the renminbi’s real exchange rate stemming from falling non-tradable service prices could enhance the international price competitiveness of Chinese goods and services. For global trading partners—particularly the United States, the European Union, and emerging market economies—this dynamic could renew trade frictions. If cheaper services and globally competitive manufactured goods flood international markets, foreign protectionist pressures could mount, complicating geopolitical and trade relations.
3. For Global Investors and Multinational Corporations
For global capital markets, understanding the unique mechanics of China’s AI economy is essential. Foreign investors evaluating renminbi-denominated assets must look beyond traditional nominal interest rate differentials and trade balance figures. They must assess how effectively Chinese policymakers manage the structural transition of the service economy.
Multinational corporations operating within China face both immense opportunities and steep adjustment costs. Firms that successfully leverage China’s advanced AI infrastructure in the service sector can achieve unprecedented operational efficiencies. However, they must also navigate a rapidly evolving regulatory environment designed to ensure that technological progress aligns with Beijing’s overarching goals of "Common Prosperity" and social stability.
Conclusion
The notable recovery of the renminbi since late 2025 marks an important chapter in China’s post-pandemic economic stabilization, but it is merely a surface indicator of deeper structural undercurrents. As artificial intelligence fundamentally reshapes the productivity landscape—shifting its epicenter from tradable manufacturing to non-tradable services—China faces a historic structural choice.
By proactively ensuring that the technological dividend is broadly shared across society rather than sequestered within capital-intensive tech pillars, Beijing can neutralize the deflationary risks threatening household incomes and domestic demand. In doing so, China can master the AI paradox, securing a resilient, consumption-driven economic future while maintaining macroeconomic and currency stability in an increasingly complex global order.