Market Sentiment, Economic Data, and Portfolio Strategy: Inside the September 14, 2026 Financial Roundup
By Global Financial Dispatch
Published: September 14, 2026
1. Main Facts
On September 14, 2026, financial analyst and author Ben Carlson released his latest market and economic insights via his regular publishing platform, coinciding with a sponsored edition of the Talk Your Book segment, proudly brought to market participants by global asset manager VanEck.
The update captures a critical juncture in the 2026 macroeconomic landscape. As central banks navigate shifting inflationary pressures, sticky employment metrics, and evolving global liquidity trends, retail and institutional investors alike are searching for clarity. Carlson’s latest installment zeroes in on the vital intersection between fundamental market data and investor psychology—frequently referred to in financial commentary as "animal spirits."
At the core of this release is a deep dive into empirical market charts detailing recent asset class movements, valuation spreads, and macroeconomic indicators. While the digital release serves as an accompaniment to a broader audio broadcast on The Compound’s network, the standalone data points provide a vivid snapshot of where financial markets stand heading into the final stretch of 2026.
Sustained interest in alternative assets, shifting fixed-income dynamics, and equity market resilience have created a complex mosaic for portfolio managers. Through the lens of VanEck-sponsored commentary and visual analytical charts, market observers are being forced to re-evaluate traditional asset allocation models in a high-information, fast-moving digital age.
2. Chronology of Market Events Leading to September 2026
To understand the weight of the data presented in mid-September 2026, it is essential to trace the economic trajectory that preceded it:
- Q1 2026: Markets opened the year grappling with persistent core inflation prints that repeatedly dashed hopes for aggressive, front-loaded interest rate cuts by major global central banks. Equity indices nonetheless demonstrated stubborn resilience, propelled heavily by technology and infrastructure sectors tied to ongoing artificial intelligence and energy transition capital expenditures.
- Late Spring 2026: Macroeconomic sentiment experienced bouts of volatility as labor market reports began showing signs of normalization rather than a hard landing. Bond yields fluctuated wildly in response to shifting treasury issuance schedules and stubborn consumer price index (CPI) prints.
- July – August 2026: Summer trading volumes brought typical seasonal lulls, though underlying institutional positioning grew increasingly defensive. Investors began rotating out of high-flying growth darlings into value and dividend-paying sectors, hedging against potential late-year geopolitical and fiscal headwinds.
- Early September 2026: As desks returned from the late-summer break, economic data releases clustered heavily. Analysts were tasked with parsing mixed manufacturing indices against robust consumer spending figures.
- September 14, 2026: Ben Carlson and financial media networks published their weekly deep-dives, highlighting the exact visual charts and market trends defining the autumn trading environment. Against this backdrop, sponsors like VanEck stepped in to frame discussions surrounding thematic investing, hard assets, and modern portfolio theory.
3. Supporting Data and Visual Analysis
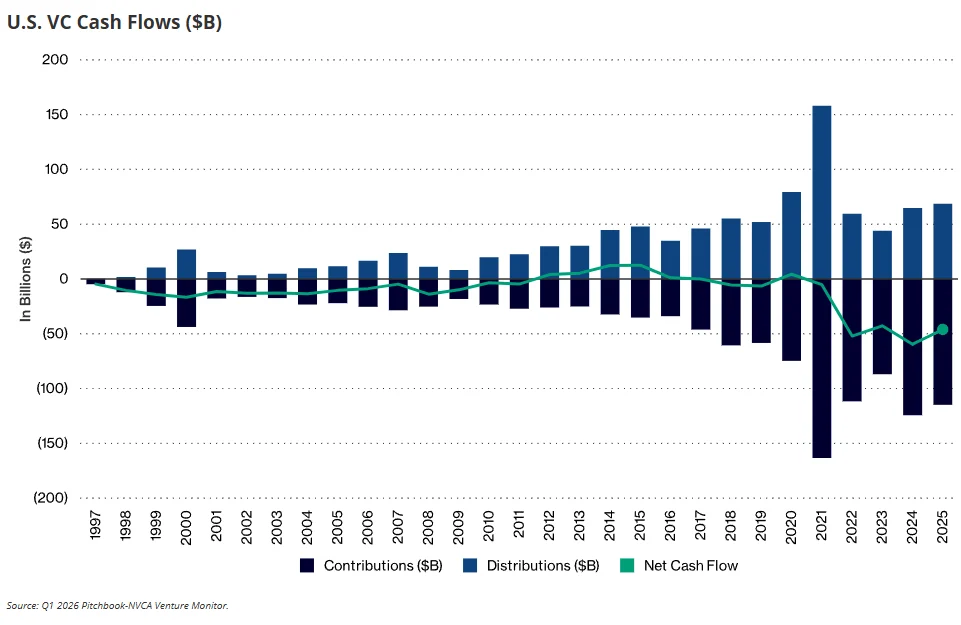
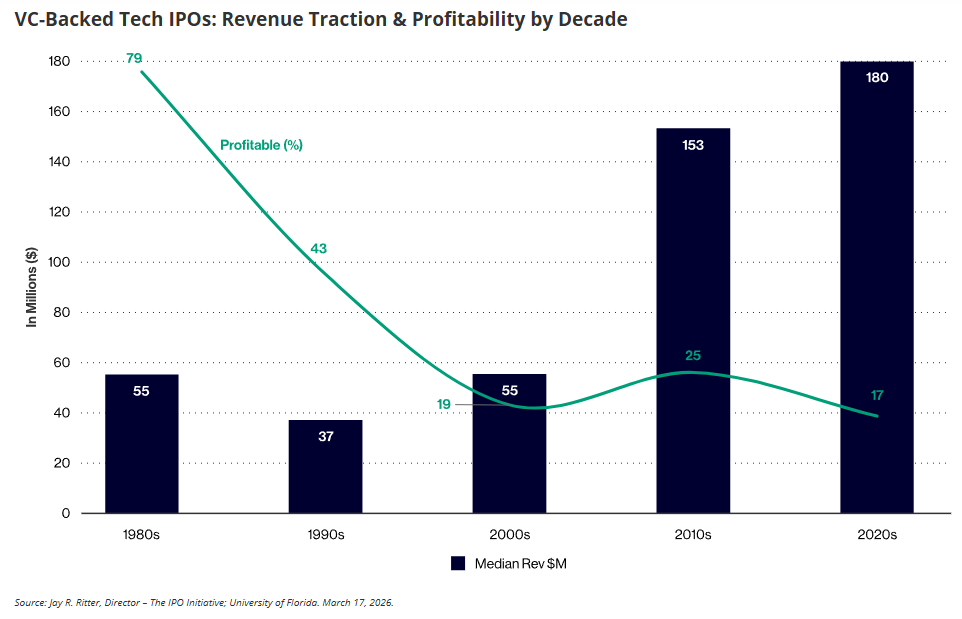
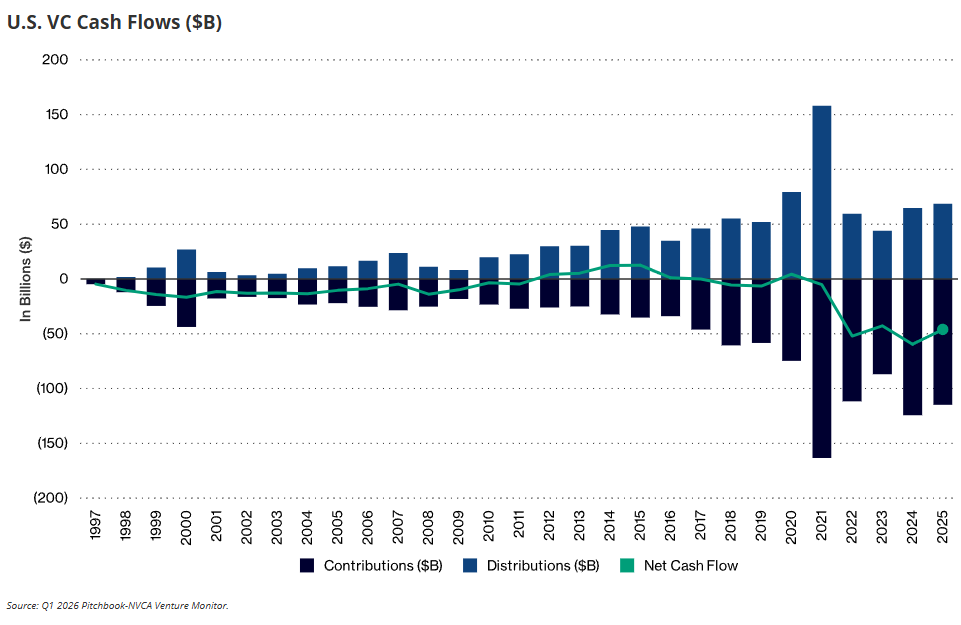
A significant portion of the September 14 release centers on raw visual data. While the accompanying podcast offers qualitative debate, the five core charts published alongside the commentary tell a compelling quantitative story about the current state of wealth management, risk appetite, and market pricing.
Analyzing the Charts of September 2026
- Macroeconomic Trend Momentum (Chart 1): The initial data graphic tracks multi-year momentum indicators across broader equity benchmarks. It illustrates a narrowing breadth in market leadership, where a select group of mega-cap entities continue to command disproportionate index weightings, contrasting sharply with the broader pool of mid- and small-cap equities struggling to break out of prolonged consolidation ranges.
- Fixed Income and Yield Curve Dynamics (Chart 2): The second chart shifts focus to the debt markets, mapping the trajectory of sovereign bond yields across short- and long-duration spectrums. The data highlights the market’s ongoing digestion of term premium normalization, indicating that investors are demanding higher compensation for holding long-term sovereign debt in an era of elevated structural government deficits.
- Sector Valuation Spreads (Chart 3): Providing a granular look at sector-by-sector pricing, this graphic highlights historical valuation percentiles. Technology and defensive healthcare remain at elevated valuations relative to their historic medians, whereas cyclical sectors—such as industrials and select commodities—trade at discounts that suggest the market is pricing in a mild economic deceleration.
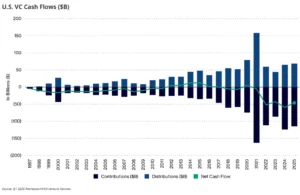
- Global Liquidity and Capital Flows (Chart 4): This metric maps cross-border capital movements and institutional fund flows. Notably, it captures the steady, if uneven, migration of capital into alternative asset classes, exchange-traded funds (ETFs) with specialized thematic mandates, and digital asset infrastructure, signaling that modern allocators are looking beyond traditional 60/40 stock-bond frameworks.
- Investor Sentiment and Volatility Metrics (Chart 5): The final chart aggregates behavioral sentiment indicators, measuring put/call ratios, retail participation indices, and institutional cash buffers. It paints a picture of cautious optimism: while investors are not aggressively bailing out of risk assets, they maintain a high degree of downside protection via options markets, reflecting underlying nervousness regarding sudden macroeconomic shocks.
4. Official Responses and Industry Commentary
While individual commentary pieces like Carlson’s platform operate independently of central bank boardrooms, they reflect the broader discourse pulsing through the wealth management industry.
Representatives from institutional sponsors like VanEck have frequently emphasized the necessity of thematic diversification in modern portfolios. In statements accompanying institutional research notes throughout Q3 2026, product strategists highlighted that traditional diversification models are under strain due to elevated correlations between equities and fixed income during inflationary spikes. Consequently, asset managers are urging advisors to incorporate real assets, commodities, and targeted global equities to insulate portfolios against regime shifts.
Financial advisory networks, including Ritholtz Wealth Management (an affiliate of The Compound Media, Inc.), maintain a strict compliance boundary regarding commentary, ensuring that all distributed media—including sponsored podcasts and blog summaries—adhere to rigorous disclaimers.
Official compliance guidelines reiterated in the September 14 publication stress that:
- No content constitutes personalized investment advice or formal performance guarantees.
- Mentions of specific securities or historical performance metrics are strictly educational or analytical in nature and do not amount to a solicitation to buy or sell.
- Paid sponsorships (such as those by VanEck) help fund independent digital media production but do not imply institutional endorsement of the sponsor’s underlying financial products by the content creators or affiliated wealth management firms.
5. Broader Implications for Investors and Markets
The convergence of data points, chart analysis, and market sentiment captured in the September 14, 2026 update carries several critical takeaways for long-term investors navigating the remainder of the decade:
1. The Death of Set-It-and-Forget-It Traditional Portfolios
The traditional 60/40 portfolio (60% equities, 40% fixed income) faced unprecedented stress tests during the inflationary surges of the mid-2020s. As fixed income yields normalize but remain susceptible to inflation surprises, investors can no longer rely solely on bonds to act as a foolproof ballast during equity market drawdowns. The charts underline the necessity of incorporating non-correlated assets, alternative strategies, and dynamic risk management overlays.
2. The Rise of Thematic and Specialized Investing
With market leadership concentrating and macroeconomic trends shifting rapidly—driven by technological disruption, supply chain reconfiguration, and energy transitions—investors are increasingly turning to specialized ETFs. Sponsors like VanEck capitalize on this trend by providing targeted exposure to structural growth themes that transcend traditional geographic and sector boundaries.
3. Balancing Emotional Discipline with Quantitative Rigor
"Animal spirits"—the emotional undercurrents of fear, greed, and confidence that drive market cycles—remain as potent in 2026 as ever. The visual data highlights that while valuations are stretched in specific pockets, structural economic growth continues to support corporate earnings. Maintaining emotional discipline, avoiding reactive trading during volatility spikes, and adhering to systematic rebalancing remain the bedrock principles for individual wealth preservation.
Summary
As financial markets chart their course through the final months of 2026, resources like Ben Carlson’s data-driven breakdowns and VanEck-sponsored discussions provide a vital compass. By examining the raw visual evidence of asset performance, bond yields, and sentiment indicators, investors are better equipped to look past daily market noise and focus on long-term wealth creation strategies.